Affordability crisis has softened in markets where home prices have fallen for a few years and hourly earnings have risen, but has worsened in others.
By Wolf Richter for WOLF STREET.
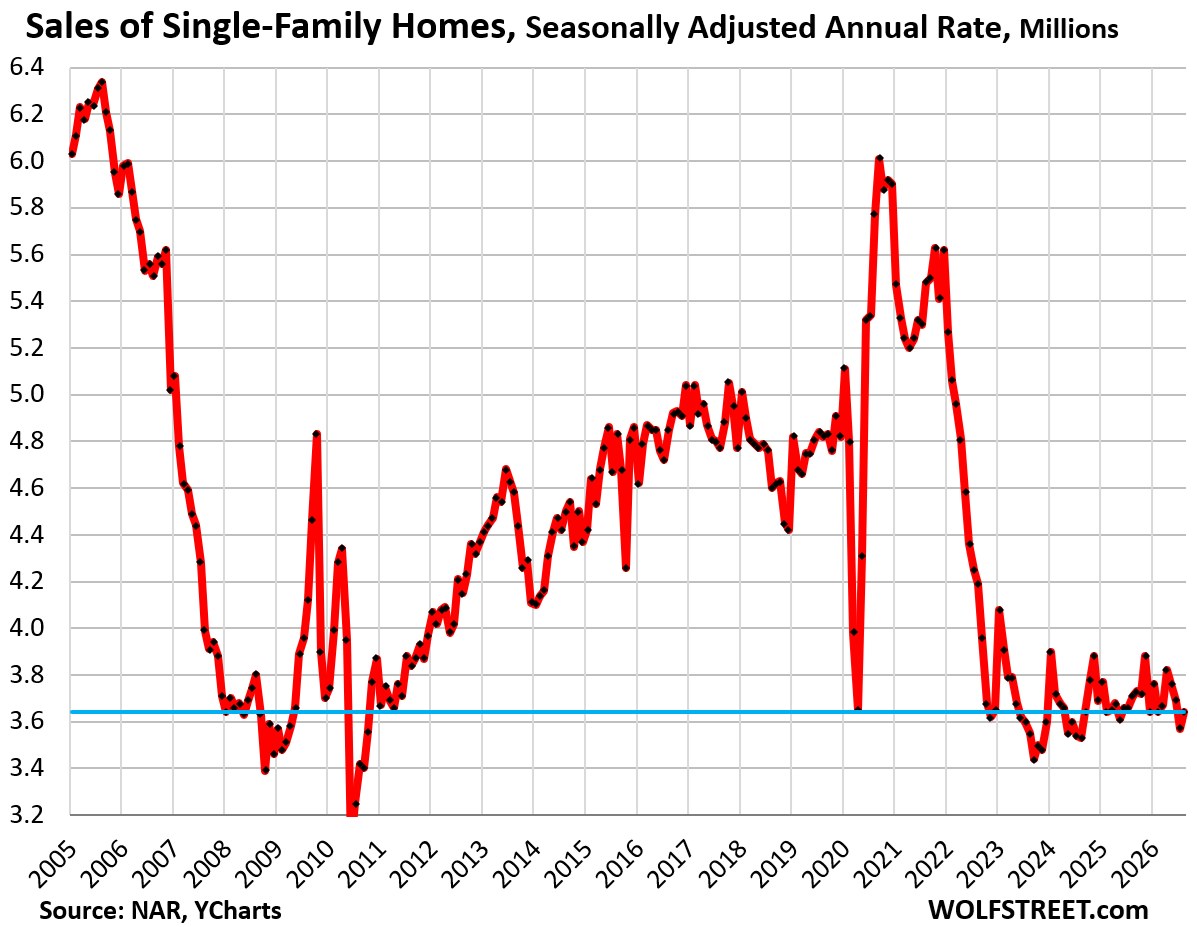
Sales of existing single-family homes in September continued scraping along the very bottom of the four-year dumpster. In September, sales fell by 1.9% from the already beaten-down levels a year ago, the second month in a row of year-over-year declines, to a seasonally adjusted annual rate of 3.64 million sales, according to data by the National Association of Realtors today.
On a month-to-month basis, sales ticked up from the downwardly revised August (revised down the lowest since September 2024).
Sales were down by 24% from September 2019, by 34% from September 2021, by 12% from September 2009 during the Housing Bust, and by 2% from 30 years ago in September 1996.
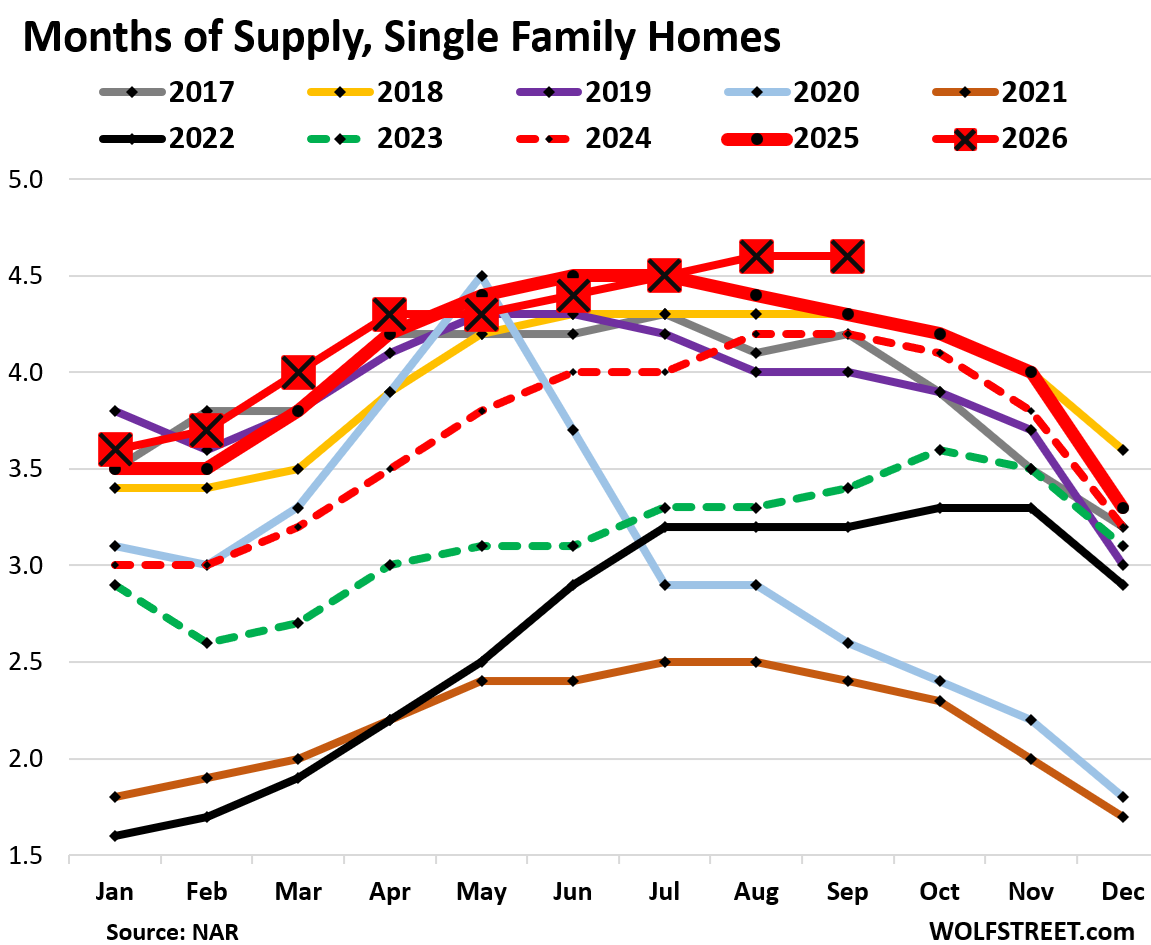
Supply of single-family homes, at 4.6 months in September, was the highest for any September since September 2015 (4.8 months).
Supply is a function of inventory and sales – how much inventory there was at month-end in relationship to sales during the month.
The stacked chart shows 2026 in red with big red squares, 2025 with the fat red line, and 2024 with the dotted red line. Supply has increased year after year, every single year, since the low point in 2021 (2.4 months, brown line at the bottom):
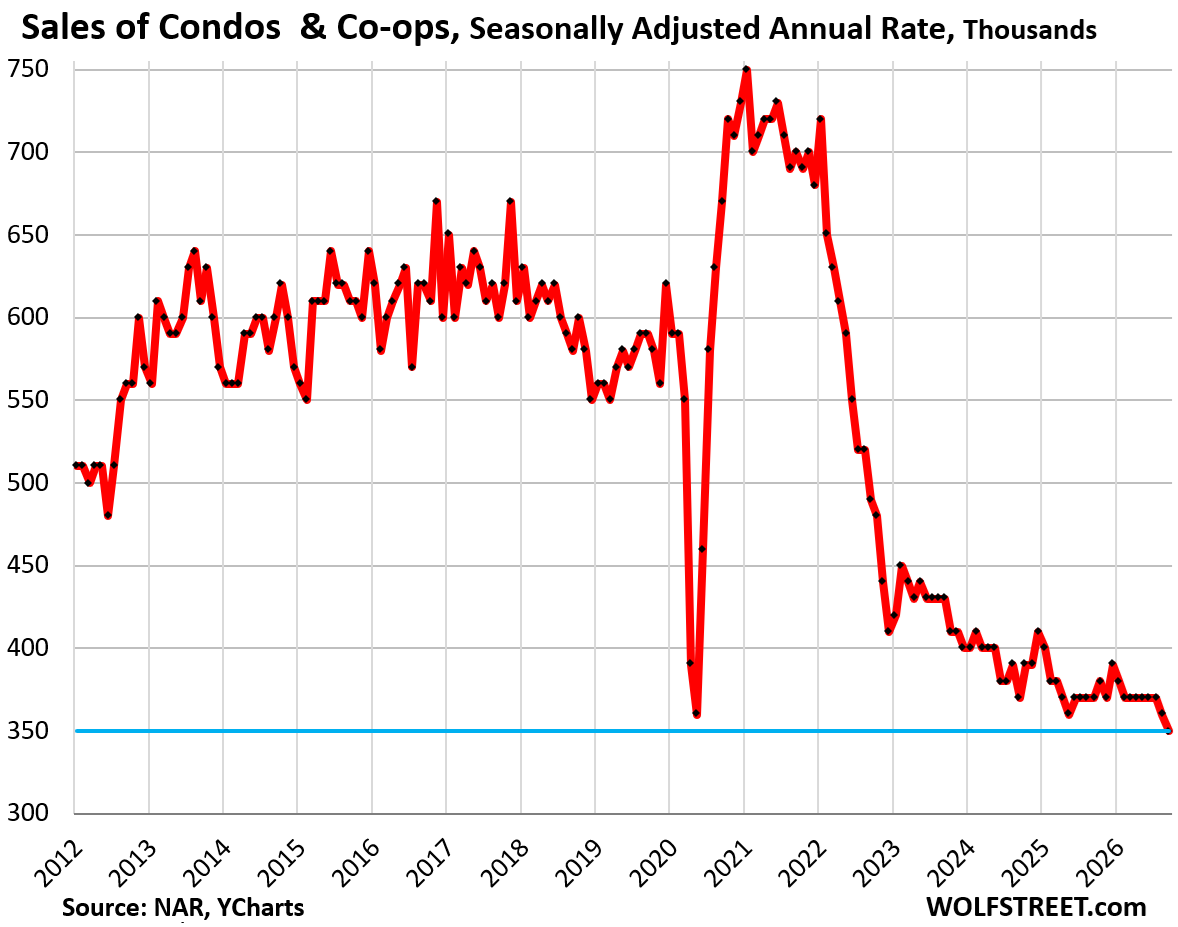
Sales of condos and co-ops fell by 2.8% in September from August, seasonally adjusted, to an annual rate of 350,000, a record low in the data that go back only to late 2011.
Compared to the already collapsed levels a year ago, sales fell by another 5.4%. Compared to September 2019, sales collapsed by 41%. Compared to September 2012, the first September in the data, sales collapsed by 38%.
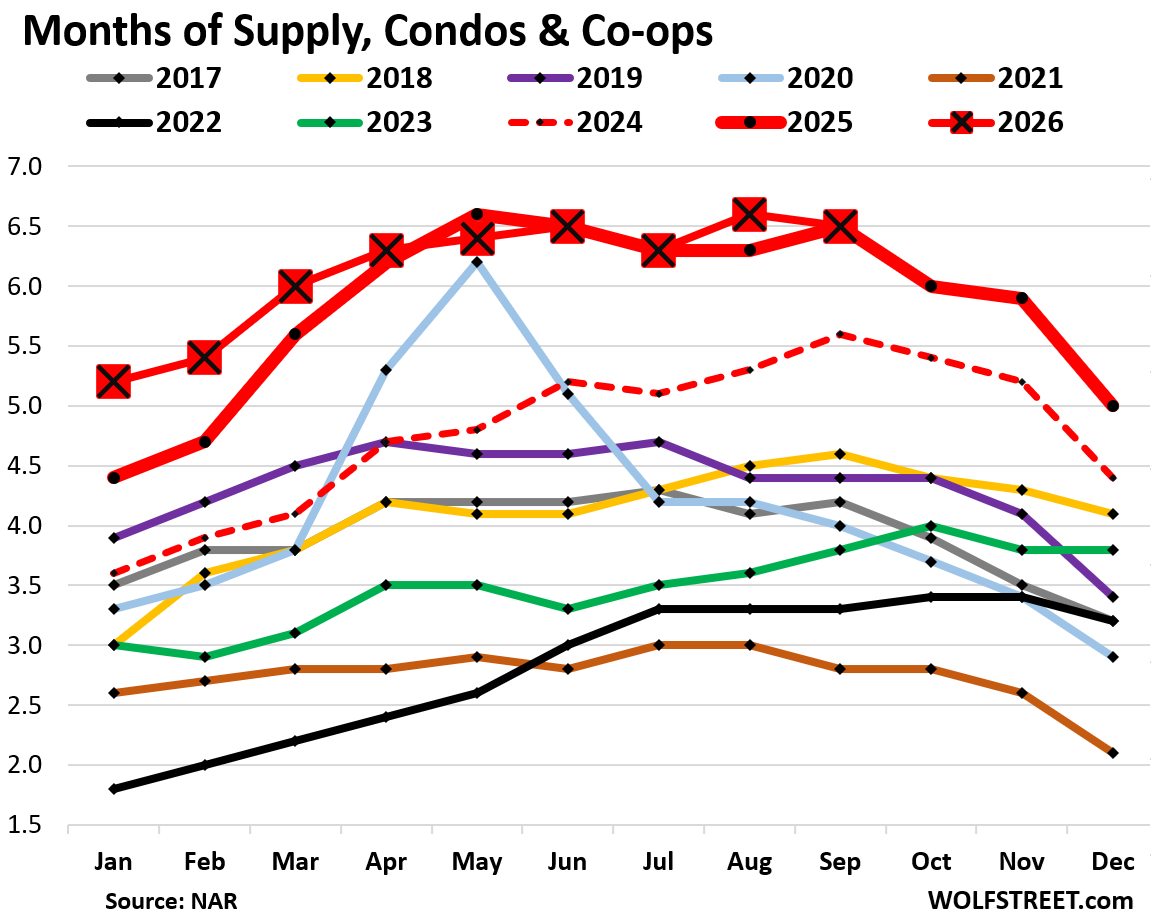
Supply of condos at 6.5 months was the same as September 2025, and both set a record high for September in the NAR’s data that for condos goes back to 2012.
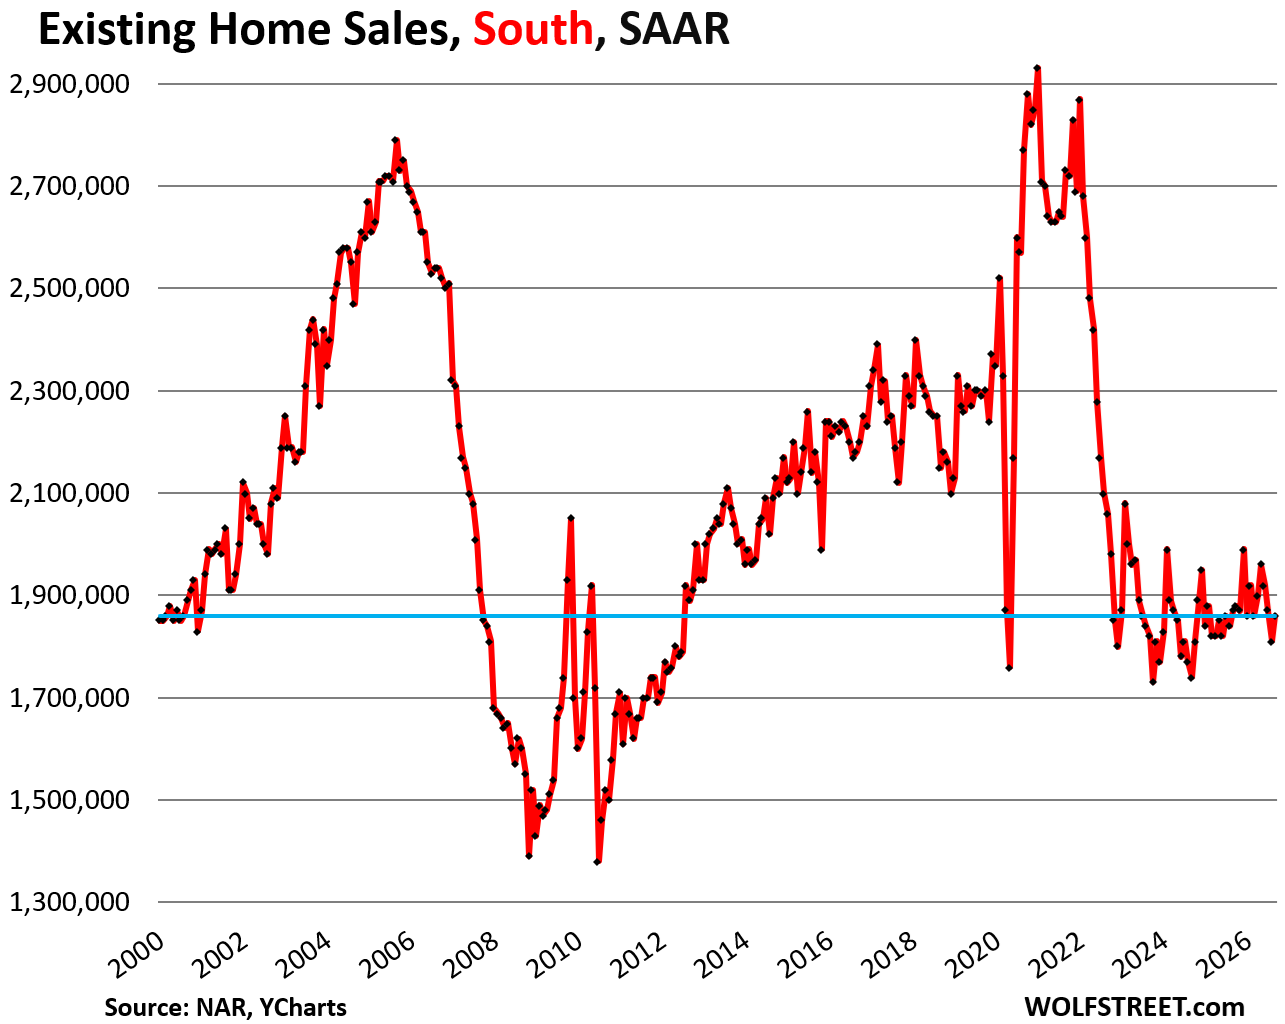
Sales by region.
In the South, the seasonally adjusted annual rate of sales ticked up in September from the downwardly revised August sales, to 1,860,000 homes, flipping to a year-over-year decline, after the year-over-year gain in August.
Compared to September in prior years:
- 2025: -0.5% (year-over-year)
- 2024: +6.9%
- 2023: +2.2%
- 2022: -9.7%
- 2019: -18.8%
- 2018: -13.5%
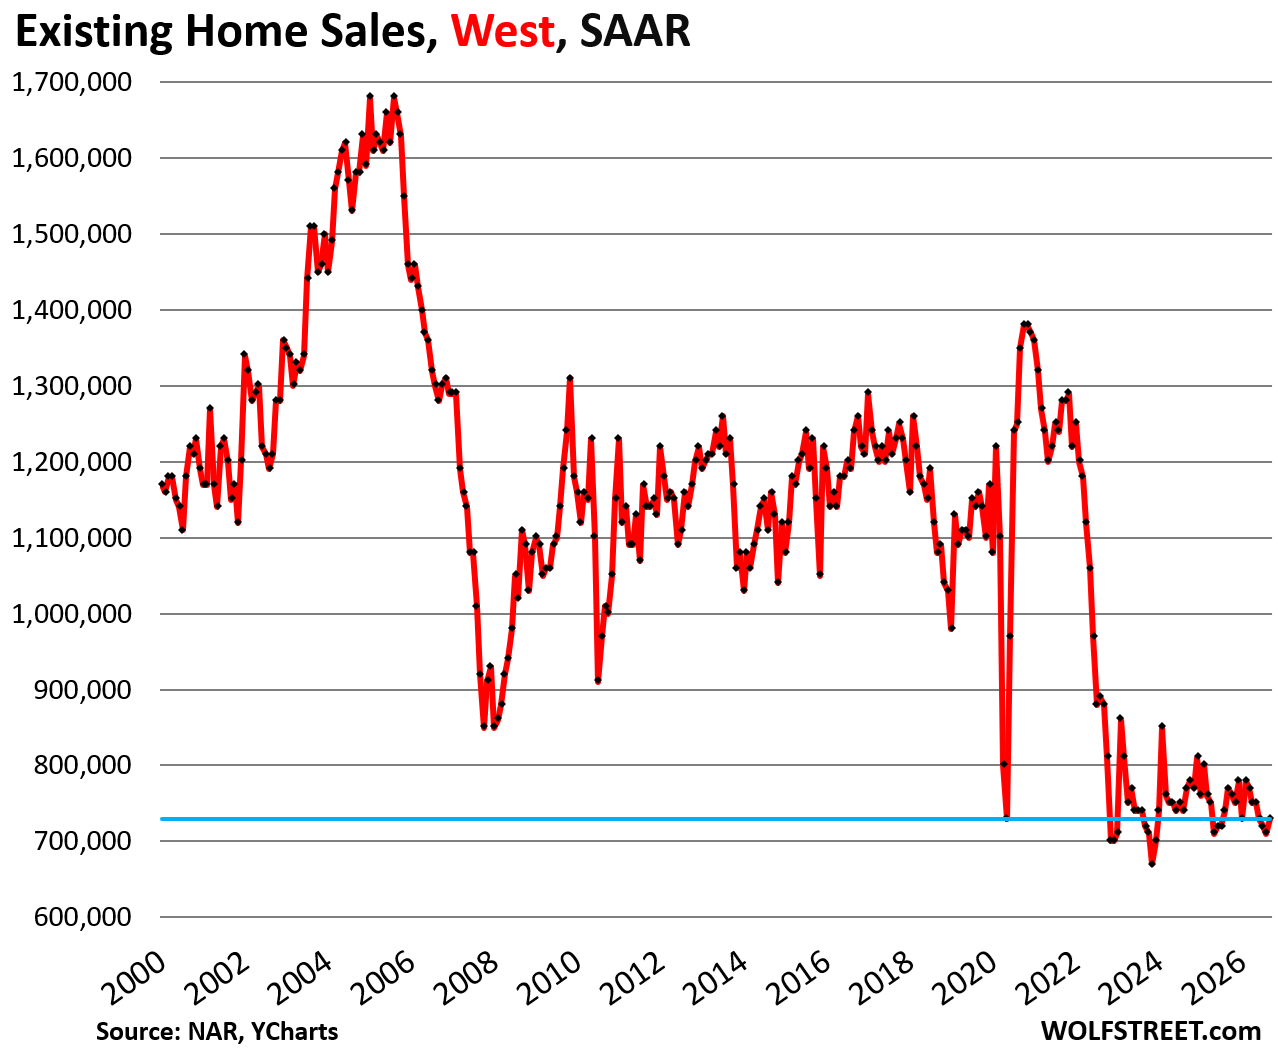
In the West, the seasonally adjusted annual rate of sales ticked up from the downwardly revised sales in August to 730,000 homes. And the year-over-year decline worsened.
Compared to September in prior years:
- 2025: -5.2% (year-over-year)
- 2024: -5.2%
- 2023: +1.4%
- 2022: -17.0%
- 2019: -37.1%
- 2018: -32.4%
In the Midwest, the seasonally adjusted annual rate of sales was 930,000 homes, same as the downwardly revised level in August. This caused the year-over-year gain in August (+2.1% before downward revision) to flip to a year over year decline in September (-2.1%).
Compared to September in prior years:
- 2025: -2.1% (year-over-year)
- 2024: +1.1%
- 2023: -2.1%
- 2022: -18.4%
- 2019: -27.9%
- 2018: -27.3%
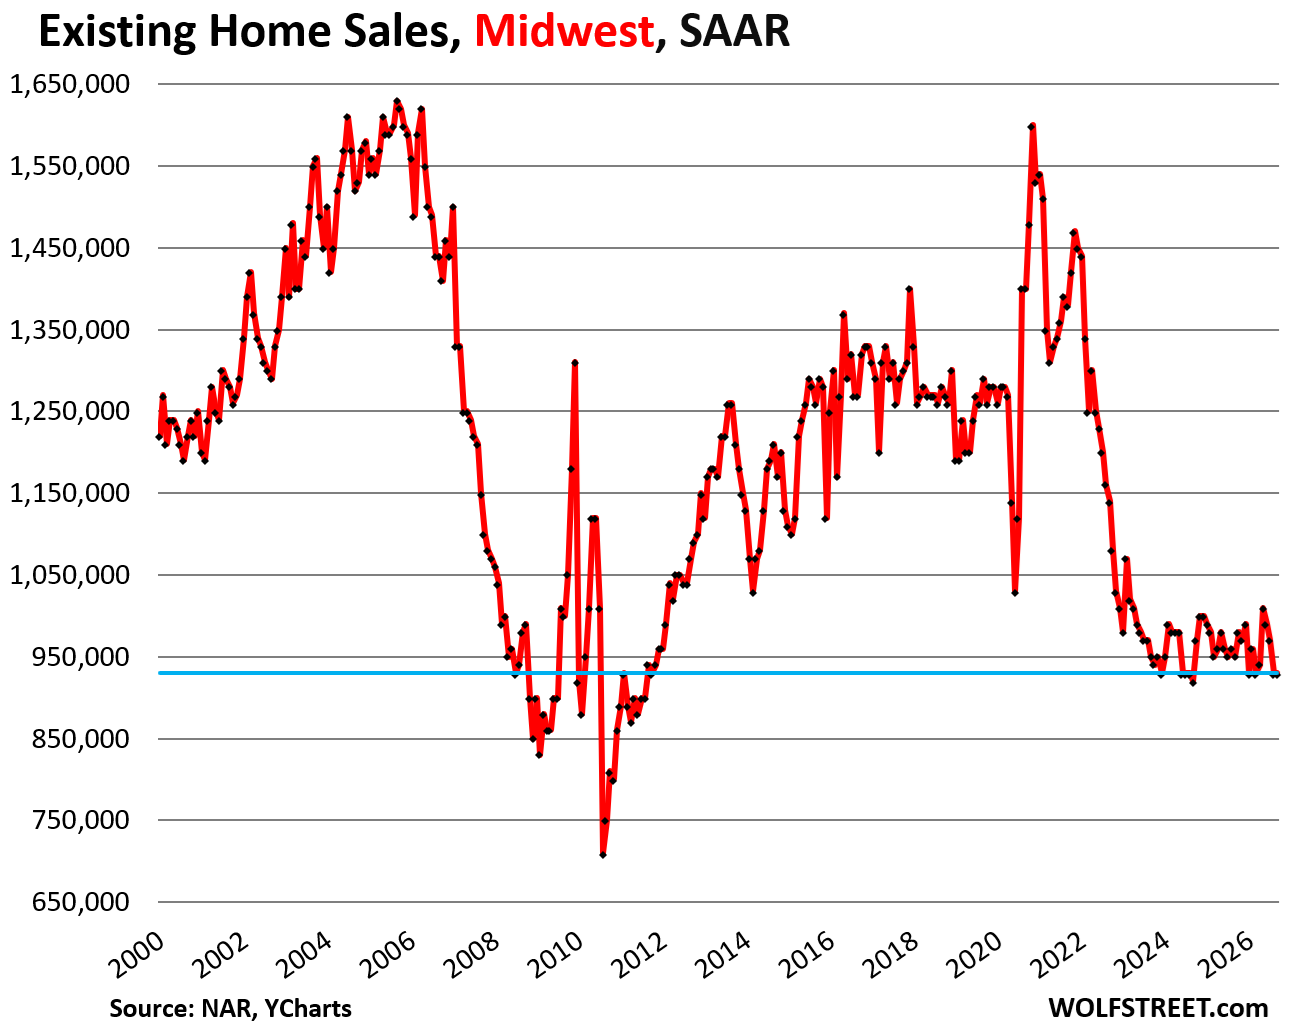
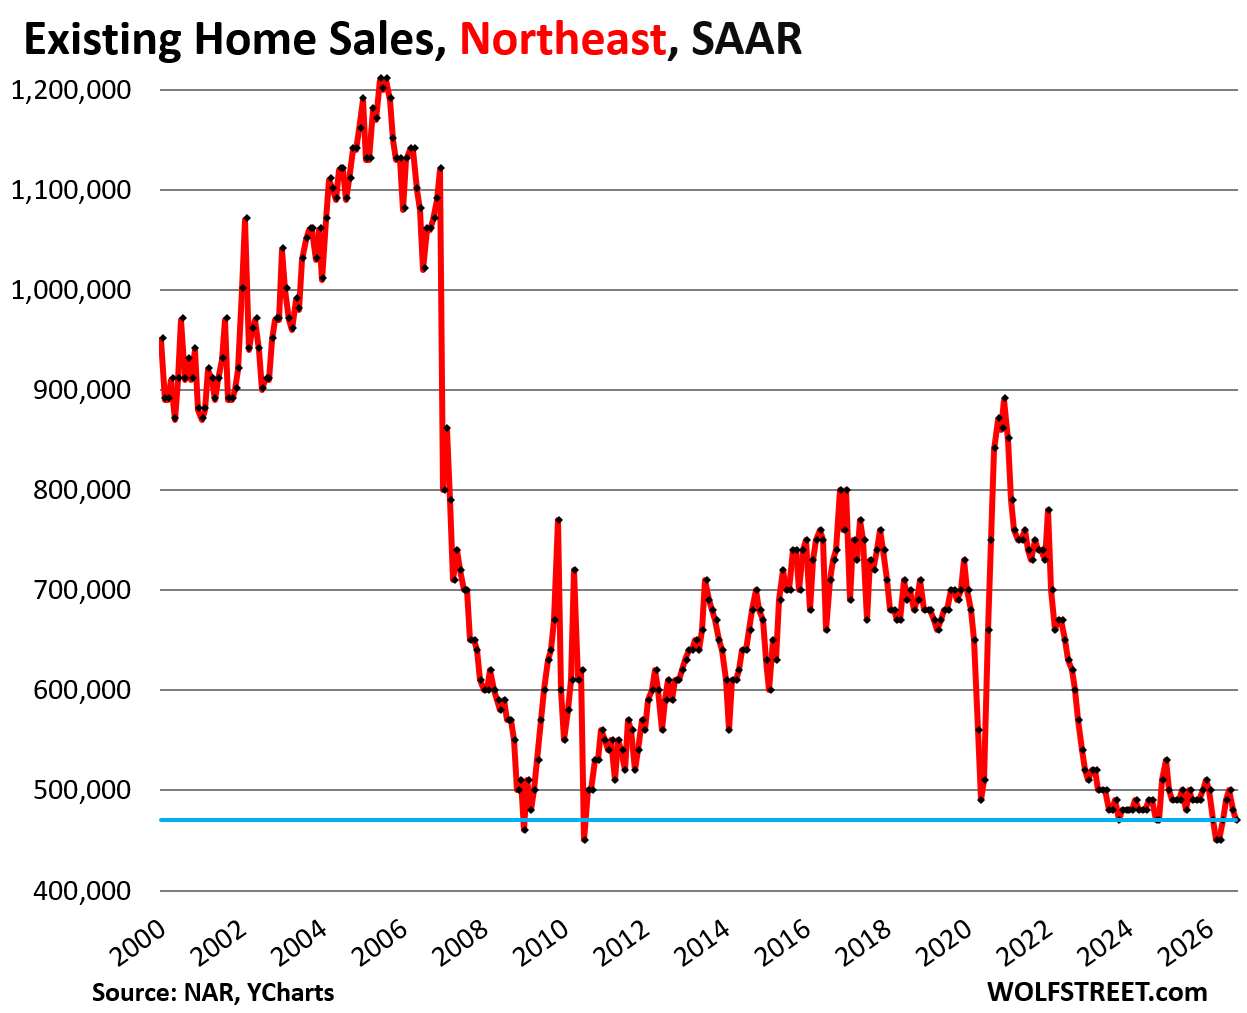
In the Northeast, the seasonally adjusted annual rate of sales fell by 2.1%, to 470,000 homes.
Compared to September in prior years:
- 2025: -4.1% (year-over-year)
- 2024: 0%
- 2023: -4.1%
- 2022: -21.7%
- 2019: -32.9%
- 2018: -30.9%
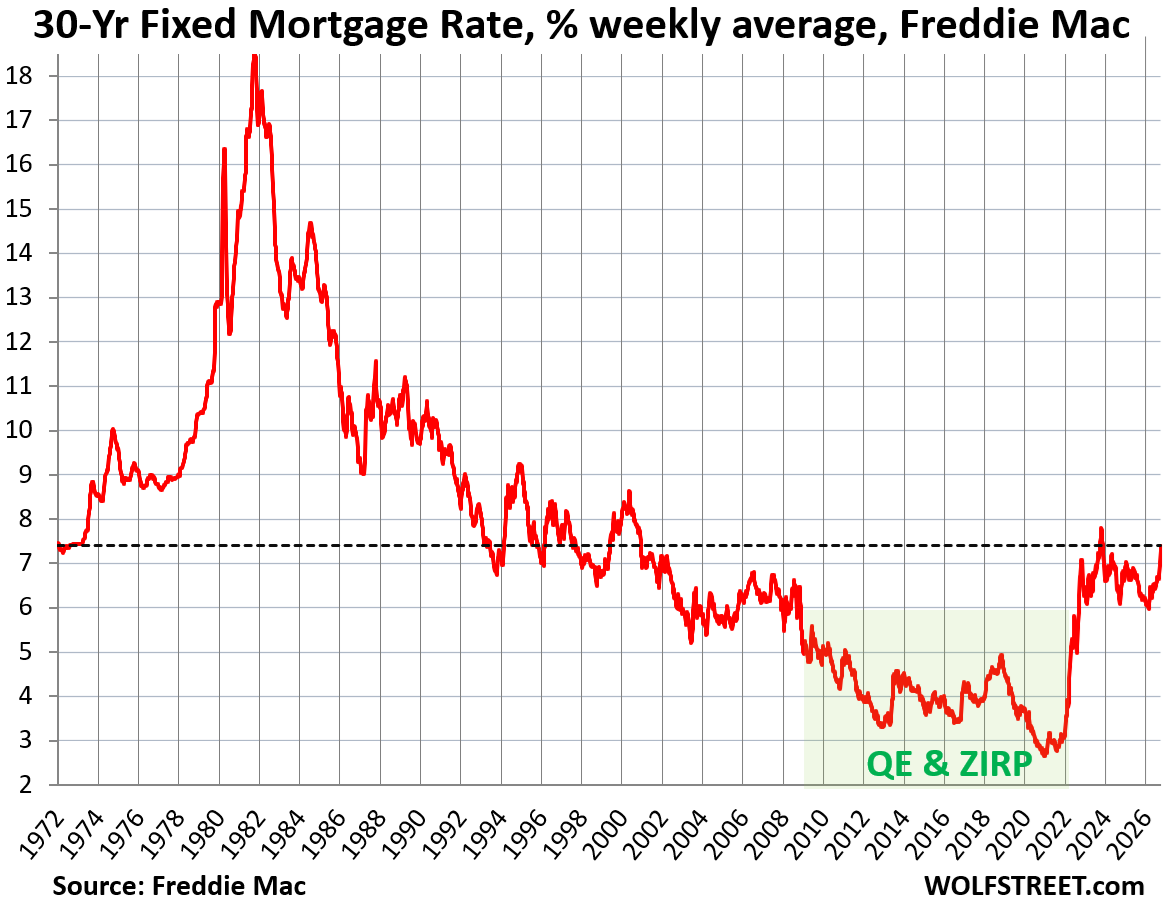
Mortgage rates were higher, but not high historically.
The average 30-year fixed mortgage rate rose to 7.40% last week, according to Freddie Mac’s weekly measure, the highest since the six-week period between early October and mid-November 2023.
In July through late September, when the deals were made that become closed sales by the end of September, mortgage rates were still between 6.4% and 7.0%. The effects of the jump in mortgage rates in October did not impact the closed sales in September, reported today. That is still to come.
In the five-decade historical context, mortgage rates are not high. But home prices are high after the price explosion between mid-2020 and mid-2022. That’s the culprit in the affordability crisis. And inflation is high.
Mortgage rates track long-term Treasury yields, but are higher, and the spread between them varies over time.
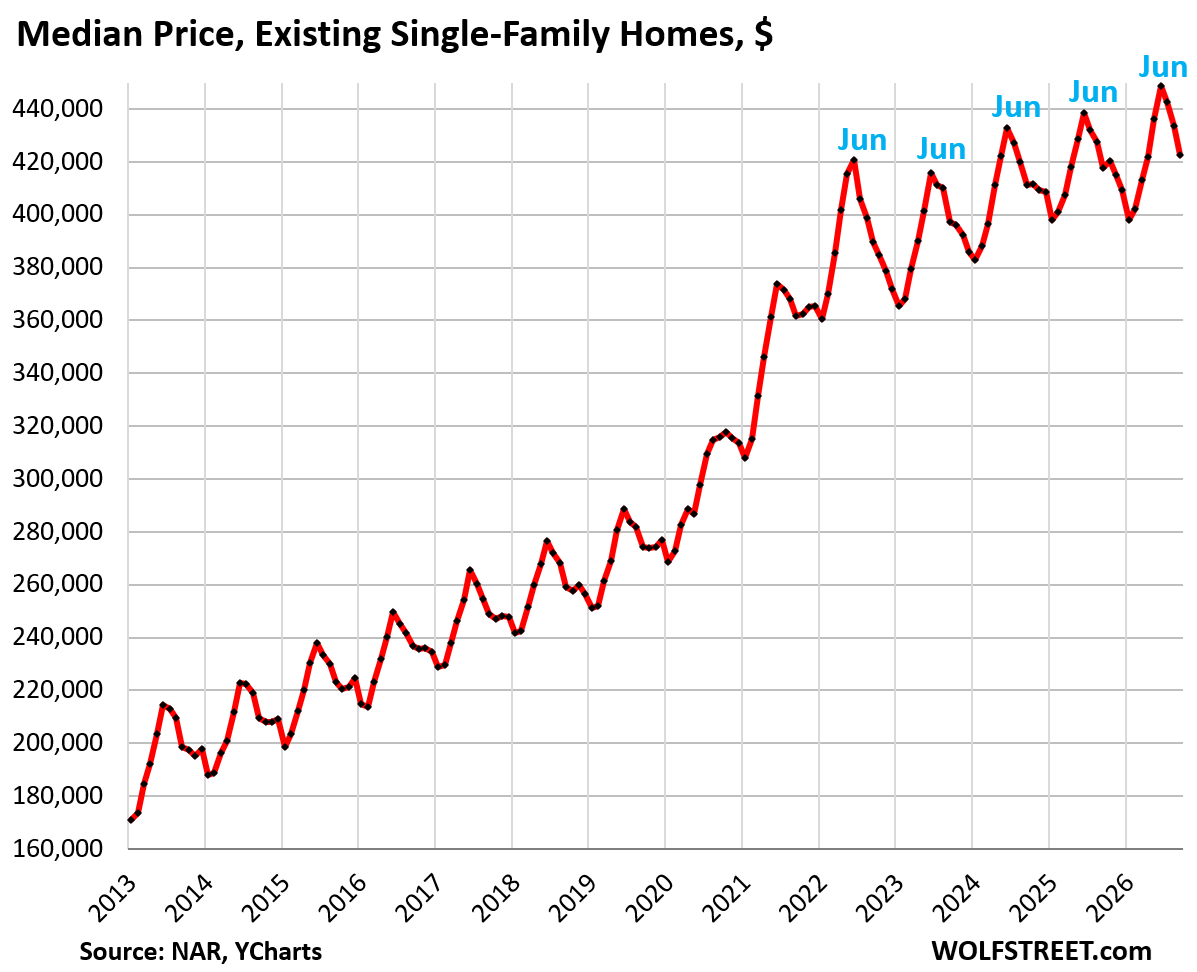
The national median price of single-family homes declined along seasonal patterns to $422,700 in September, not seasonally adjusted. Year-over-year, it was up by 1.2%.
The “affordability crisis” at the national level was caused by the 40% explosion of the national median price in the two years through mid-2022 that had come on top of already high prices.
Wage increases reduce the affordability crisis. Since September 2022, over those four years, average hourly earnings have increased substantially faster than the national median price of single-family homes, thereby easing very slowly, over many years, the affordability crisis.
Over the four years since September 2022:
- National median price of single-family homes: +8.5%
- Average hourly earnings: +16.1%
- Consumer Price Index (CPI): +12.7% (through August).
Local prices differ dramatically.
For people buying or selling a home, the national median price is irrelevant. What matters are prices in their local markets.
In some of those markets, the affordability crisis has softened by quite a bit through the combination of rising wages and sharply falling home prices, for example:
Prices of single-family homes in the cities of:
- Austin, TX: -26%
- Oakland, CA: -23%
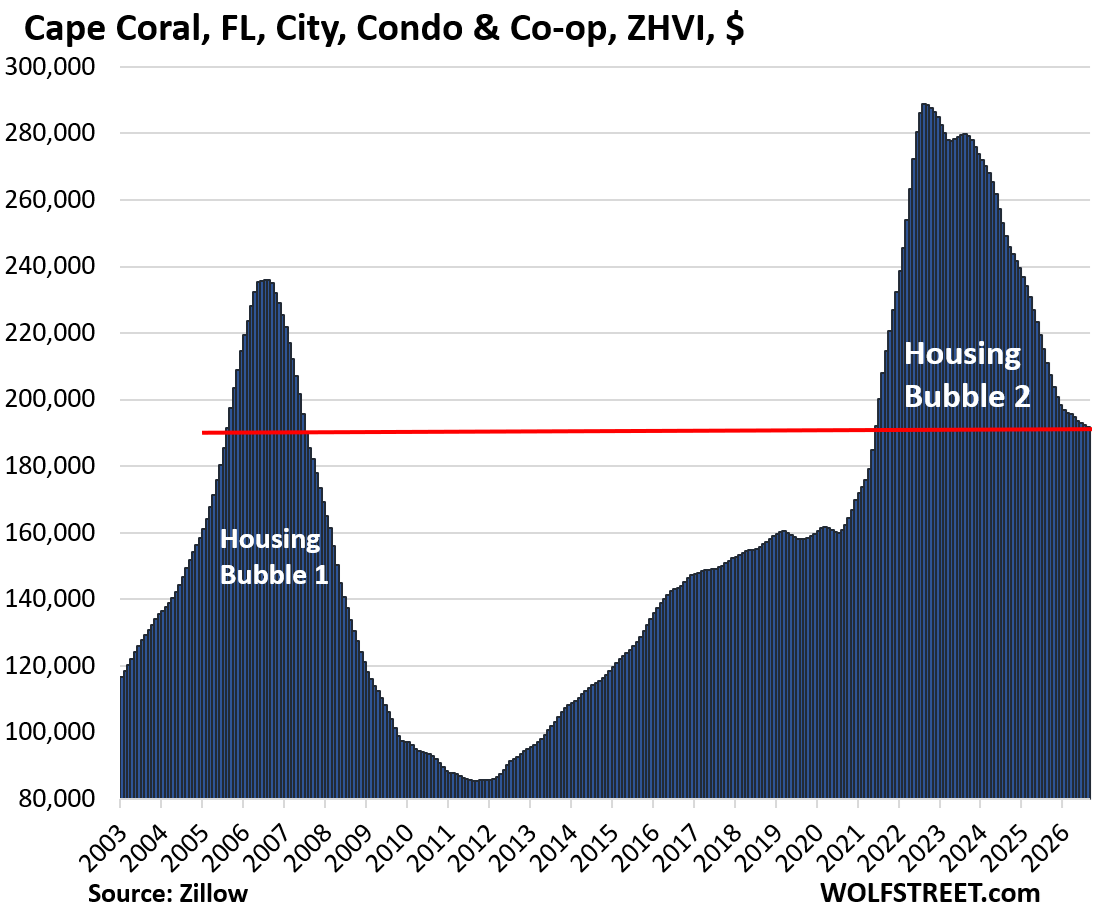
- Cape Coral, FL: -22%
- New Orleans, LA: -20%
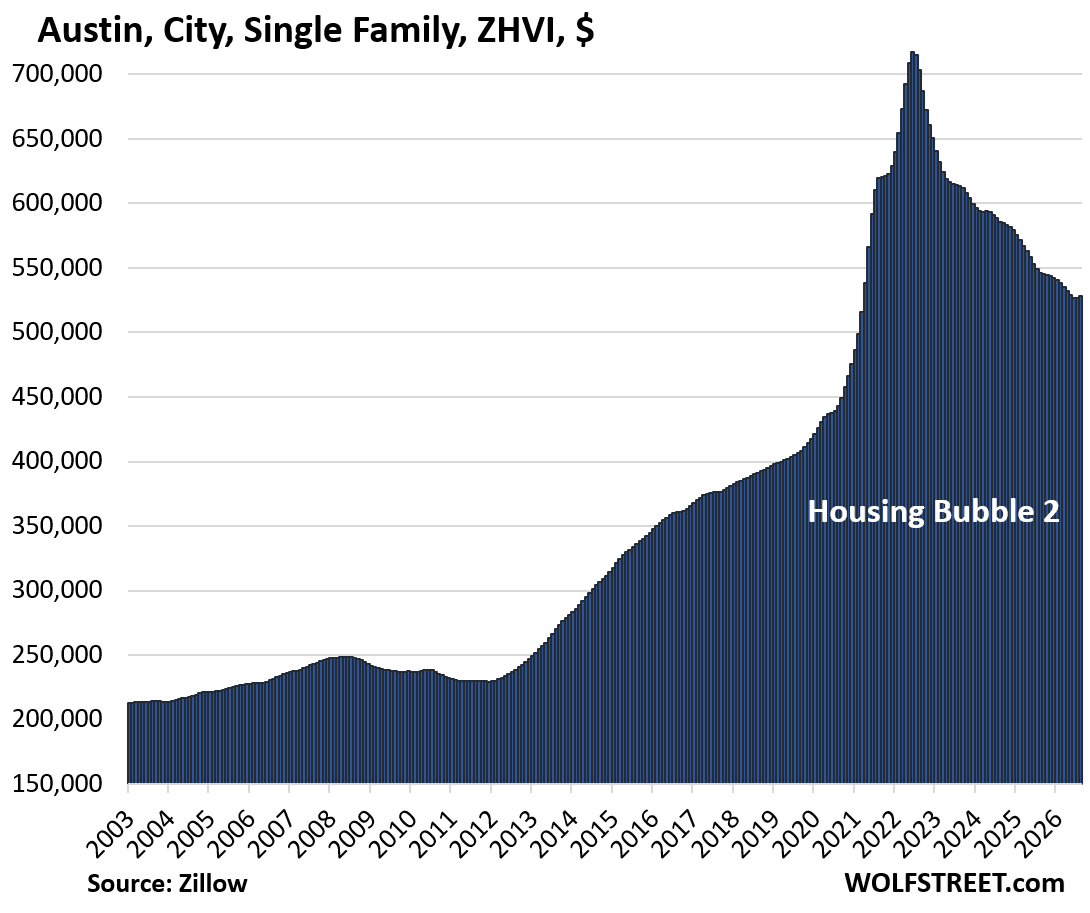
But in some other cities, prices of single-family homes have continued to rise to new highs and worsened the affordability crisis.
The biggest cities with new highs and the biggest year-over-year gains:
- Toledo: +6.0%
- Chicago: +5.6%
- Rochester: +4.6%
- New York City: +4.4%.
The national median price of condos and co-ops declined along seasonal lines to $363,000 in September. Year-over-year, it was up by 1.2%.
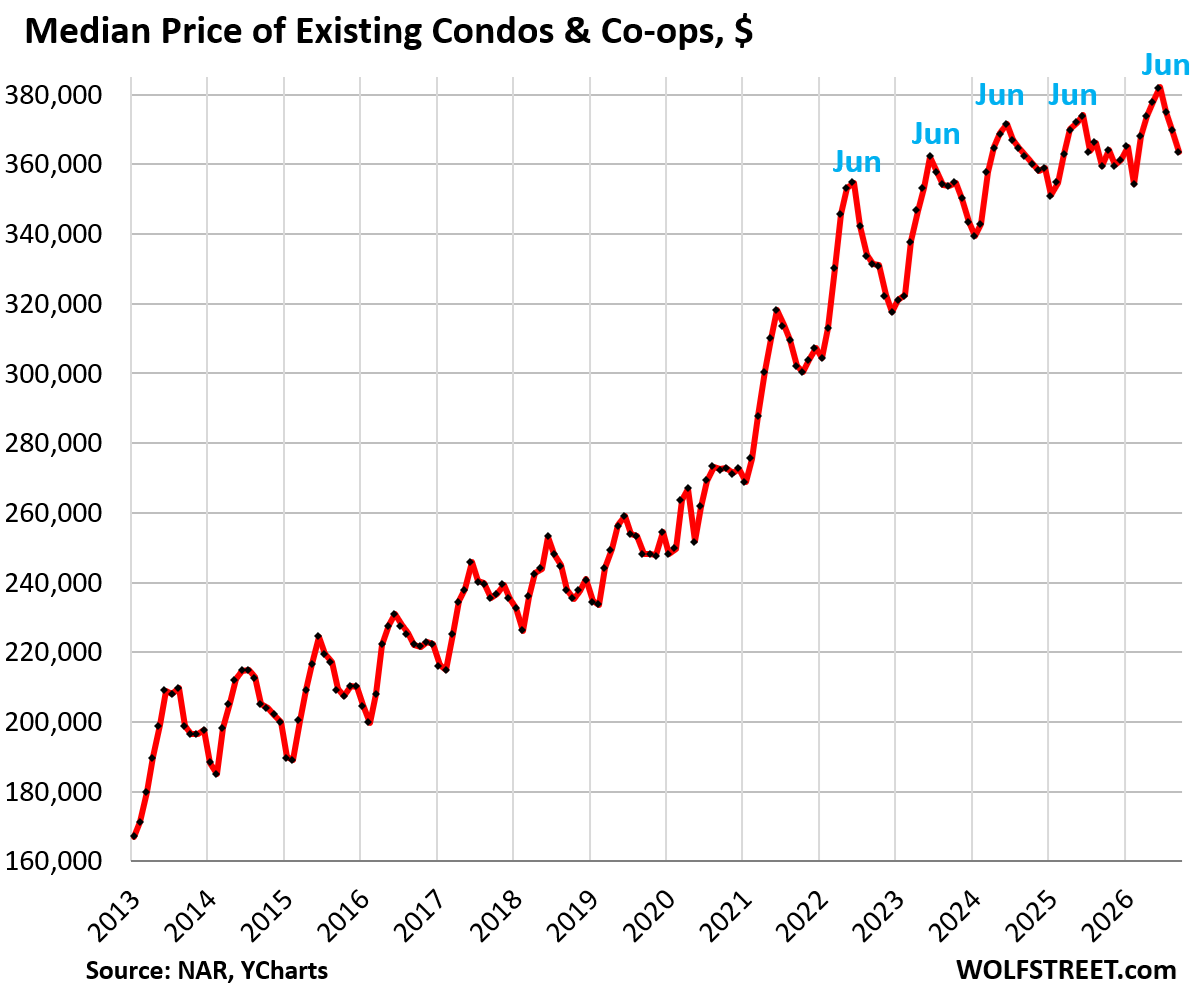
But condo prices have plunged in many cities, and the affordability crisis has softened substantially in those cities. In some of those cities, condo prices have fallen below their highs in 2006 (see our report: Oh Dear, Condo Prices Dropped by 15% to 34% in 34 Bigger Markets).
- Cape Coral, FL: -34%
- Oakland, CA: -32%
- Petersburg, Fl: -30%
- Austin, TX: -28%
- Fort Myers, FL: -27%
- Sarasota County, FL: -24%
- Garland, TX: -22%
- Tampa, FL: -22%.
The national median condo price is irrelevant for condo buyers and sellers anywhere.
In case you missed it: Home Sellers Grapple with Reality: Listing Prices Drop in Florida, California, Texas, and Suddenly even in New York
Enjoy reading WOLF STREET and want to support it? You can donate. I appreciate it immensely. Click on the mug to find out how:

I am looking but with flu pricing still on strike.
The affordability crisis will slowly move towards resolution, until or unless a deflationary recession happens.
If the Fed hadn’t overflated so much during the scamdemic, we would have had huge deflation, and this affordability crisis would have never happened.
What’s the mechanism by which deflation will make homes more affordable?
Lower prices. People with a moderate amount of savings will save money buying a house. It will encourage people to save which is a wise thing to do.
It’s a slide for sure. Interesting the sales graphs per each region look like mirror images of each other. What could be so universal? Leadership, economic policies, and interest rates all working their magic on this and other markets.
Thank you for these informative articles.
The median price charts are amazing examples of social phenomena that appear to follow regular laws.
The pre-covid slope and seasonal pattern generally continues post-covid, but with a change in intercept from inflation. (Slope looks like it might have declined a bit.)
Just remarkable.
My eyes are seeing something very similar.
I’m trying to visualize a linear regression of 2013-2020 and projecting it to present. Then visualizing a linear regression for 2022 to present. Following the slopes out to the future, it looks to my eye like the intercept would still be many years away. Not sure that says something useful, just interesting.
Growth from 2013-2019 was 5% per year. Extrapolation to 2026 gives $410k. It will intersect the new slope around 2029.
Thumbs up for the modeling.
2029 seems plausible as a return to a normal-ish SFH market where seller capitulation meets rising incomes, all else being equal.
“All models are wrong, but some are useful.”
That growth was with artificially low rates. If you look over a longer period I think price growth was closer to 2-3% a year. Historically single family homes were considered a terrible investment. But at 3% interest rates most things will grow. Also airbnb taking up inventory. Normal rates and more airbnb restrictions it would be a different market.
Kinda of interesting that nationally and regionally, closed sales cratered post unZIRP (that makes sense) and then hit/stayed at a floor for 3.5 years (even as mtg rates stayed unZIRP and even occasionally rose somewhat).
Any explanations for why such a closed sales floor might exist? Nationally *and* regionally? The general lack of volatility around that floor is also fairly interesting.
theyre nor doing zirp, flooding the economy with printed money, but theyre still flooding the economy with borrowed money deficit spending?
Thanks WR for this report.
Prices are still too high as if rates are 3%.
When I see this headline, I can imagine that’s what most RE agents are telling their cilents when it comes to buying and maybe mix in some form of rates will come down soon BS…
“Mortgage rates were higher, but not high historically”
and either by stupidity or by design leave out this other part…
“In the five-decade historical context, mortgage rates are not high. But home prices are high after the price explosion between mid-2020 and mid-2022. That’s the culprit in the affordability crisis. And inflation is high.”
I saw a realtor ad: Don’t wait to buy real estate. Buy today and then wait :-)
Oh yeah, it’s always a good time. I am sure if buyer is looking at beach front properties, some RE agents will tell you it’s a good time to buy some right in front of the coastline in Long Beach or Newport Beach Balboa island….might come with a small discount and free salt water in the living room for days….
Now if only prices would return to the 2021 levels.
adjusted for inflation the price drop might not be as much as people are thinking, and the $ has been devalued in more ways than just than just inflation.
Many markets are down by 30% or so from its peaks.
It’s all about affordability and homes are historically unaffordable.
They already have in some markets, and more. But they have continued to rise in others. If you want to buy or sell, it’s the local market that matters, not the national median price. See charts toward the bottom of the article. We’ve covered some of those markets in detail here. See links
I look forward to 1921 pricing. It’s coming….
The six mile stretch down from the Franklin Ave bridge across the Mississippi river on Minneapolis’ east side, and through St. Paul to where Mississippi River Blvd ends is my favorite — by far. A smooth road with a dedicated bike lane, and great views.
It’s also where some beautiful homes that represent St. Paul’s ‘old money’ are. I always keep an eye on any of these homes that go for sale.
In June, one of my favorite mid-century modern homes went on the market. 450 Mississippi River Blvd S was “aspirationally priced” at $3.25 M. Location, location, location is perfect. And the house sits on .76 acres.
A couple weeks later, the price was reduced to $2.85 M. That didn’t do the trick. Seven weeks after being listed, the price went down again; to $2.5 M. It was taken off-market briefly at the beginning of September. But it went back on at $2.5, and stayed there unsold.
Finally, at the beginning of October, the price was dropped another quarter-mill. This is one million under the initial listing. $3.25 to $2.25 M.
Well, that was the “Price Is Right.” On today’s ride, I saw a “Sold” marker on the sign, and looking online, I see that it is “Pending.”
Hell, I’ve been in my 1920 Sears Craftsman kit-built bungalow, all 1,040 sq ft, for 31 years now. But yeah, I’ll keep looking at the homes on the river with a little lust when I see a for sale sign go up.
Over $2 million to live in an ice box…..cute…..
Let’s start a conversation. I have say 500 K to invest. Where do I put the money for the next ten years? Yes, I do not wish to trade the money just invest it for ten years. My choices are gold, land, Treasury securities or stocks.
I suggest everybody will have a different answer. But It might be fun to do this, Mr. Wolf
I suggest cashier’s checks, but make sure you stay under the FDIC insured insurance limit per account type:
“Liquidity issues could theoretically arise if a bank treats large pools of long-term uncashed cashier’s checks as stable, permanent core deposits and invests those funds into illiquid, long-term assets (such as multi-year bonds). If a massive wave of old cashier’s checks is suddenly presented for payment all at once, the bank could face a short-term cash outflow scramble, though this is rare since standard cashier’s checks clear relatively quickly.”
Tounge in cheek.
Well what is your apatite for risk.
You can bet or invest. They’re not the same thing
Of those choices, I’d pick treasuries. Gold is in a massive bubble. Land is ludicrously overpriced. And the stock market bubble is so laughably grotesquely bloated that an elevator drop is likely at some point.
Can’t beat under the mattress, just don’t smoke in bed.
Ten years of 3.5% inflation turns 500K cash under the mattress into 350K cash under the mattress.
Or you could throw away 150K today on the wildest party ever and roll 350K into TIPS. You’ll end up in roughly the same place, except one way you’ll have better photos to look back on.
They have a new thread for that type of question often on bogle heads. Idk, but try to give some to charity, which admittedly can be tricky.
Andrew,have you considered hookers and blow?
What we need now is another 42 months of student loan moratorium/forbearance and another 18 months of mortgage moratorium/forbearance for Main Street borrowers. At 7.5% mortgage interest it seems to be an over supply of housing with no demand. What will be the next great crisis or pandemic coming out of Washington or Wall Street to cause the shock and awe panic. The gospel according to AI seems to have mini mutiny among the tech disciples, Elon is now building his own chip manufacturing facility in Texas. The daily grind of tech giants leaking back door agreements and deals, I see consolidation coming. Renting still seems to be the cheapest option for consumers, I see more availability everywhere in my neck of the woods.
As of Jan 4, 2027 , Fannie Mae will require 15% of annual HOA assesment income to be set aside for maintenance reserves. This will likely cause more turmoil in the condo market for some developments, starting next year. I’m looking forward to seeing the condo price charts next spring.
JeffD,
You are 100% correct. The new Fannie Mae requirement played hell with our can-do-minimum’s 2027 HOA assessment. Owners aren’t pleased … but none of us seem to be moving.
Conservatively run HOAs for high-rise condo buildings have been doing this sort of thing for eons. The building where I owned my condo had a massive sinking fund, which paid for a new central water heater (about 170 units on it); it paid to repair damage to the building when lightening knocked off a big piece of the concrete crown at the top (if crashed down on the sidewalk and didn’t kill anyone, didn’t even hit a car, luckily). We never had an assessment. Everything was paid out of the sinking fund. That’s how it should be.
The main issue with many condo boards are they are inept or downright corrupt. If you are in a well run building count yourself lucky and and or smart to have chosen well. On the other hand you gotta live somewhere and there is no perfect place. Ask yogi bear.
My impression is that one of the worst situations that one can find them selves, assuming they are normal, is having overpaid for a house just before the asking price dropped by 40 pct
Salinas California, a farm valley of 160,000 people. A good size for reference.
As of September 2026, the Salinas, CA (a 70% non-white Major US farm City) real estate market has a median of 52 to 66 days on market depending on the specific neighborhood and asset class, with a total active residential inventory hovering around 185 to 217 listings. This translates to a tight months’ supply of inventory (MSI) of approximately 1.5 to 2.5 months, cementing Salinas as a strong seller’s market where demand continues to outpace available inventory. So the moral of the story here is the same as always: tight markets are “where more people want to live there AND are also willing to pay for it”. Bad markets are: where more people want to leave that Area than move to that Area.
What was the average days on the market last summer? The summer prior? I am sure that it didn’t double…
The “days on market” on active listings is NOT how months-of-supply is calculated. Active listings are ephemeral, they come and go.
You need to take total listings and divide by actual sales in a month.
Even that does not account for the shadow inventory of homes that will come in the market if prices fall a bit further
It’s surprising with the bull run in equities that the housing market is in the dumps. I guess the let it ride seems better than selling and taking the capital gains tax hit to buy an overpriced home because equities will continue to gain 20% yoy ad infinitum.
I became aware that the plain vanilla S$P 500 index ETF was up by 118 pct over the past four years.
\
All the while I was convinced that the stock market was grossly overvalued
I reckon it’s because of the high prices and the “high” (historically normal but high by QE era standards) mortgage rates together. Buying at the current price points and with 7.5+ rates kinda sucks.
For the most part, the people who own the equities already own their house (and often more than one). An interesting data point would be to see over time how many buyers are first time buyers. Perhaps Wolf has done this in the past and I missed it.
^^^This housing is struggling with stocks at all time highs and record unemployment.
What do you think happens to housing if the AI bubble bursts? Or unemployment goes up by 1-2%?
What is amazing is the rectitude of the American populace, as this Shakespeare worthy drama unfolds. Becket comes to mind.
Home prices are mostly decided by how much borrowers in the local market can borrow.
When one buys a home through a mortgage, they are in essence making a leveraged bet on their local economy and national mortgage interest rates.
Yes and no, COVID changed this. For example, Denver housing prices got driven up by out of state highly paid remote workers. Also a giant increase in tourism and Airbnb ownership.
Now that trend is reversing, prices need to fall 20-30% to come back in line with CO outcomes. Also a lot of big companies are leaving CO for more business and tax friendly states so median local income may fall instead of rise
Wow, despite sales being in the toilet, the national median price of single-family homes continues to see-saw upwards. Years ago I posted on here that unless a recession hit, prices would see-saw flat until sales took off due to low mortgage rates. I wouldn’t have imagined it taking this long and even less that prices would continue to rise. Now I am more confident than ever to state that unless we have a recession, housing prices will continue to rise and will jump once mortgage rates drop below around 5%-5.5%.
I live in Fort Myers, FL. I have lived in Florida for 30 years and previous to that I lived and grew up in the mid-Atlantic region. I can see on the graph that back in 1972 interest rates were tracking around 7%. As a baby-boomer in his late 60s, back in 1972 I was only 14 years old and too young to grasp mortgage rates or home sales. However, in 1989 when I purchased my first house I was paying 10.5% on a 30 year loan.
I have lived in my tiny, retirement bungalow for 9.5 years. This is my 5th and final house, which I paid off a few years ago. Yes, I’m one of those horrible, baby-boomers sitting on enormous equity in their home – 100% to be exact in my case and an article I read a few days ago says that 25% of us outright own our homes.
As pointed out in this article, interest rates are returning to their historical norms of 50 years ago. The pandemic induced craziness and QE were aberrations in pricing and interest rates. Those halcyon days of nearly free money will never come again, unless we have a 2nd Great Depression, but let’s not go there.
The problem is the cost of homes and I’m not just talking about the actual price of the house. It’s the insurance on the house and property taxes. Three major hurricanes in the 9.5 years I’ve lived in Fort Myers have caused my insurance to sky rocket even though I only suffered damage to my privacy fence during al 3 hurricanes. This 69 year old, concrete block house survived. The insane valuations caused during the pandemic, punch-drunk bidding wars and stratospheric over paying for homes has left a huge impact on property taxes.
In the 9.5 years my taxes have almost tripled in value. Here in Florida, we have Amendment 3 on the ballot. If it garners 60% of the vote, it goes into effect in 2027 with a 150K homestead exemption for Floridans who have lived here at least 5 years and goes up to 250K in 2028. I am hoping it gets the 60% vote. Retirement becomes challenging when insurance and property taxes continue to greatly outpace inflation.
I am sure these same cause and effects are affecting young and first-time home owners. It’s not the house. It’s not the interest rates. It’s the total cost of ownership. Cheers.