The numbers are out for the Cost-of-Living Adjustments for Old-Age, Survivors, and Disability Insurance and Supplemental Security Income.
By Wolf Richter for WOLF STREET.
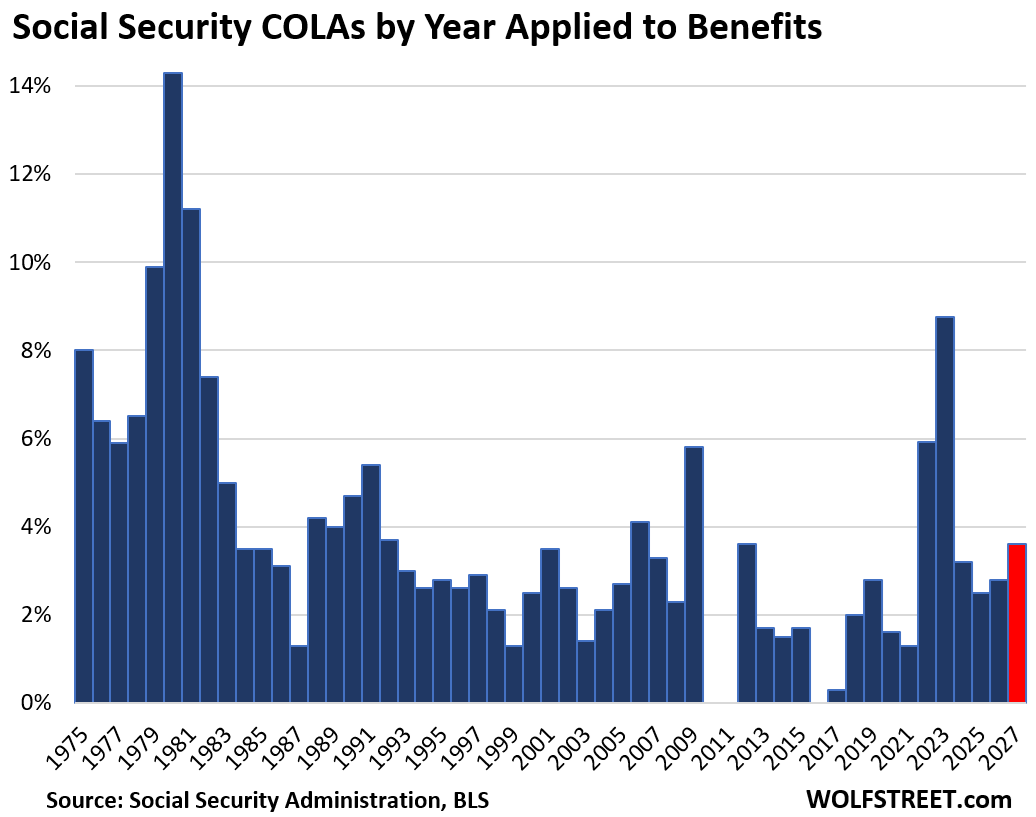
The 71.5 million Social Security beneficiaries will see their benefit increase by 3.6% in the calendar year 2027, according to the Social Security Administration, based on today’s somewhat ugly inflation data for September. It will be the largest Cost-of-Living Adjustment since 2023 (8.7%).
The new COLA will be applied to Old-Age, Survivors, and Disability Insurance (OASDI) benefits paid starting in January 2027.
The COLA is based on the average of the year-over-year increases of the Consumer Price Index for All Urban Wage Earners and Clerical Workers (CPI-W), not seasonally adjusted, for July (3.40%), August (3.52%), and September (3.93%, released today), by the Bureau of Labor Statistics.
The COLA also applies to Supplemental Security Income (SSI) payments.
Because the applied COLAs are based on inflation data for July, August, and September of the prior year, they reflect past inflation. So in years when inflation surges, the COLAs, reflecting the cooler inflation in the prior year, lag behind and beneficiaries lose purchasing power. And in years when inflation cools, the COLAs, reflecting the hotter inflation in the prior year, catch back up, and recipients regain some of that lost purchasing power.
Social Security was designed to protect people from descending into abject poverty when they retire, after having worked all their lives. It’s a safety net and old-age insurance. And it more or less does that.
But Social Security benefits are not enough to retire on comfortably unless recipients do a lot of belt-tightening because the benefits are far smaller than the beneficiary’s peak income was.
In addition, CPI-W may not fully capture the increases in actual costs of living that beneficiaries may experience. These effects are cumulative and erode the purchasing power of those benefits a little more every year. And that adds up.
To prepare for a long comfortable retirement, people need to build additional resources over the course of their working lives, with Social Security being only the bottom layer.
Obviously, if you love the work you do and if you can keep doing it, the best retirement may be no retirement for as long as possible. It keeps the brain challenged and the body active. Our politicians have figured this out; they’re working into their 80s, or longer, and they’re having a blast, whether we like it or not. Even a part-time gig helps, and it can be a great way to remain engaged and active.
My detailed CPI inflation report will be posted in a little while.
Enjoy reading WOLF STREET and want to support it? You can donate. I appreciate it immensely. Click on the mug to find out how:

SS goes up and Medicare follows. The net you gain from SS minus the raise in Medicare won’t be 3.6%.
Same as with other costs, such as rent, HOA fees, homeowner’s insurance, food, etc. That’s inflation, including Medicare Part B, and the COLA is there to help cover inflation. The COLA is NOT additional retiree profit or a performance raise or bonus or whatever. You seem to confuse the purpose of the COLA. It’s supposed to help cover price increases, including from Medicare.
COLA changed to reflect broke govt 1st
today nearly 70% retirees live below poverty line
my mother at 90 gets $1,100 month
her RENT and utilities are $1,000
being widow she pay little in taxes(property/tags-yah she drives)
her pension after 17 years is $400(basically what she LIVES ON-food/insurance/upkeep)
she REFUSES govt assistance
SSI was meant to be RETIREMENT SUPPLEMENT
then some smart accountant in 1979 found IRS rule 401(k) – another supplement now main retirement
pensions only are for executives who get 250% inflation adjusted raises annually
Yes, RTGDFA
Why is she refusing government assistance?
And that 70% stat seems wildly off.
For Gods sake JoeDidee Help your mother.
According to the Census Bureau around 10% of those above the age of 65 live below the official poverty level. Where do you get 70%? https://www.census.gov/library/publications/2026/demo/p60-290.html
He get’s it just fine. His net benefit explains everything
You don’t get it either. Medicare is health insurance. There is no “net benefit.” Premiums are deducted from the SS payment like your contribution to employer health insurance premiums is deducted from your paycheck. You people think that COLAs are a performance bonus that you can put into a savings account, LOL. No, it’s supposed to help you deal with price increases due to inflation, including that of health insurance premiums (Medicare).
People who delay SS benefits till they’re 70, but are on Medicare from 65 on, they get billed for Medicare premiums every month, and they have to PAY it every month, just like other health insurance premiums, such as the premiums for a Medicare Advantage plan. These are just health insurance premiums that people have to pay, and the premiums go up every year, which is part of inflation.
And the annual co-pay goes up every year. I think mine was about 8k this year.
Reach age 73 and your required minimum distribution will throw you into a higher tax bracket. Can’t win.
It should be pointed out that social security is one of the most successful US government programs of all time.
Millions of US citizens benefit each and every hour.
It should also be pointed out that it is a giant ponzi scheme that will not self sustain long term without massive tax increases, benefit cuts, or a massive wave of immigration.
AI doesn’t think so!
“No, Social Security is not a Ponzi scheme. While critics and some politicians have used the term as a critical comparison, legally and structurally it is a government-run social insurance program.
Why People Compare It to a Ponzi Scheme
• Pay-as-you-go funding: Like a Ponzi scheme, the money collected from current workers is used to pay current beneficiaries rather than sitting in an individual investment account.
• Demographic pressure: Critics (such as some economists or political figures) argue that the system relies on a continuous stream of new workers to support retirees, which faces strain as the worker-to-retiree ratio shrinks.
Why It Is Not a Ponzi Scheme
• Legality and transparency: A Ponzi scheme is an illegal, fraudulent criminal enterprise built on deception and fake investment returns. Social Security is a public, legally mandated social insurance program established by the U.S. government.
• No deception or fraud: The Social Security Administration openly publishes its financial data, rules, and annual Social Security Trustees Report detailing how the system is funded and projected.
• Backed by government authority: Unlike a private fraud that inevitably collapses when new investors run out, Social Security is backed by the federal government’s taxing power and statutory authority to adjust revenue or benefit structures.
• True challenges: While Social Security faces genuine long-term financial shortfalls and trust fund sustainability issues that require congressional action, these are structural and demographic funding problems—not financial fraud
Yep HappyOne Tax Increases make sense… about time we started taxing corporations/people to Make America Better Again!
40 Trillion in the hole and counting! Can’t wait to see the deficit number for this year!
Time to buy bonds.
10-Yr Bond
5.31
+0.09
Yeah, that CPI report was pretty rough. CPI-W, which the COLA is based on, rose by almost 4% year-over-year in September.
TIPS
5 year opens tomorrow
5.19
-0.03
(-0.52%)
At close: 1:59:54 PM CDT
I guess lots of other people had the same idea.
I am having trouble reconciling the obvious risk of owning wilting American Federal Reserve notes while the so called market interest rate seems oblivious to the facts.
The fading safe haven that America has been portraying since WW2 has become substantially more risky, with hardly 10 basis points increase in the so called market interest rate.
Maybe I’m old and misremember the extent of corruption back then
Today seems like a whole new level.
I don’t want to tell my Mom, she will think this is an “ALL CLEAR” signal to go shopping.
Just in time. Forced retirement December.
Bummer man
Our politicians are “working” into their 80’s is a laughable comment. Entrenched lifelong politicians who have cozy benefits, including inside information and dark money don’t want to leave?
Give me a break!
“Our politicians have figured this out; they’re working into their 80s, or longer, and they’re having a blast, whether we like it or not.” For some reason, these politicians end up being multi, multi-millionaires by the time they leave office. Obviously, I selected the wrong career path!
These politicians are not leaving because their seniority and positions on powerful committees is far too valuable for their respective parties. Looking at Mitch McConnell, it’s obvious retirement is in his best interest.
Even assuming the best of these people, that they are in it for the love of their country and trying to make the world a better place, there’s a bigger reason they stay in office: lack of talent development. Both parties, moreso the Dems, have made the same blunder as corporate America – not developing and growing their future leaders. There is a dearth of younger talent available to compete for these roles, and the ones that have survived the political machine are largely special interest or extremes of either edge of the political spectrum. This is in large part due to the failures of our two party system.
For what it’s worth, I believe a portion of politicians are still in it for these noble reasons. Not as many as I once believed, but there are still some there. I hope that they can be successful and help steer the ship in the right direction. Call me naive if you want, but I believe unchecked cynicism is just a coping mechanism to avoid disappointment or projecting negativity outward.
Another reason is that good people who might want to serve to better society are afraid of the attacks from the social media crazies, political groups and even top level government leaders. My wife convinced me not to run by pointing out some of the attacks that people in government positions in our town and county endure. It’s a shame that this is the playbook.
We are stuck with the people that created the current mess in charge of cleaning it up.
The only way too get rid of them is in the open primary system. One vote carries a whole lot more weight
The Fed failed to keep inflation under control: Russel 2000 is in correction over 10% off from highs. The semiconductor index $sox is almost in bear market territory over 18% off highs, Dow 30 is off over 5%, the spy are only 1% off from the highs. I told my friends and posted here to sell limit spy at 573.65 telling my friends and family you will sell within 1% of the highs and a 4% t bill hideout is great place to visit. Equities are selling but when $tnx closes above 5.3% for 3 days the crash will happen, buyers came in at 5.3%, the house knows the algorithm code. Scott Bessent called this knowledge asymmetric. It’s just a matter of time! If you think I am delusional I get it, listen no one ever cried posting profits it’s good to pay taxes the government needs the money, a 2 % stop loss is wise on the spy from all time high!
“The Fed failed to keep inflation under control”
Is there another way besides inflation to diminish the relative size of the debt? The ugly secret though is that debt management through inflation only works if interest rates dont force you to pay the full price of inflation.
Are Treasury and FED really going to work at cross purposes ?
Is the type of inflation we are experiencing really monetary inflation or is it due to supply disruptions in critical commodities…or both ?
What if we hadnt initiated this war 8 months ago and oil/LNG were plentiful and at $60 with transport costs at the normal $1 dollar per barrel rather than $20 or $30 ?
Will raising interest rates change that ? Perhaps yes as rates and a wobbly bond market may put pressure on the administration to end the war…. if it is able to.
Excellent summary of the financial dilemma facing us as the end of the unsustainable, monetarist sugar high fades
in a collapse of the debt bubble
as usual
Of course, my opinion has been used as a weather vane to do the exact opposite from what I predict which would have increased tour wealth by 120 % over the past four years.
Jeremy Seigal was right.
Thanks for your thoughts! :)
Just here for the inevitable social security doom posts.
Keeping brain challenged and politician in same sentence. Lol.
Heckuva job, Weimar Boy Powell.
Wolf, anyone with a functioning brain knows that the 3.6% increase they will “give” you is less than the increase in the cost of living per year. Do we really think the total cost of living increased only 3.6% last year? Wolf’s clever term of hocus-pocus comes to mind. You think you’re ‘getting,’ or maybe breaking even. The reality is different.
Ours was probably less than that as a percent of our total household expenditures. Some big expenses didn’t increase at all. A few big expenses got cheaper (auto insurance and broadband for example; I cut broadband by 60% by switching suppliers). And some things got more expensive. We stopped buying beef a couple of years ago because it had turned into an obnoxious racket. Let the meatpacker oligopoly eat their production. That was deflationary for us. We drive a hybrid that gets 40-50 miles per gallon, and I walk everywhere I go (great exercise), so gasoline is only a tiny part of our expenses…
If you just sit on your butt and keep buying all your food at a rip-off store like Safeway or Albertsons, and you don’t pay attention to what you buy, and you don’t try to switch suppliers and products and buy online to cut your costs, and if don’t fight inflation at every twist and turn, well, then, that is your own problem.
Inflation is not measured by price tags (“asking prices” in real estate), but by what people actually buy and pay for, just like home prices are not measured by asking prices, but by transaction prices.
My wife and I tightened our belts similarly, and have spent less each of the last 4 years, but eventually there is less and less to tighten, but we’re still enjoying life. We’re lucky because many others have already reached “eventually”.
My wife just gripes about the prices but doesn’t want to bother dealing with them. I absolutely HATE it when I get ripped off, and I act. We could easily afford to pay those prices, we both work and have income, plus investment income, plus SS now for me (I delayed to the maximum), but I just HATE getting ripped off, and I feel like it’s part of my duty as a citizen to crack down on price increases and inflation.
true true true. As a person raised working class (barely) in the 80s. I still shop around even though i could afford not too. Many people that i see don’t bother. I really don’t understand it. An example and one of my pet peeves is ice cream shops a scoop is $5 I buy a whole container on sale for $5 and scoop it when i want it watching Netflix. But i digress. Unfortunately many of the expenses that are going up the most insurance being one and health care being another are requirements and cannot be avoided. Not sure how to bake this into the inflation rate. I can choose not to go out for dinner or make a coffee at home….
Wolf said in all “Yeah, that CPI report was pretty rough”. While everyone is still fixated on Powell and his lame duck tactics for the past 6+ months of his final term as Chairman (which I don’t disagree with), I’m going to focus my attention on Warsh now and provide the following analogy.
My father-in-law passed away this summer under the care of Hospice. No issues with Hospice as this organization did their job very well. However, one nurse made an very observant and correct observation with how they were treating him for pain. That is, the majority of the nurses were left caught “chasing” his pain with medication that was behind the curve (i.e., too little, too late). As she correctly pointed out, and given his condition, they needed to get ahead of the pain to manage what was left of his life.
My point is, Warsh needs to start thinking about getting ahead of the pain with interest rate, QT, etc. management. A quarter point rise (too little, too late), after everyone already knows inflation is a significant problem, isn’t going to do anything. Warsh needs to put on his Volcker hat and turn far more aggressive with the Fed’s policies. Is this going to be painful, yep as the stock market is going to get hammered, credit defaults will increase, and it could push the country into a recession. In addition, Warsh could use some help on the fiscal front to reduce the deficit (cut costs and increase taxes).
The message from the bond market is loud and clear. Monetary and fiscal policy need to change, and now, to help safe the patient. If not, the patient (i.e., the US economy as well as the world economy) is going to suffer which BTW is not just a US issue but a problem for the world now.
I understand that rate increases before an election are rare so I’m not holding my breath for anything to happen soon. However, Warsh needs to take a more proactive approach and begin to take inflation seriously as hoping, praying, and dreaming for inflation to decrease does not represent a plan or strategy, but is often fatal. If he needs a playbook, look to Volcker as nobody wants to experience the mess of 1970’s again as taking some real pain now is worth avoiding losing a decade.
I’m 73 and I like my job in biomedical research so that I have no intention of retiring anytime soon. My continued IRS salary deductions are helping prop up SS and Medicare. We need more workers, and not retirees, to save the system.
❤️👍
What to do with this windfall? Stocks, bonds or there is always under the mattress.
OK, you should do an analysis of how much prescription and Medicare costs will go up in 2027 compared to the cost of living increase.
Example my SSN increase will be $72.00 but prescription drug plan with Humana is going from $9.90 this year to $26.30 next year and we have not received our Medicare increases for next year yet. If past is prologue, these two increases will eat up the “cost of living” increase as they have in years past.
That is EXACTLY what a COLA is supposed to do, which is help you pay for higher costs. Do you think a COLA is a bonus or extra profit for retirees to put into the bank and save?
I believe what John P is saying is that
the SS COLA doesn’t come close to covering his personal inflation costs.
Even if you substitute beef for chicken,
and ditch the car, most retirees standard of living is declining.
As a younger retiree myself ,who is
having to assist his extremely elderly
parents, some costs can’t be cut and
will likely rise faster than CPI. Que sera.
So READ THE ARTICLE. What does it say? It repeats what everyone has known forever, but what lots of people have ignored all their lives, and now they gripe about it. Since no one here seems to bother to read anything and just spout off stuff, I quote my own article above verbatim here in the comments, maybe people will read it:
“Social Security was designed to protect people from descending into abject poverty when they retire, after having worked all their lives. It’s a safety net and old-age insurance. And it more or less does that.
“But Social Security benefits are not enough to retire on comfortably unless recipients do a lot of belt-tightening because the benefits are far smaller than the beneficiary’s peak income was.
“In addition, CPI-W may not fully capture the increases in actual costs of living that beneficiaries may experience. These effects are cumulative and erode the purchasing power of those benefits a little more every year. And that adds up.
“To prepare for a long comfortable retirement, people need to build additional resources over the course of their working lives, with Social Security being only the bottom layer.
“Obviously, if you love the work you do and if you can keep doing it, the best retirement may be no retirement for as long as possible. It keeps the brain challenged and the body active. Our politicians have figured this out; they’re working into their 80s, or longer, and they’re having a blast, whether we like it or not. Even a part-time gig helps, and it can be a great way to remain engaged and active.”
Chinese proverb: “He who lives upon hope will die fasting”. If you think the government gives two $hits about you, you’re in sad shape. I was lucky, I guess, self-employed since I was 30, started a SEP IRA and converted it to self-directed IRA and invested heavily in RE, and sold my business in 2007. I turned 73 this year and will now be forced to take my RMD. I don’t need the money, have zero debt and good cash flow from investments. I knew early on that if I wanted to retire in relative style and comfort, it was up to me and not some slimy, self-serving politician. Do I pay more for my Medicare, yeah, but that’s OK, the alternative is not acceptable to me. For some it is too late to make up ground, but our experiences, good or bad, should be pontificated to younger generations who will inevitably be faced with the same dilemma.