In New York, until recently a beacon of strength, the bottom fell out over the summer.
By Wolf Richter for WOLF STREET.
Listing prices are would-be-nice-to-get asking prices that sellers put on their wish-list but might not get. When sellers cut the price, the new price becomes the listing price. When sellers pull the home off the market because it didn’t sell, that price vanishes from the listing prices. When they put it back on the market at a lower price, that new price becomes the listing price. So listing prices show what sellers are struggling with. Those listing prices have been sinking in Florida, Texas, and California for the past few years. Transaction prices have also fallen or plunged in many markets in these states. But listing prices are now suddenly sinking in New York, where transaction prices had held up.
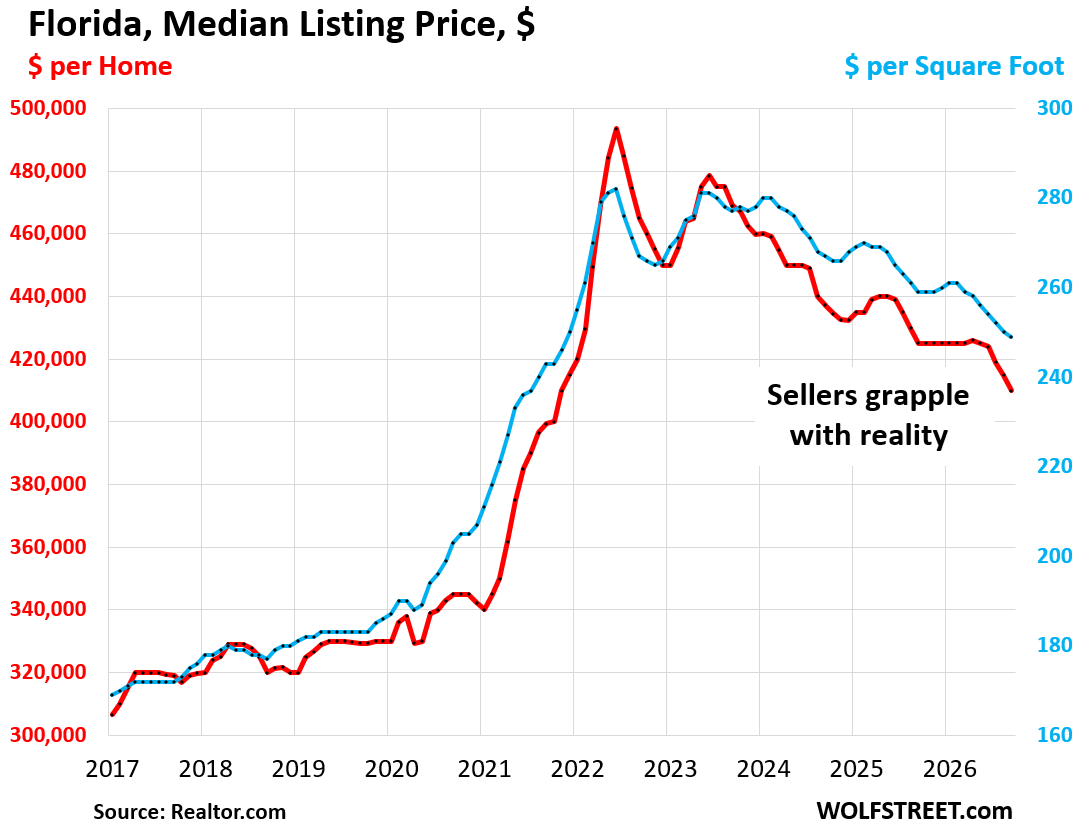
In Florida, the statewide median listing price in September has dropped by 13% from the peak for September in 2022, and by 3.5% year-over-year, to $409,950, the lowest since November 2021 (red in the chart).
On a square-foot basis, the median listing price has dropped by 7% from the peak for September in 2022, and by 3.8% year-over-year, to $249 per square foot, the lowest since December 2021, according to data by Realtor.com (blue).
The downtrend in listing prices in Florida has shown up in actual transaction prices, pushing a number of larger markets in Florida onto the WOLF STREET lists of the biggest decliners of transaction prices. Some markets got hit hard, and others just barely; condos got hit harder than single-family homes.
Actual transaction prices of single-family homes in many markets in Florida have dropped sharply from the peaks in 2022 or 2024, including in: Lee County (Cape Coral, Fort Myers) -18%, Sarasota County -17%, Collier County (Naples) -12%, St. Petersburg -10%, Tampa -6%, Jacksonville & Orlando -5%.
Transaction prices of condos in many markets in Florida have plunged from their peaks in prior years, including in Cape Coral -34%, St. Petersburg -30%, Fort Myers -27%, Sarasota County -24%, Tampa -22%, Jacksonville -21%, Orlando -18%, etc. – and in four of them, transaction prices have plunged below their 2006 Housing Bubble peaks.
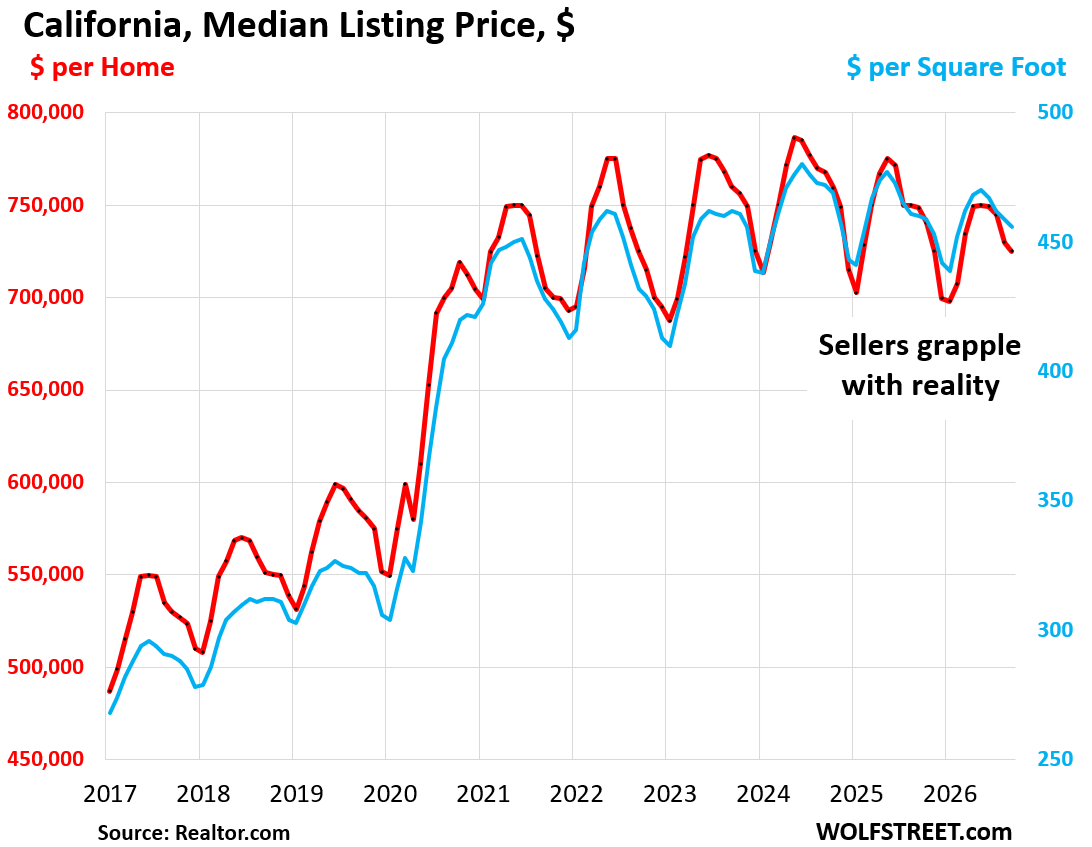
In California, the median listing price in September has declined by 6% from the peak for September in 2024, and by 3.1% year-over-year, to $725,000, the lowest September since, and the same as, September 2022 (red in the chart).
On a square-foot basis, the median listing price has dropped by 3.4% from September 2024, and 1.0% year-over-year, to $456 per square foot.
Transaction prices of single-family homes in many markets in California have dropped more or less sharply from their peaks in 2022 or 2024, and some have made the WOLF STREET list of the biggest decliners of single-family home prices: Oakland (-24%), Hayward (-13%), Sacramento (-9%), Stockton (-8%), San Francisco (-6%), San Diego (-4%), and Los Angeles (-4%).
Transaction prices of condos in many markets in California have made it on the WOLF STREET condo list of biggest decliners: Oakland which fell below the 2006 peak (-32%), Hayward (-17%), Contra Costa County in the East Bay, which also fell below the 2006 peak (-17%), Fremont where the Tesla factory is (-16%), San Mateo County, the northern part of Silicon Valley (-16%), etc.
In Texas, the median listing price in September has declined by 9% from the September high in 2022, and by 2.5% year-over-year, to $355,765, the lowest September since 2021 (red in the chart).
On a square-foot basis, the median listing price has dropped by 4% from September 2022, and by 2.1% year-over-year, to $181 per square foot.
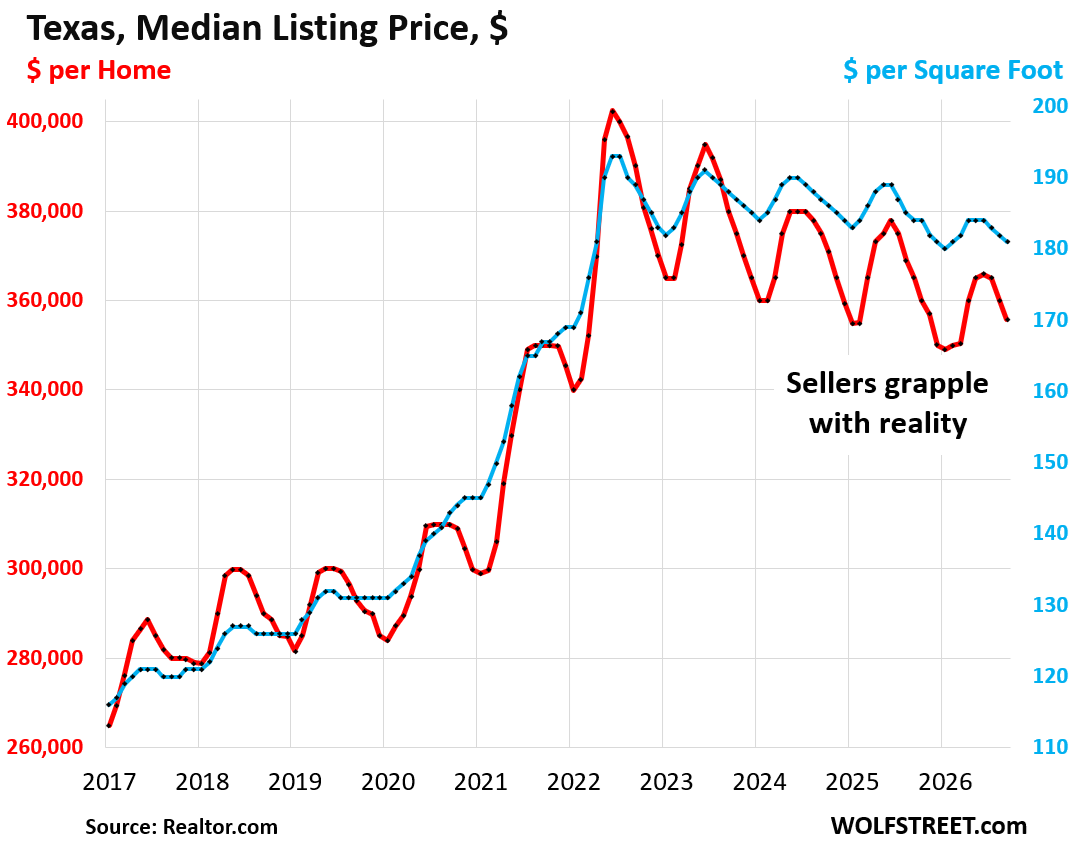
Transaction prices of single-family homes in many cities in Texas are on the WOLF STREET list of the biggest decliners: Austin (-26%), McKinney (-14%), Fort Worth (-11%), San Antonio (-10%), Frisco -10%, Garland (-9%), Plano (-9%), Dallas (-7%), Arlington (-7%), etc.
Transaction prices of condos in many cities in Texas are on the WOLF STREET condo list of biggest decliners: Austin (-28%), Garland (-22%), Arlington (-19%), Plano (-17%), Houston (-15%), Dallas (-14%), Irving (-14%), San Antonio (-14%), Corpus Christi (-13%), Fort Worth (-9%), etc.
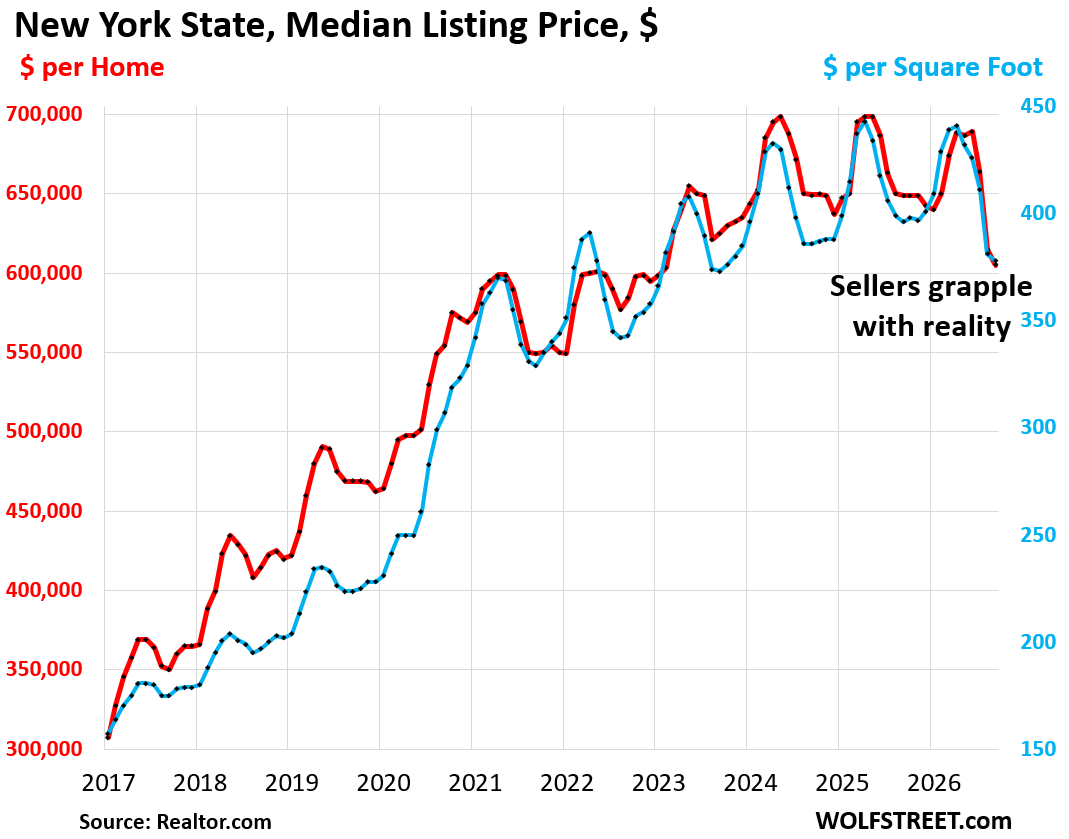
In New York State, the median listing price suddenly plunged in recent months, and by 6.8% year-over-year, to $605,000, the lowest September since 2023, after having flatlined at record levels over the prior two years.
Home prices in the big markets in New York had risen at a modest pace in recent years, while prices in many markets in Florida, Texas, California, and many other states had been falling. New York State was one of the forces that propped up the national median price and other national price indices, and kept them rising in the 1% to 2% range year-over-year. The entire Chicago area was another big factor. Those are huge housing markets that move the needle.
But this sudden big downdraft in listing prices may be a harbinger that change is afoot even in New York, which had been a beacon of strength in the housing market.
This move over the past few months was quite dramatic, with the peak spring months having already been down slightly on a year-over-year basis, but then the bottom fell out over the summer.
Enjoy reading WOLF STREET and want to support it? You can donate. I appreciate it immensely. Click on the mug to find out how:

Just sold my house in Hawaii. Cut $80K from asking price after it sat for three weeks. Got an all cash offer from some trust fund kid and was out right before more homes flooded the market.
Took my proceeds and bought a house in San Diego. The market in SD is shifting. Made an offer (I was the only offer) and we close next week. The house had a ton of work done to it and would have sold for $300K more in 2022. But the long slow grind with high interest rates chipped away a lot of that fake equity and made it somewhat of a buyer’s market.
Is renting cheaper? Yes. By at least $3K a month. But I hate renting and the slumlords that seem to dominate the market in SOCAL who want $5K in rent but won’t fix anything. So I’m glad I’m back to owning even if I am paying a premium.
Buying in Florida right now is catching a falling knife. I’ll continue to sit on the sidelines.
It’s good until suddenly it’s not good.
Trump has had so much latitude due to moral hazard from the easy money era and subsequent helicopter money in 2020… but I feel his latest comments on high inflation being used to deal with the deficit, as daft as they are, was perhaps a bit unwise given how high he’s stacking the plate of inflationary pressures.
Just look how in 2020 prices shot up with rate cuts and easy money.
Now imagine how people feel with high inflation and rising interest rates. Ouch.
Your life will improve greatly if you cease to latch onto every word that Trump utters.
Can I safely latch onto a couple?
I actually think Trump is awesome, he’s basically ToTo and doing a fine job at pulling back the curtain.
One assumed the system was full of checks and balances and sensible authority.
Trump pulled back a curtain only to find a mirror because both parties are inept using ZIRP to borrow and spend while cutting taxes.
It’s a blank check with high balances
“his latest comments on high inflation being used to deal with the deficit, as daft as they are, was perhaps a bit unwise given how high he’s stacking the plate of inflationary pressures.”
I think this is the only way to deal with deficit and debt. and This is happening for last few years.
Other way is: Cut spending which no one wants to do.
“I think this is the only way to deal with deficit and debt. and This is happening for last few years.”
Just roll over and let them steal the fruits of your labor, huh? You’re a good little sheep.
Remember the old adage, those that sell first sell best. Maybe this is what some of the sellers are finally beginning to realize as I know in AZ where I live, prices across almost all regional markets are under pressure. Sellers just need to accept reality and if needed, know when to take their losses.
At a macro level, its hard to see many positives in the housing market right now based on the following. First, home prices are just too high from the drug addiction fueled by easy money (as Wolf has commented on countless times). Second, interest rates are now higher but more normalized (which the easy money minions just can’t seem to grasp). Third, home ownership costs have accelerated over the past three years (with insurance, utilities, R&M, etc. leading the way). And fourth, the demand side of the equation has taken a hit from the immigration crackdown (either from actual deportations or from the fear of being deported as buying a house would most likely be the last thing on their minds).
I’m sure everyone that follows Wolf understands the challenges in the housing market and could expand on my list to include other factors but right now, renting has the upper hand as until home prices correct in a meaningful way and to affordable levels in relation to the total costs of ownership, its hard to envision any type of recovery in residential real estate (except for markets being influenced by “hot” money such as San Francisco which Wolf has already discussed).
@wolf Any chance you have the by square foot info for Denver or Colorado?
Yes I have the data, but there are 50 states and DC, plus many thousands of cities. So this was just about the big four states.
I had to go to an online dictionary for the word “Grapple”
1.) As a physical tool: A hook, claw, or heavy machine attachment (like on an excavator or tractor) used to lift, log, drag, or secure heavy objects.
2.) As a physical fight: A close, hand-to-hand struggle or wrestling match where opponents hold onto each other
3.) As a figurative action: To grapple with a tough problem means to try hard to understand, cope with, or solve it (for example, grappling with a complex math problem or a crisis)
The sad part is that all 3 apply to the current situation in Real Estate. It’ll take quite some time to “un-grapple”.
“In New York State, the median listing price suddenly plunged in recent months, and by 6.8% year-over-year, to $605,000, the lowest September since 2023, after having flatlined at record levels over the prior two years.”
“When interest was at ten percent, land was commonly sold for ten or twelve years’ purchase. As the interest rate sunk to six, five and four percent, the purchase of land rose to twenty, five-and-twenty, and thirty years’ purchase.” [i.e. the yield on land fell from 10 percent to 3.3 percent]. and.. “the ordinary price of land … depends everywhere upon the ordinary market rate of interest.” – Adam Smith
Home prices were intentionally inflated by artificial 2-3% pandemic mortgage rates courtesy of the Fed. Rates are now 7.5%. Prices are sticky to the downside, but mean reversion is a thing, and inflation in all carrying costs is an adder; it’s not just the P+I anymore.
Home prices in the NE and MW have been holding up due to limited supply, but now cracks are appearing in the NY market as “sellers grapple with reality”.
“You can ignore reality, but you can’t ignore the consequences of reality.” – Ayn Rand
I think the quote should actually be as follows…
“You can ignore reality, but you can’t ignore the consequences of ignoring reality.” – Ayn Rand
“Home Sellers Grapple with Reality:”.
Reality? Reality is that homes and home sellers are sitting on the precipice of the Grand Canyon.
Oh, I know – people will say it’s not so bad right now. In fact, in some areas the illusion is alive and well. All it’s going to take is a small tremor to two, or ‘the Big One’ and the party will mot only be over but all those homes will be sitting on the canyon floor.
The Big One could be the bursting of the AI bubble – one of many scenarios.
Housing or a home?
That is also a consideration for buyers. In fact, it has always been my main reason for owning a home for the last 50 years. I do not regret one aspect of home ownership and if my home loses value from the recent highs then so be it. It is all relative. if your price is down then a relocation move will also be down, provided you do not move to a higher price area.
Homeowners don’t worry!
InflationMan is here to save the day!
Normally you know your home prices would drop into the S@#+ bucket. But not these days!
Inflation is like a puffy pillow to prop up your home prices. It makes buyers pay more every year. Woo.
New York?
Only Whores and Gangsters live in New York
Sounds like a fun place. How do I get there?
Thumb out on the highway
🤣 I did that in 1981, during the big bad Double Dip recession, from Tulsa to Manhattan. Took three days. Was great (but sleeping near express interchanges, were I got dropped off after dark, was not that great… even back then, it wasn’t smart to hitchhike after dark)
Now now…Thats just Wall Street
Hey my wife lives in New York!
I bet she’s a gangster.
Lived there for 13 years- place has everything….disco pants and haircuts too……love my time in NYC- miss it. One of the few places that can approach reality on a daily, minute by minute, second by second basis. Grew up on the west coast, now live in dixie land, love both places, but miss NYC badly.
See that $340k level in Florida? Thats where prices need to return and until they do the housing markets is a dung pile.
But living in the land of 95% relative humidity, corrupt government, and Zika virus is such a privilege it’s gotta be worth going into life-altering, generationally devastating levels of debt, right? They have Disney Land, which you’ll not be able to afford to visit.
Chris B….
“But living in the land of 95% relative humidity, corrupt government, and Zika virus is such a privilege”
I think your opinion of the South is fine. It sounds like you don’t want to come…..
Which is also fine.
But your stated opinion might be a little off.
38 percent Relative Humidity right now, and no Zika in sight….
And my city’s budget is in the black, and they are paving roads, upgrading infrastructure, etc. with taxes still reasonable.
And the schools are thriving, top notch new facilities with the scores to back.
So you might be a bit off. But I guess to each their own.
The best of luck to buyers and sellers alike.
Sounds like everyone is gonna need it.
LoL, now the slide begins. Finally. The Fed could cut rates and try to slow real estate, if given energy pressure abatement. But now comes a hard reality, only in specific places with high employment driving demand will prices stay up. And in the rest, early selling will drive drops, just like the beginning in 2006. But, in this case, I think drops will end up smaller as the homebuilders quickly set the bottom on their spin down.
We have seen this playbook before, and pros will sell fast to survive. And hope for lower rates is not a viable strategy.
If I were a buyer – I’m not – I’d only submit lowball offers of 50% off. The housing market was overcooked in 2018. It’s delusional today.
“just like the beginning in 2006. But, in this case, I think drops will end up smaller”
Back in 2008 too many banks were exposed and they kept a floor on prices by holding properties off the market. I personally knew a couple that didn’t pay their mortgage for 48 months, with the bank paying the property taxes the entire time, and then by 2012 prices recovered and the bank finally started foreclosure but they found a buyer.
Who’s going to keep the floor on prices this time?
More than 10,000 Las Vegas Valley homes are for sale for the first time since the Great Recession.
Brownell Analytics counted 10,344 at the end of August, according to the Review-Journal.
Get out before the roulette wheel stops spinning
In Texas prices are still way too high. Interest rates are now at 2000 levels. Everything is 200 to 300% too high. 400K homes should be 140K or less. Fredericksburg is the poster child. 900sqft house on a 5000sqft lot, 500K. That’s the lowest one. There are no real jobs there. True value 50K. People are still in denial. The pain is just beginning.
Wolf, I really like that you listed square foot pricing in those charts above. That’s so telling to me. Back in the day, the average square foot pricing around Tampa was ~ 100 sf ~. That’s the benchmark I used to determine value. that was in the nineties.That also happened 2009-2012 or so. That’s non waterfront. So using that as a cost basis, housing in my area is still way way overpriced. Just sayin… I do not think we will see those prices ever again, but time will tell.
Watch the demographics. It might when the old folks’ estates try to sell their snout houses to a younger, broker generation!
I’ve always felt that there is a disconnect between the price of land and the price of the buildings on the land. Some neighborhoods discount the value an old house on the lot to zero. Builders come in and buy the land for the lot, take down the old house and start again. People pay a fortune for fancy new houses that will depreciate rapidly over time unless you keep renovating. The builders are driving around in Porch’s, and fancy F150s. I wonder if the the home price changes we monitor reflect the upgrading and resale building activity.
Depends on the property. Location location. And yes houses can be worth nothing when the cost to renovate exceeds reality.
Florida is a more of unicorn than anything else when you take into account that they still have a ton of excess housing sitting there from 2008-09. It will probably take them another two plus decades for that to get sopped up. Still building too, of course. I don’t necessarily put a lot of emphasis on what happens in FLA just because of all of that. Markets that remained a bit more normalized during 08-09 to me are more of an indicator. You also have such a wild swing geo-politically between our largest states that it is also difficult to know how much that plays in all of this. Currently L.A. is essentially seeing Hollywood back up the u-hauls and leave town. I will say, long overdue all things considered, but that leaves what is essentially a giant housing development without one of its primary businesses- be interesting to see how that plays out. NYC continues to do one stupid thing after another, my old home town saddens me with their decisions politically and economically/legally. Took one of our daughters up there to tour FIT, not to worry, she decided to stay in state and is now at UNC Chapel Hill and happy tar heel, but we walked a lot of midtown, lower east side and I have never seen that many empty store fronts in the city, even when I got there for college in 1990 and Dinkins was doing his best to burn the place down.
New York State is a massive area with many depressed economic areas in upstate NY regions like the Southern Tier that were gutted of jobs in the last 40 years. I assume this was a statewide decrease, but how does it look closer to NYC in the Hudson Valley?
From what I see the prices are getting more eye watering each day in the desirable places that I monitor.
What may be the reason for the zigzag price pattern for median home prices in New York and California over the last few years?
Seasonality. It’s the same in the national median price index. Median prices are skewed by changes in the mix. A larger number of more expensive homes come on the market in the spring and are sold in the spring, and this shifts up the median price, and then in the fall and winter, a smaller number of more expensive homes come on the market, and this shifts the median price back down. And this happens even when actual prices do not change. This is a big shortcoming of median prices.
I explained this here with a fictional mini market and table of 11 homes that shows this effect:
https://wolfstreet.com/how-median-home-prices-are-skewed-by-changes-in-the-mix/
Charts all looking like rolling over
New Single Family Home reductions leading the way .
Global property bubble now starting to deflate and how much gas will come out this time .
The biggest property crash yet is imo has just started , too many people in the US mortgage trapped , how long will they stay there at 3.5% ?
Governments have caused the problems
Governments are going to have to solve them
If they don’t or can’t then revolutions cometh.
Interest payments might become a thing of the past somewhere down the line as a result of Government mistakes and greed.
Dams burst
Massive storm coming that will swamp all those fools who bought in a hurricane zone, their $$ washed out to sea.
As bad as all those banks and fools who bought bonds ar 2, 3 and 4 %.
Big Fat Ugly Bubble, I think the quote should actually be as follows…
“You can ignore reality, but you can’t ignore the consequences of ignoring reality.” – Ayn Rand
Finally we are back on the pre-covid trend. I must admit to doubting that this would be allowed to happen. California still dragging its heels, but the other 3 states all look to be trying to break through the old trend line too.
A few more years and we’ll finally be seeing some semblance of relief for the buyer side of the market.
I think most of those lanlords who got their rental homes before 2020 (whether they refinanced or not) will be ok even if home prices are dropping. If they are in a tech city, then they ar likely to always have an army of renter pets unless the rentoids lose their jobs en masse.
As for those who overpaid pot 2020 & are now unable to sell, I am sure their debts will be inflated away as Trumpanion recently hinted. They only need to able to hold long, which they will if they are tech couples or such.
Signed,
Supreme leader of Landlordistan (formerly USA)
I live in Fort Myers and I’ve been here 9.5 years. I have firsthand, on-the-ground information on what is happening down here. The drunken party during the pandemic years that pushed home valuations into artificial, stratospheric levels, which sparked bidding wars and no-inspection offers far above the asking price has mercifully ended. However, the carnage left in it’s wake remains.
I recently took my house of the market this summer after 18 months on the market and multiple price drops. I had a threshold below which I refused to go. This home is my retirement and having 100% equity in it is also my pot of wealth. My neighbor sold their home 2 months ago after 3 months on the market at around 176/sf. My house, with the same square footage, was priced around 192/sf. The differences being lovely, tropical landscaping on my property, a huge wraparound deck in the backyard and two separate driveways for plenty of parking. The house next door has none of these features.
One additional item is that the house next door was a long-term rental. The renters, who were related to the owner, left in February 2026 after they bought a new home in Cape Coral that came with incentives and financial assistance. So, for about 6 months, the former rental house next door was a non-performing asset. I live in my house and maintain it constantly. The rental next door required a lot of maintenance and upgrades before it sold including a new HVAC system.
My older, established neighbor inside city limits is close to shopping, entertainment, downtown Fort Myers and numerous other amenities including a 20 minute drive to Fort Myer’s Beach and the Islands. However, new home development in Western and Northern Cape Coral is adversely affecting existing home sales in the entire Fort Myers metropolitan area.
Development for these new communities was approved over a decade ago. The housing market was a lot different back then. Today, the developers are trying to offload these homes at steep discounts and including freebies to shrink bloated inventories. At the same time, more new homes are coming out of the pipeline due to excessive exuberance during the halcyon days of the migration to Florida and the WFH ethos.
On the local news, nightly these new residents complain about lack of infrastructure, traffic jams, crowded stores and rising costs of living all around. Gee, what a surprise. This is what you get when local governments are more interested in tax revenues instead of maintaining a quality of life outlook for it’s residents.
Remember, we were ground zero during the real-estate led “Great Recession” during the 2008-2010 years. It seems like a lot of these elected county and local officials have forgotten that. If another similar recession were to hit in the next year or two or three the effects would be devastating. However, the more likely event may be natural.
Between climate change, record warming of Gulf waters, we seem to have begun a magnet for hurricanes. In the 9.5 years since I moved to SW Florida I have endured 3 hurricanes: Irma, Ian and Milton. My insurance has quadrupled in the past 9 years. Being retired and on fixed income helps and hurts my personal circumstance. However, for working families with mortgages and required insurance to service those loans another hurricane or recession would be devastating.
Florida is unique in comparison to other states. We are a gigantic sandbar sticking out among 3 large bodies of salt water. As the ice caps melt and ocean levels rise, this sandbar may be reclaimed by nature. Look to Miami Beach and their frequent issues with flooding. I used to live there many years ago and it was bad back then.
As I write this piece, Hurricane Isaias has formed in the Gulf of Mexico. It is expected to make landfall Friday night in the Northern Gulf region as a cat-2 storm. Isaias is late to the party this year. We got lucky this year. How long before our luck starts running out? This is the changing world and climate we live in. Cheers.
Fifty year Sanibel owner here. Ian made a mess but prices for houses built with flooding in mind seem to have become more desirable. Unfortunately a lot of the new building is too large and tasteless.