How Americans are handling their debts.
By Wolf Richter for WOLF STREET.
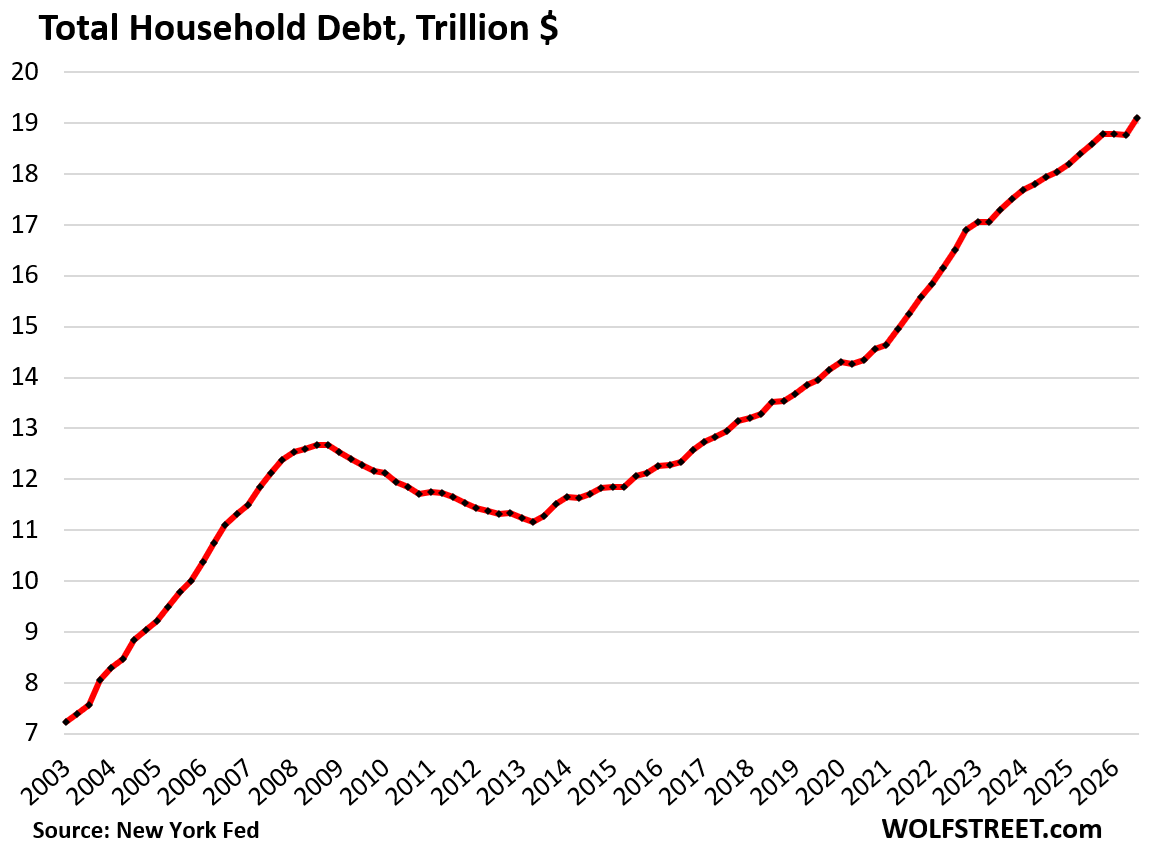
Total household debt outstanding in Q3 rose by $334 billion from Q2, or by 1.8%, to $19.1 trillion, after having been nearly unchanged for two quarters in a row, according to the Household Debt and Credit Report from the New York Fed, which obtained this data via its partnership with Equifax. Total household debt includes mortgages, HELOCs, student loans, auto loans, credit card balances, and other consumer loans such as personal loans and BNPL loans.
The quarter-to-quarter increase was largely driven by mortgage balances, which jumped by $257 billion, after declining in Q2. The unusual decline in Q2 had been “due to a temporary gap in the reporting of mortgages on credit reports due to a transfer of servicing,” the New York Fed had explained at the time. And now the missed data from Q2 was included in Q3, causing the Q3 mortgage debt to jump from the under-reported Q2 balances.
Year-over-year, total household debt rose by $520 billion, or by 2.8%, the second smallest increase since Q2 2021, behind only the prior quarter.
The burden of the debt.
Total household income has risen over the many years, as more households were formed, and as incomes increased per household. In addition, there were years of wage inflation, consumer price inflation, and home price inflation. So total household income has grown over the years since the Financial Crisis far faster than total household debt, and the burden of that debt on households has declined over the years.
The debt-to-income ratio is a classic way of evaluating the burden of a debt. With households, we can use the debt-to-disposable-income ratio.
Disposable income (by the Bureau of Economic Analysis) consists of after-tax wages, plus income from interest, dividends, rentals, farm income, small business income, transfer payments from the government, etc.
But it excludes capital gains, which is where rich households make most of their money. Excluded are thereby income from stock-based compensation plans and capital appreciation where billionaires make their billions.
The debt-to-disposable income ratio in Q3 ticked up to 78.9%, as disposable income rose to a record while debt balances increased slightly faster. But the Q2 ratio had been pushed down by the above-mentioned gap in mortgage reporting. Q3 simply ironed that out.
Both Q3 and Q2 were the lowest in the data going back to 2003, except for two quarters during the stimulus era, when disposable income was inflated by the stimulus checks, PPP loans, and numerous other government handouts.
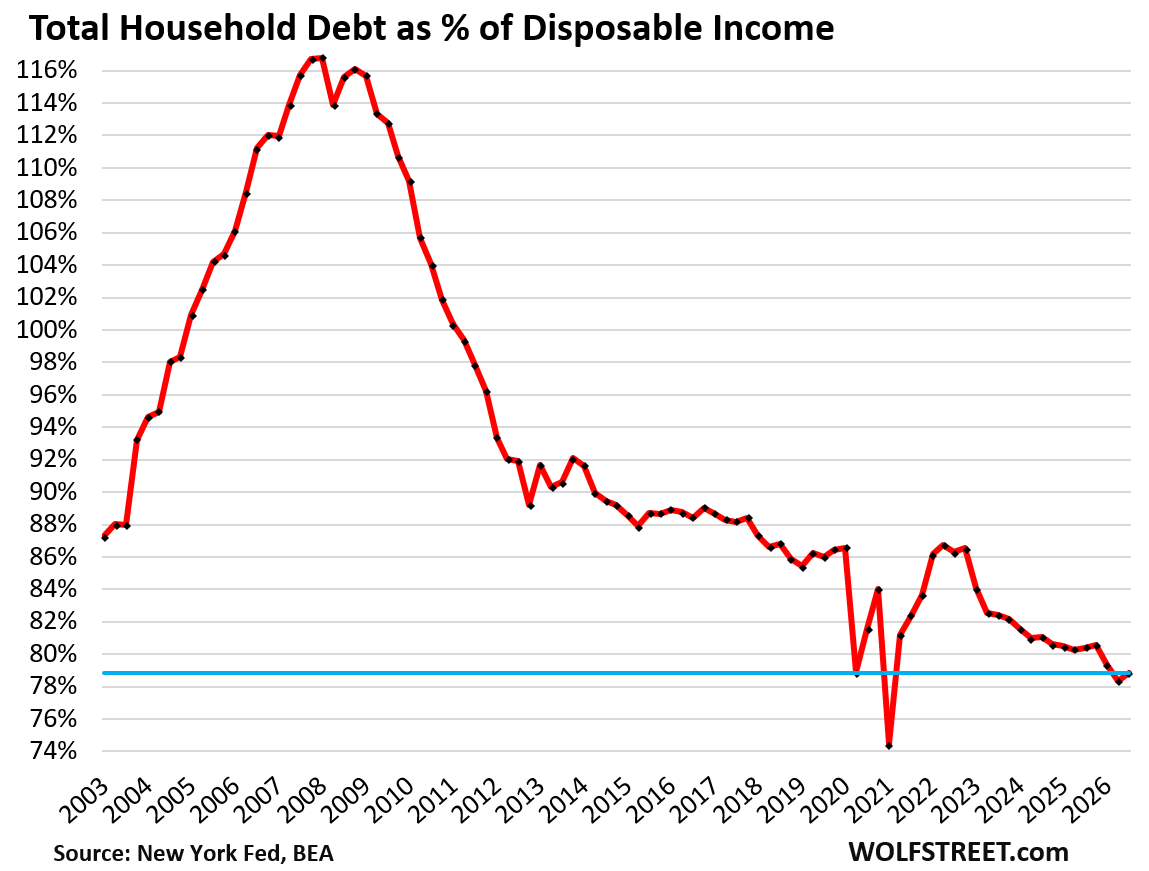
It’s obvious where the problems were leading up to the Financial Crisis: Consumers were way overleveraged, and banks were on the hook for this debt, which came on top of all the risks banks had loaded up on over the 10 years since the Glass-Steagall act was repealed. When the debt-to-disposable-income ratio passed 100% in 2005, all red alarms should have gone off at the same time.
Household balance sheets are now in good shape overall. 65% own their own homes, and home prices soared over the years through mid-2022, and these households are sitting on huge amounts of home equity. About 40% of homeowners own their homes free and clear. Another big portion of homeowners has only a relatively small balance left on their mortgages. Over 60% of households have at least some equities, and their values have skyrocketed over the years. Households hold precious metals and cryptos. And households have over $5 trillion in money market funds and a large pile of CDs.
The leverage risks today aren’t with households but with overleveraged businesses, including those in the AI trade, and the massively over-indebted federal government.
Delinquency rates.
Federal student loans that had been covered by the government’s forbearance policies since 2020 came out of forbearance in 2025. While in forbearance, borrowers didn’t need to make payments, and their loans weren’t counted as delinquent, and student loan delinquency rates plunged to near zero.
But in 2025, when forbearance ended, loans showed up on credit reports as delinquent again when borrowers failed to restart the payments, and serious delinquency rates for student loans exploded back above 10%, where they’d been before the pandemic. This once-again high delinquency rate pushed up overall delinquency rates.
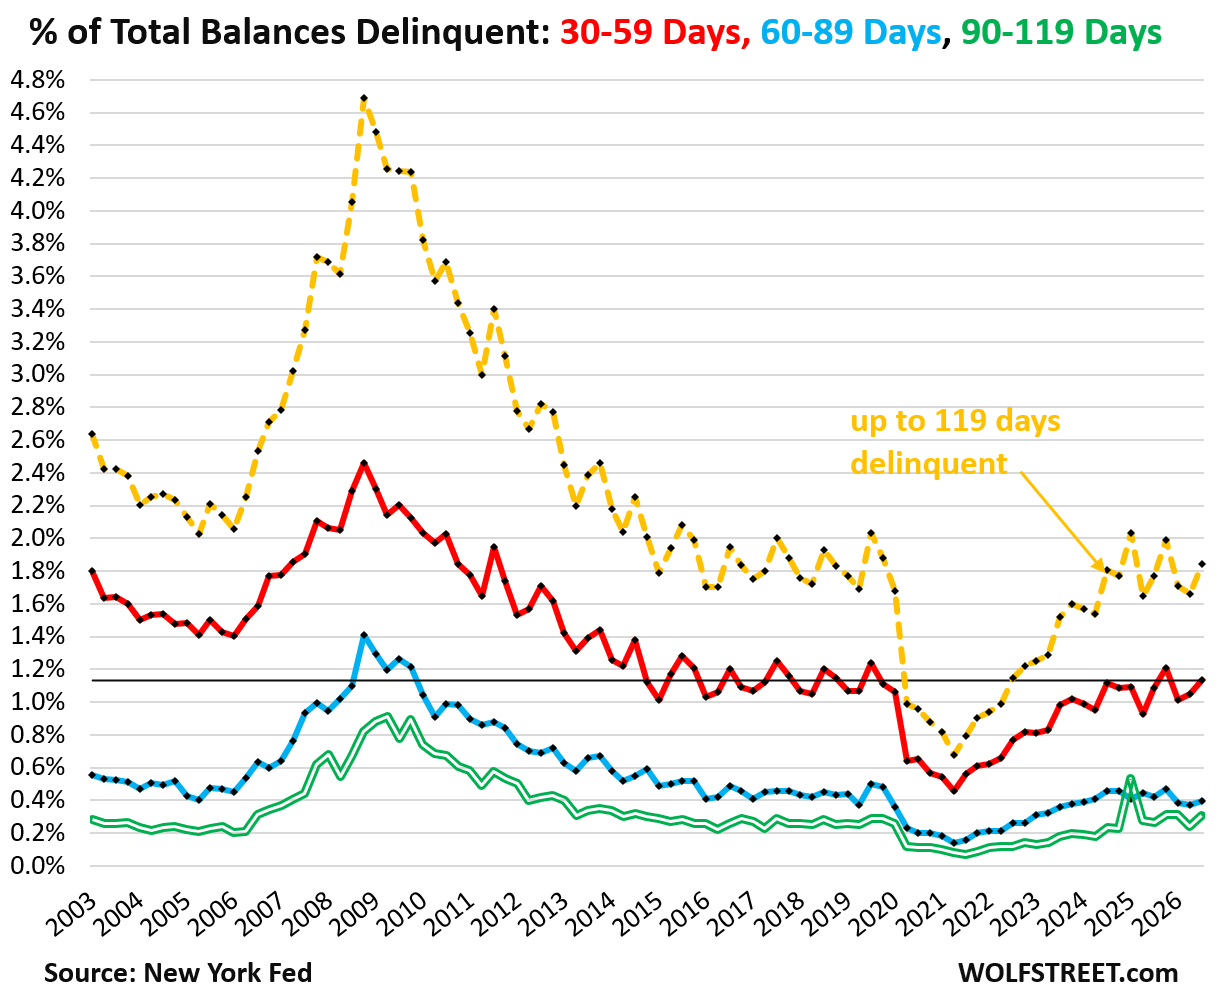
Here are the delinquency rates for total household debts by delinquency status, per the New York Fed’s Household Debt and Credit Report, based in Equifax data:
- 30 to 59 days, (red): 1.1%
- 60-89 days (blue): 0.4%
- 90-119 days (green double line): 0.3%
The dotted yellow line shows the combined delinquency rate for the three categories, all debts delinquent up to 119 days: 1.8%
Delinquency rates are at or below where they’d been in the three years before the pandemic, and far below the prior years. They have risen from the near-zero rates when delinquent student loans and mortgages were in forbearance and didn’t count as delinquent.
Mortgages make up 70% of total household debts, and they have low delinquencies. Delinquency rates are substantially higher for other loan types and huge for student loans (we’ll get to each debt category over the next few days, so stay tuned).
In the category of 120+ days delinquent, there is a lot of old, charged-off stale delinquent debt on credit reports that hasn’t been removed yet. The New York Fed, in a blogpost a few months ago, clarified this issue with regards to credit cards, and summarized:
“We find that the stock delinquency rate is rising because of a pool of stale, charged-off debts that lenders have been reporting for longer durations, rather than a fundamental worsening in the incidence of delinquency.”
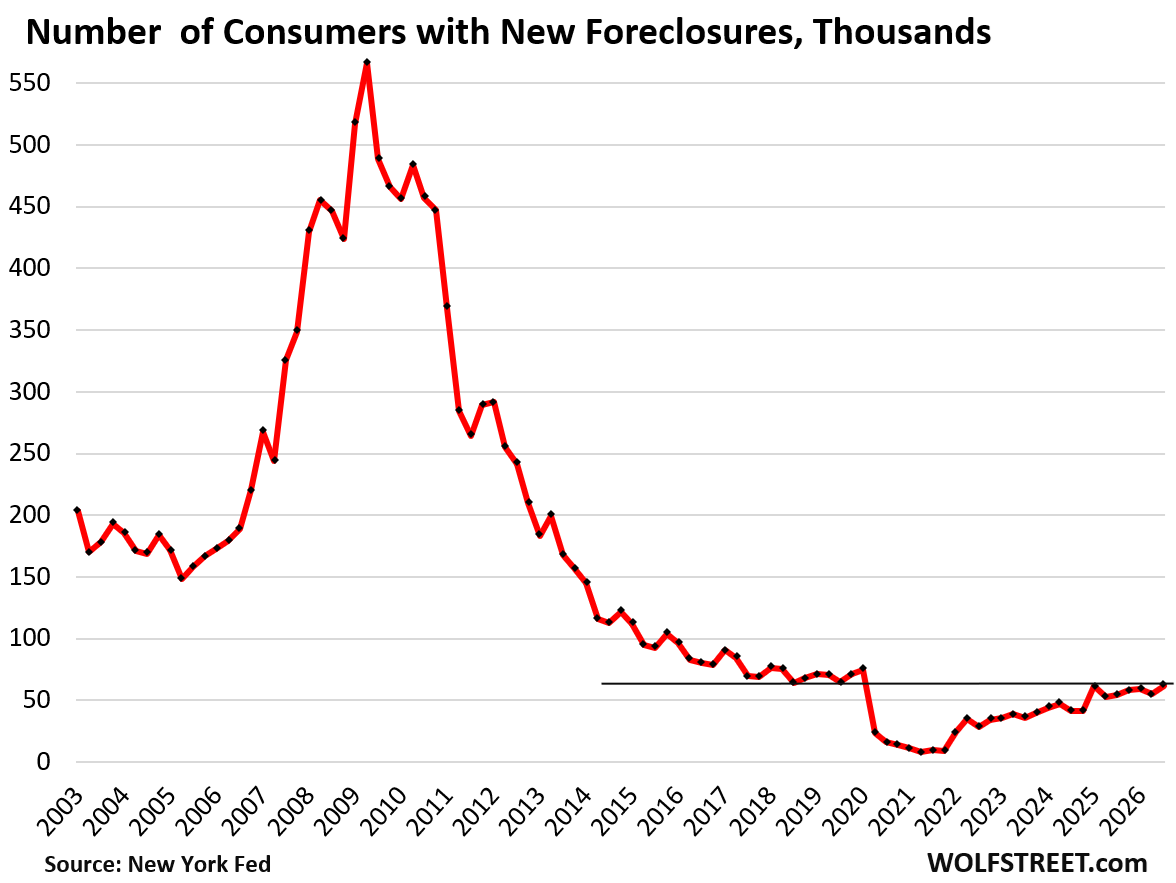
New foreclosures in Q3 edged down to 61,900. During the era of mortgage forbearance and foreclosure bans, foreclosures were near zero because they were essentially impossible.
Foreclosures are now at the very low end of the three years before the pandemic, far below the number of foreclosures in prior years, and historically low.
Condo prices have plunged in many markets and condo supply has shot up, while sales have plunged, and walking away from the condo and the mortgage would seem to be the next logical step. But we haven’t seen a visible uptick above the pre-pandemic years in foreclosures yet.
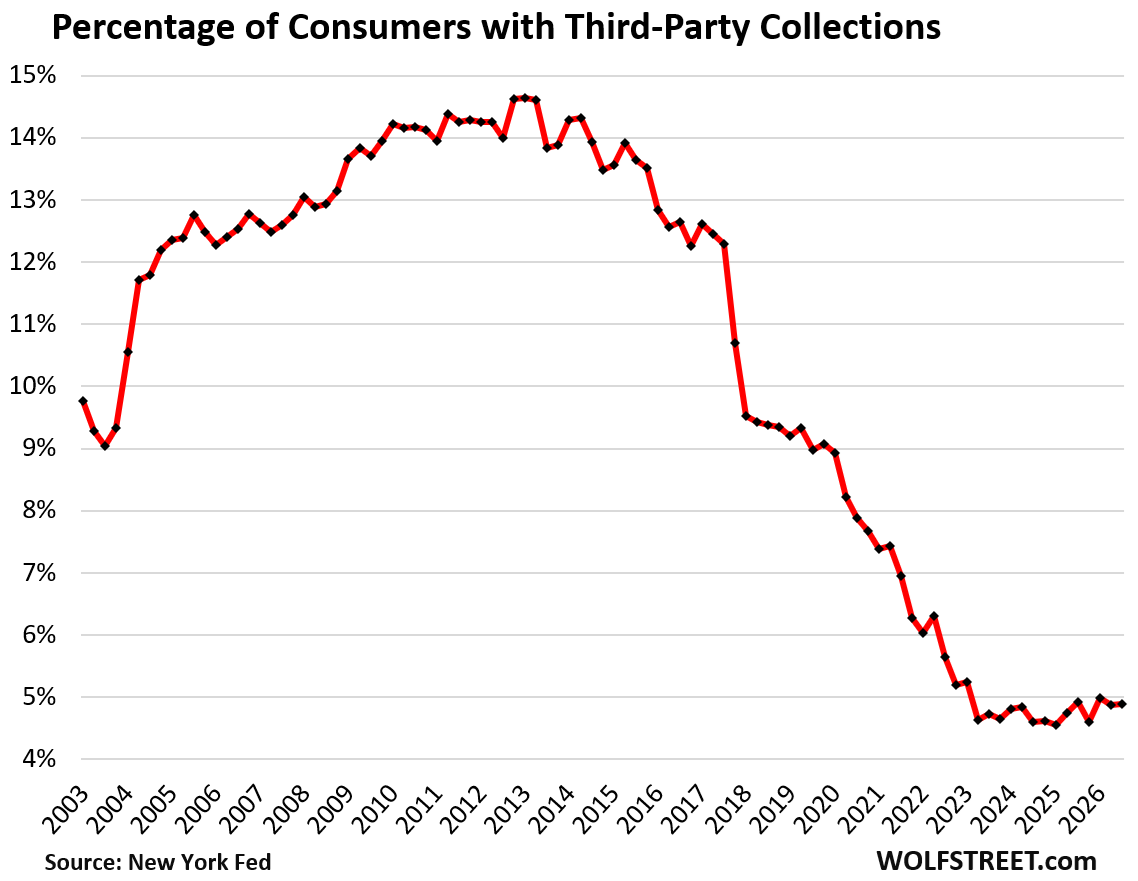
Third-party collections were essentially unchanged from the prior quarter. The percentage of consumers with third-party collections on file within the past 12 months remained at 4.9%, stuck at rock-bottom.
The collections data is based on public records and credit reports. The majority of collection actions result from unpaid medical bills and utility bills, according to the New York Fed’s Data Dictionary. Credit accounts, such as credit cards, make up only a small proportion of collection actions.
The share of households with third-party collections on their records had exceeded 14% from 2008 through 2015 as a result of the mortgage crisis, the Great Recession, and the unemployment crisis, during which many households fell behind on their bills, and those arrears were eventually turned over to third-party collections.
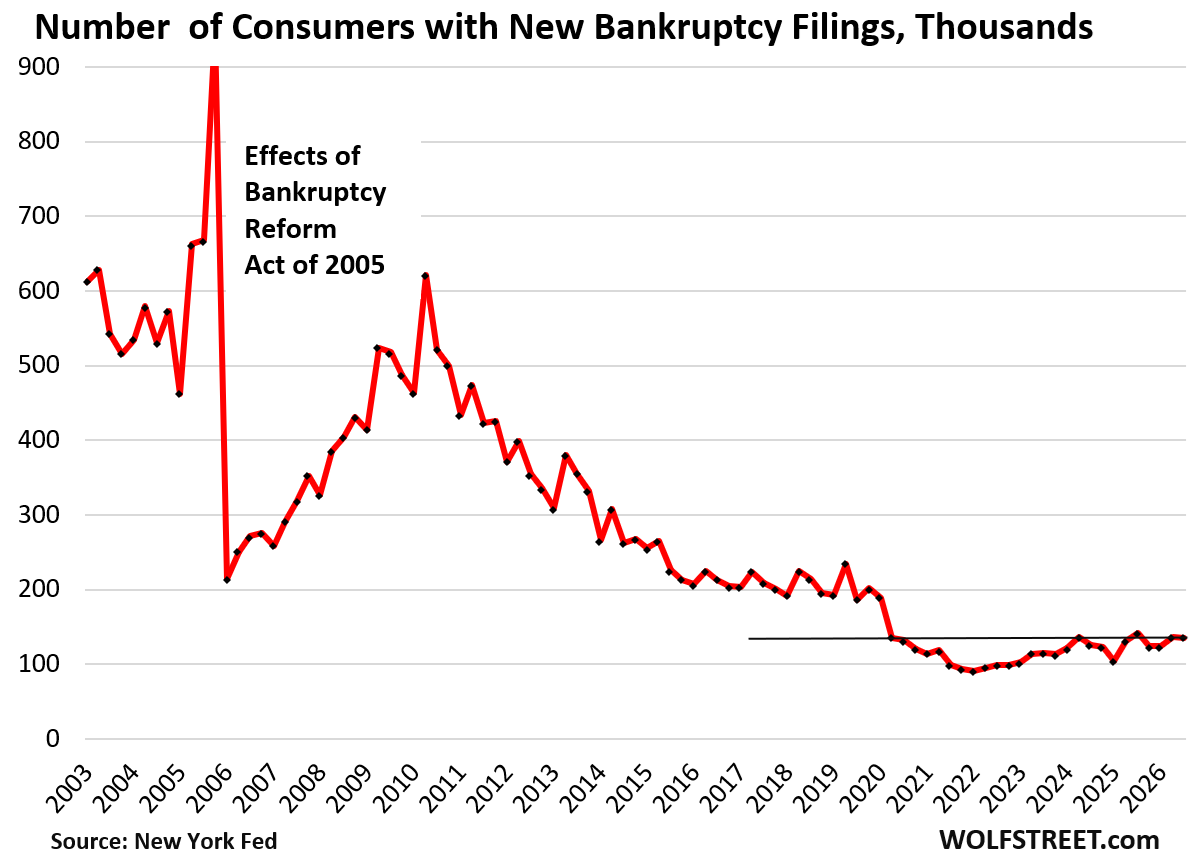
New bankruptcies remained at rock-bottom. The number of consumers with new bankruptcy filings in Q3 edged down to 135,220, far below the low end of the Good Times before the free-money pandemic.
I will discuss housing debts, auto debts, and credit card debts in three separate articles over the next few days. Next one up is housing debt.
Enjoy reading WOLF STREET and want to support it? You can donate. I appreciate it immensely. Click on the mug to find out how:

The last time debt to DPI was this low was 1998!