The housing market just keeps getting worse. Sales in the West collapsed to the lowest since at least 1999, in the Midwest to 2011 lows, in the South to 2012 lows.
By Wolf Richter for WOLF STREET.
Sales of existing single-family homes fell by another 5.8% in October from September, seasonally adjusted, and by 8.6% year-over-year, to an annual rate of 3.41 million, the lowest since October 2010, during the depth of the Housing Bust, according to data by the National Association of Realtors today.
Sales were down by 29% from October 2019, by 38% from October 2021, and by 9% from 30 years ago in October 1996.
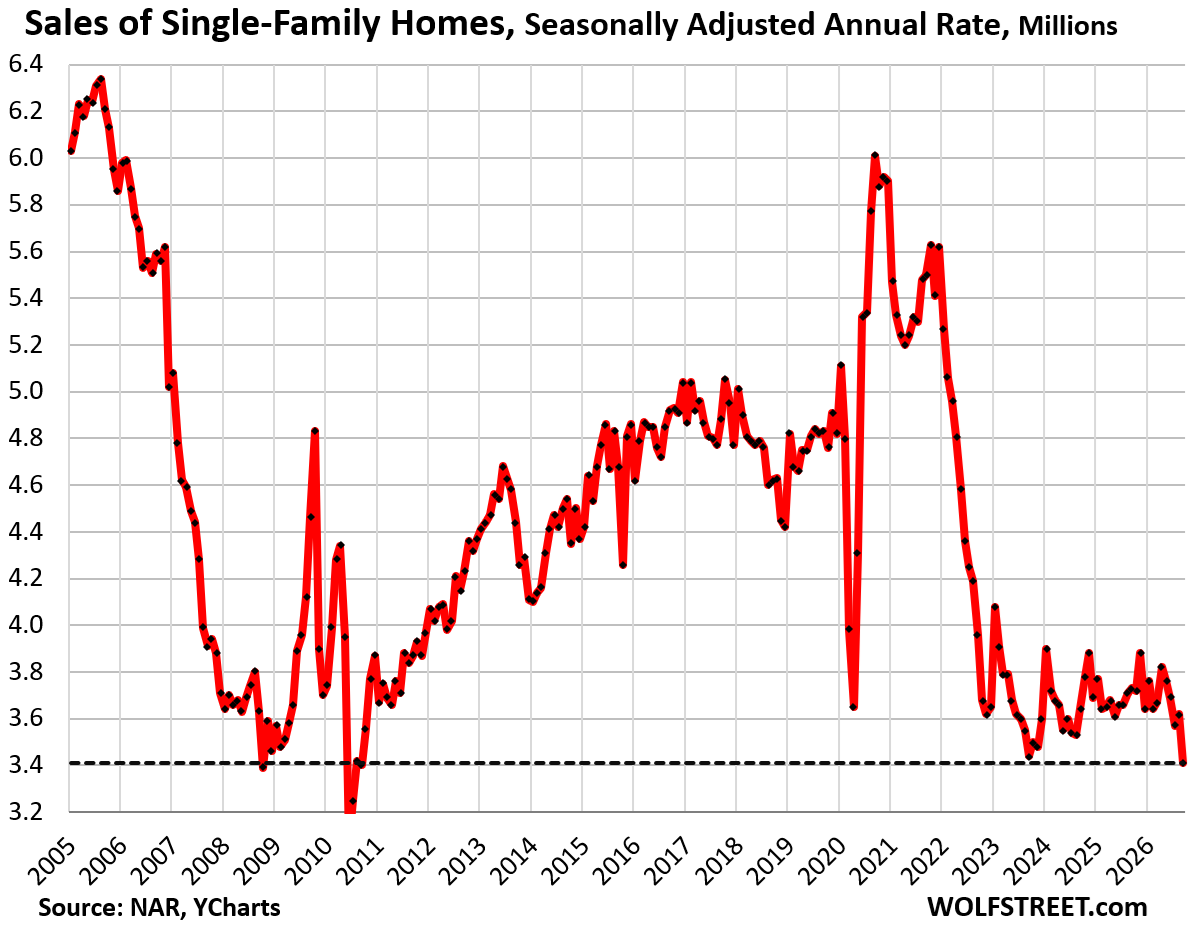
Not seasonally adjusted, and not annual rate, sales plunged by 11.7% year-over-year to 287,000 actual single-family homes sold.
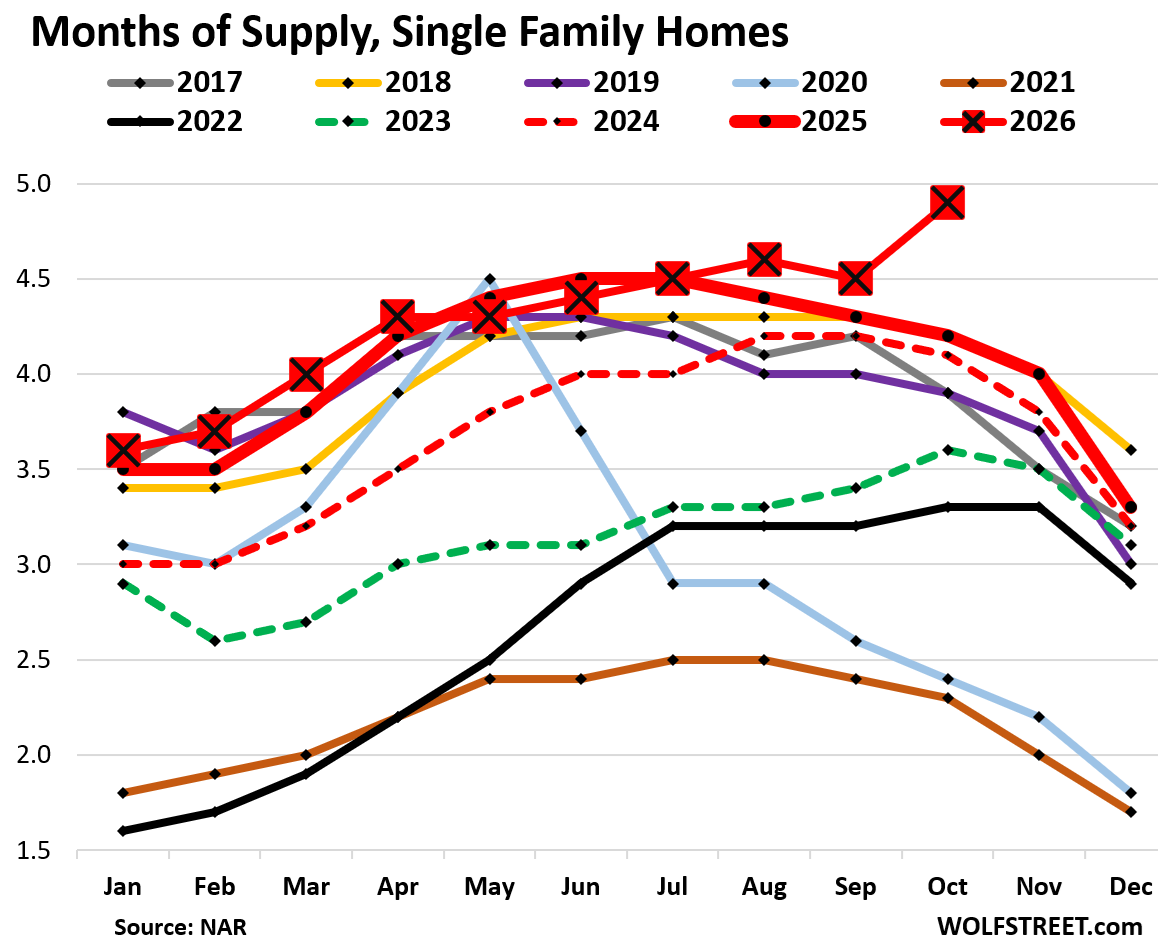
Supply of single-family homes jumped to 4.9 months in October, the highest supply for any October since 2014.
Supply is a function of inventory and sales – how much inventory there was at month-end in relationship to sales during the month.
The stacked chart shows 2026 in red with big red squares, 2025 with the fat red line, and 2024 with the dotted red line. Supply has increased year after year, every single year, since the low point in 2021.
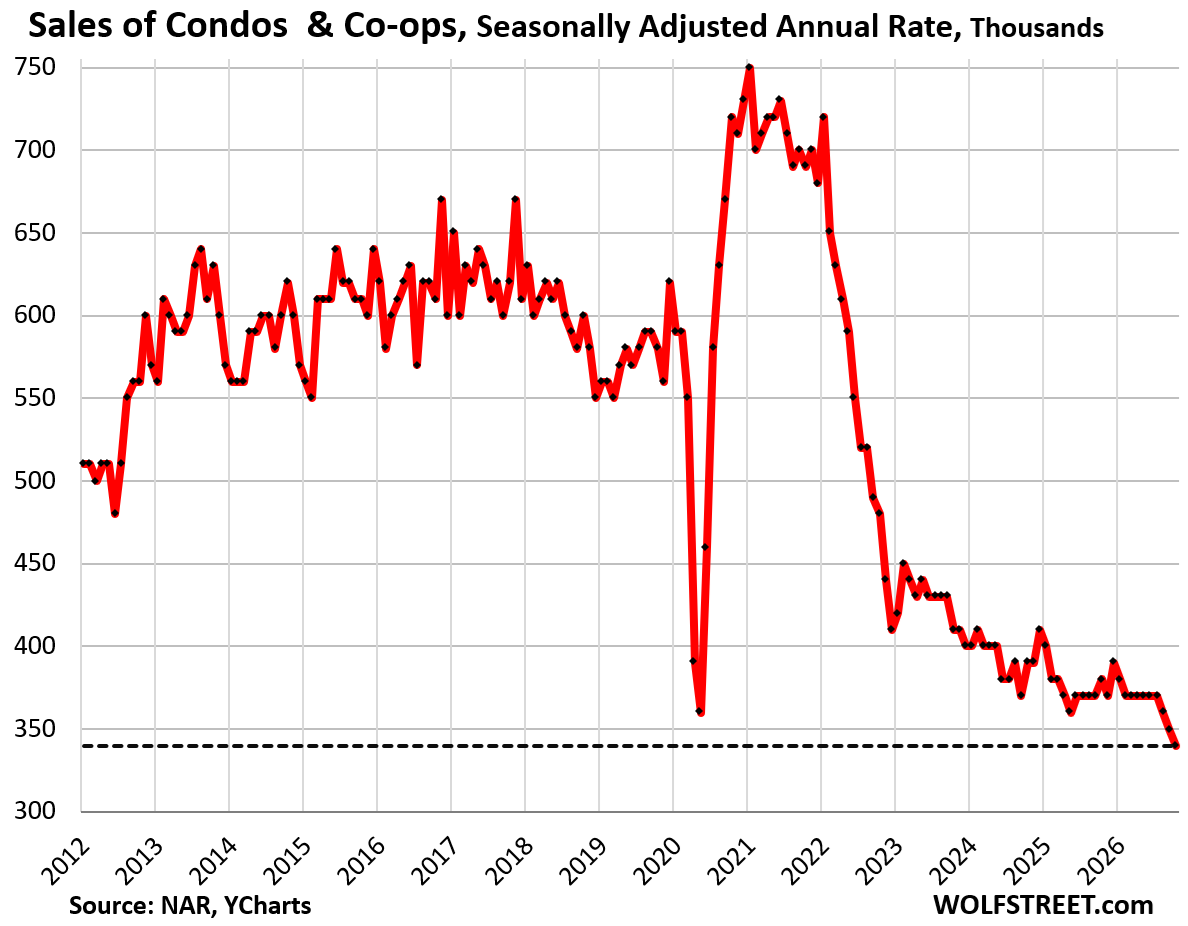
Sales of condos and co-ops dropped by 2.9% in October from September, seasonally adjusted, and by 10.5% year-over-year, to an annual rate of 340,000, a record low in the data that go back only to October 2011.
Compared to October 2019, sales collapsed by 41%. Compared to October 2011, the first October in the data, sales collapsed by 28%.
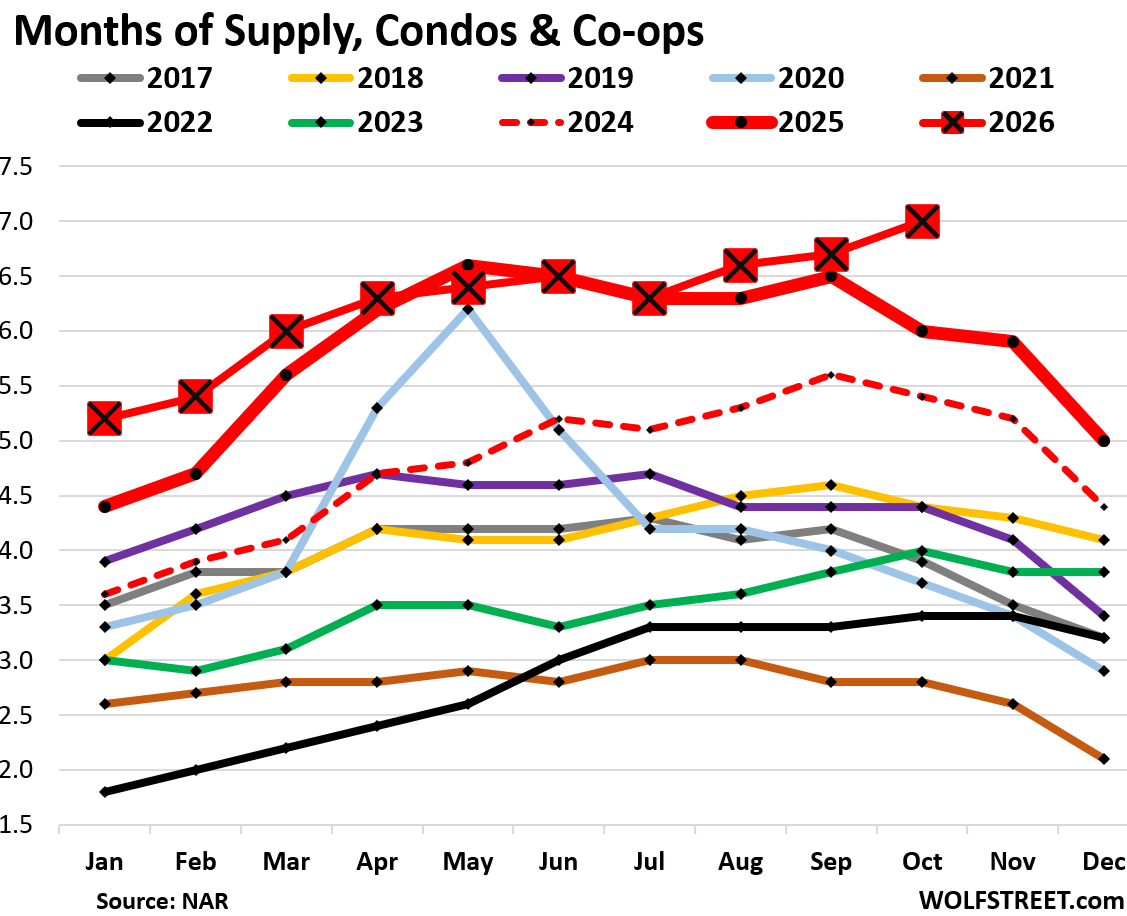
Supply of condos rose to 7.0 months in October, the highest for any October since October 2011.
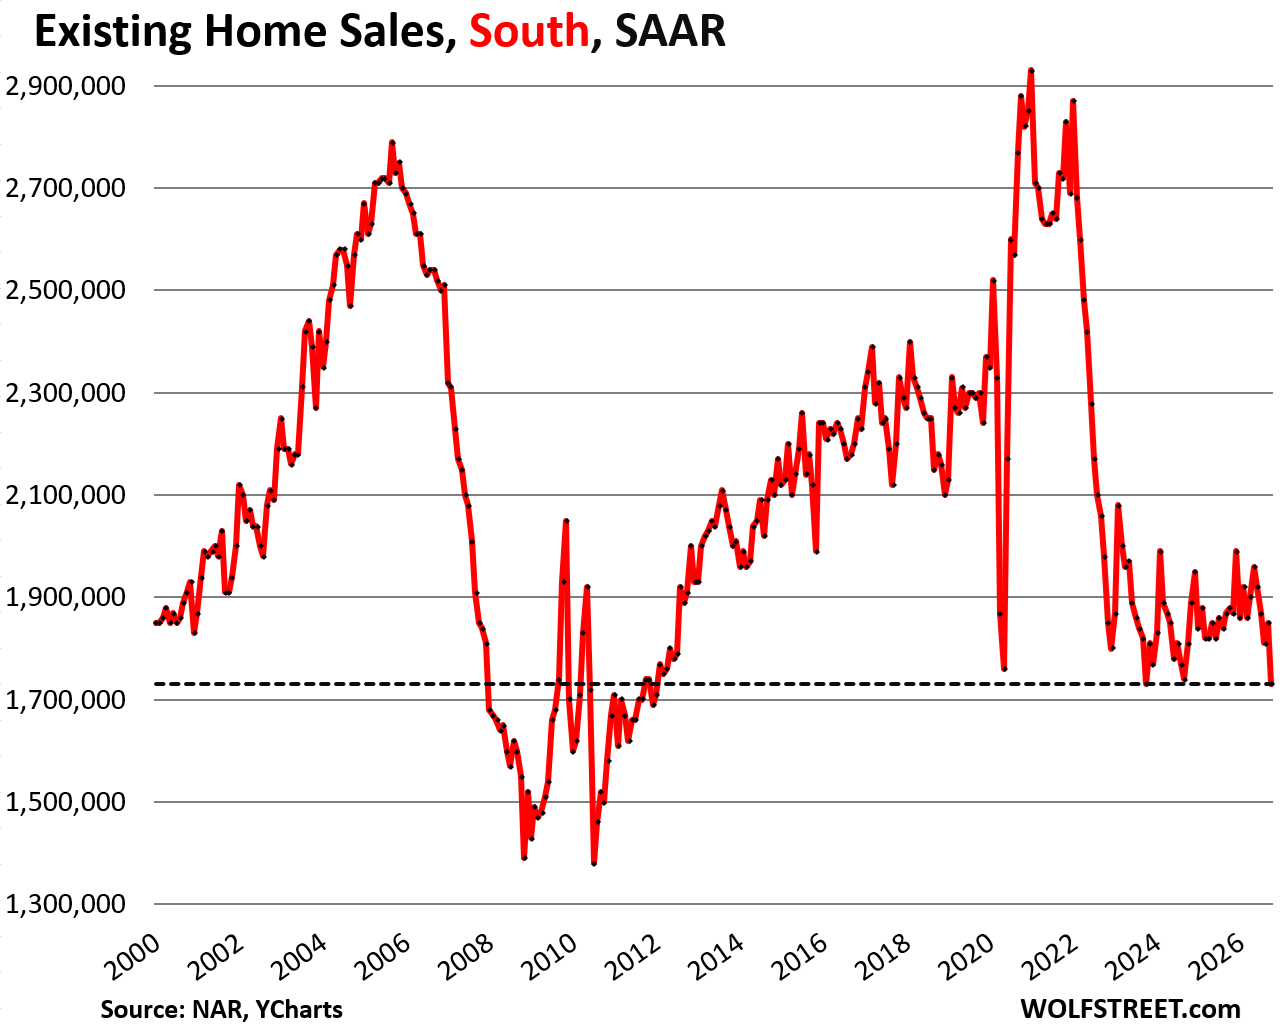
Sales by region, all existing homes (single-family, townhouse, condo, co-op).
In the South, the seasonally adjusted annual rate of sales of all existing homes (single-family, townhouses, condos, and co-ops combined) plunged by 6.5% in October from September, and by 8.0% from the beaten-down levels a year ago, to 1,730,000 homes, matching October 2023, and both were the lowest since January 2012.
Compared to October in prior years:
- 2025: -8.0% (year-over-year)
- 2024: -4.4%
- 2019: -24.8%
- 2018: -20.6%
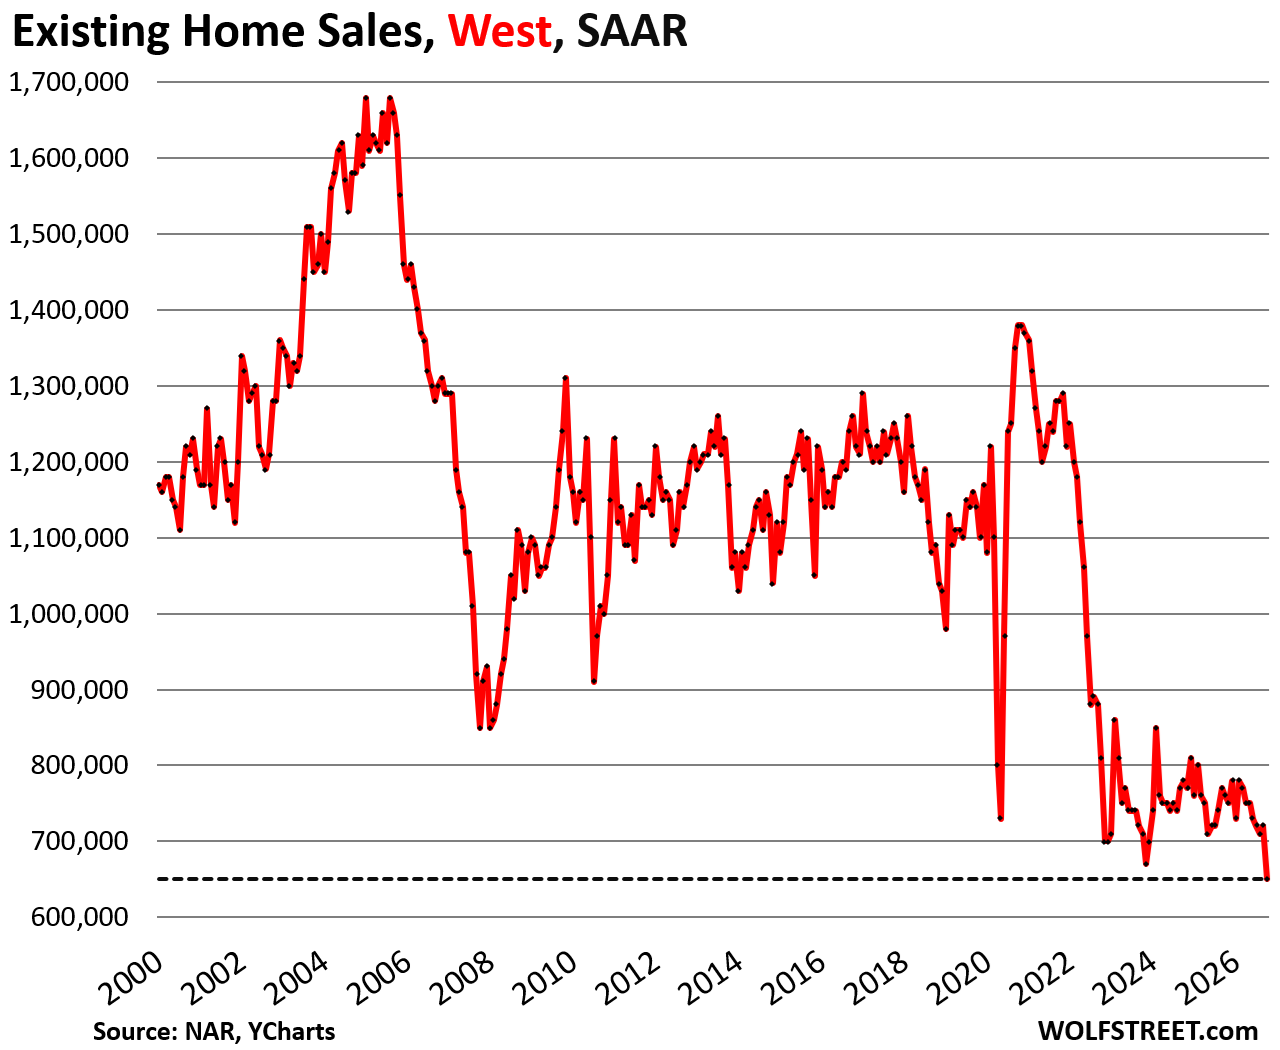
In the West, the seasonally adjusted annual rate of sales collapsed by 9.7% month-to-month, and by 14.5% year-over-year to 650,000 homes, the lowest in the data going back to 1999.
Compared to the prepandemic Octobers in 2018 and 2019, sales in the West have collapsed by over 40%, and it’s not because there’s “nothing to buy,” but because demand has collapsed because prices are too high!
Compared to October in prior years:
- 2025: -14.5% (year-over-year)
- 2024: -16.7%
- 2019: -43.0%
- 2018: -40.4%
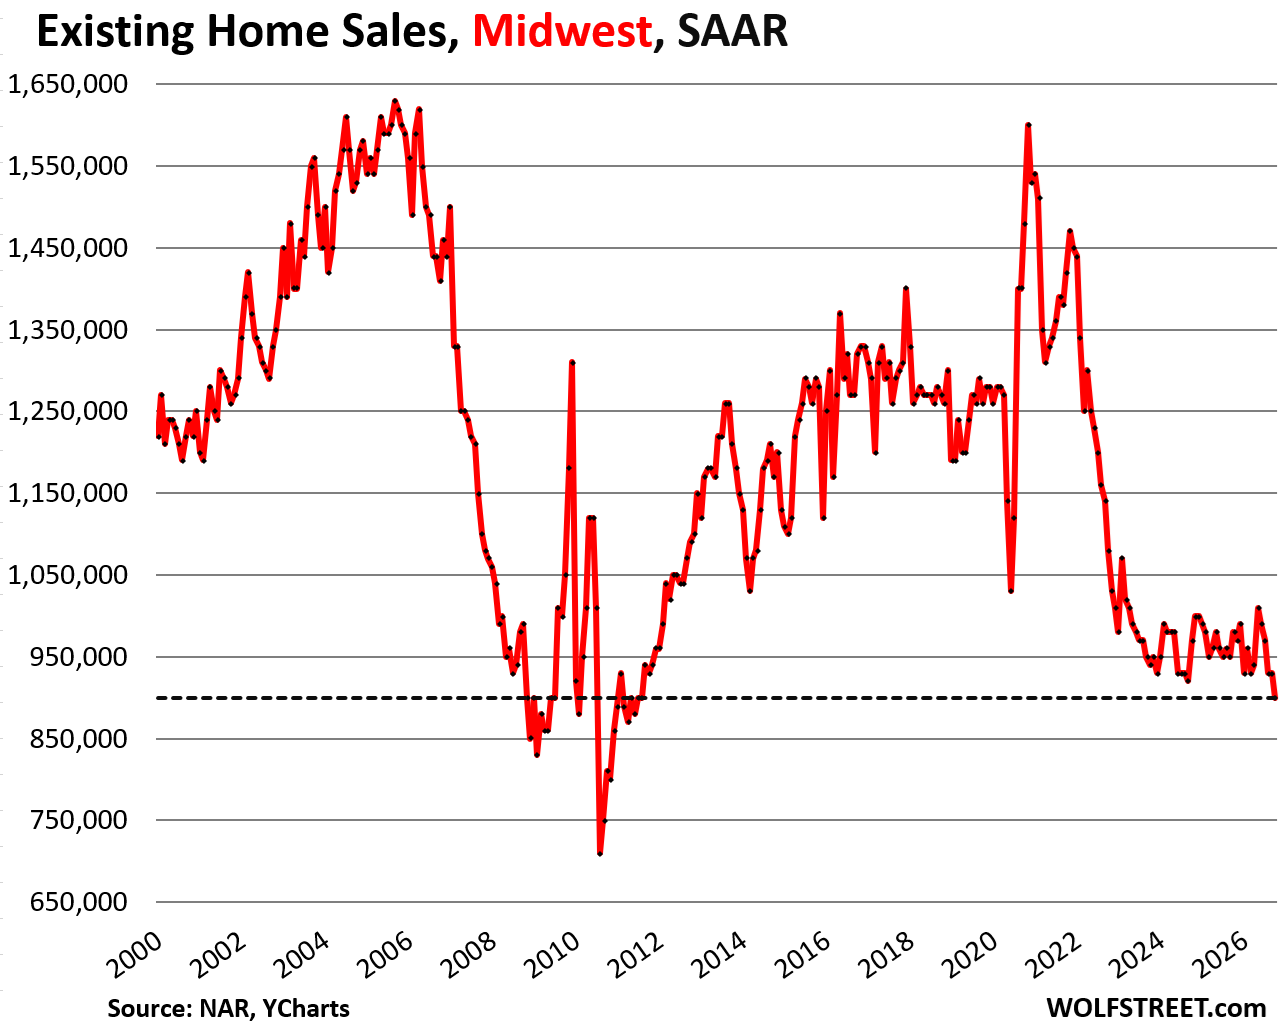
In the Midwest, the seasonally adjusted annual rate of sales dropped by 3.2% month-to-month and by 8.2% year-over-year, to 900,000 homes, the lowest since 2011.
Compared to September in prior years:
- 2025: -8.2% (year-over-year)
- 2024: -7.2%
- 2019: -28.6%
- 2018: -29.1%
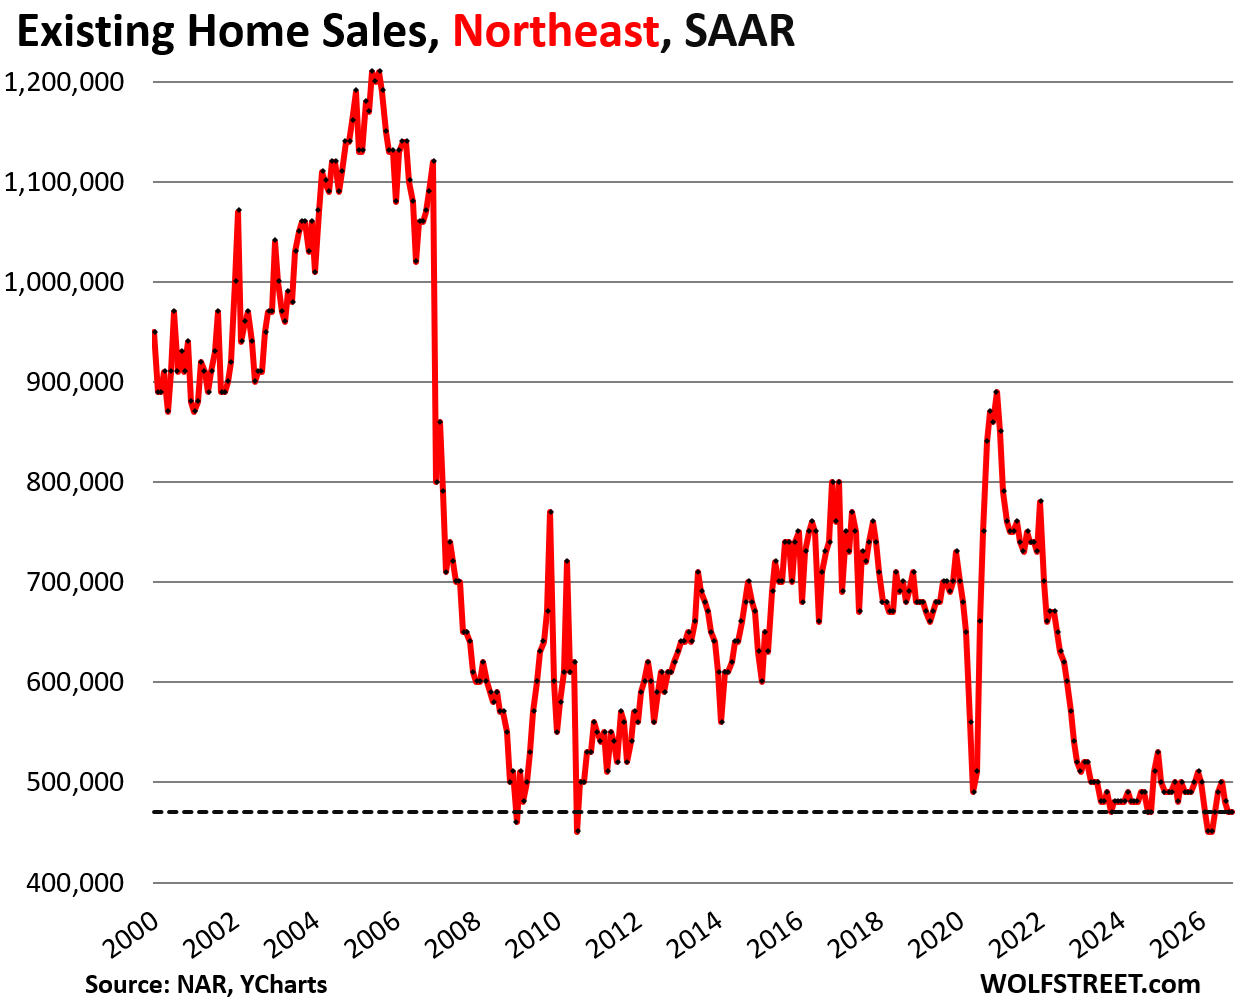
In the Northeast, the seasonally adjusted annual rate of sales was unchanged month-to-month at 470,000 homes, with only a handful of months in the data lower than that.
Compared to October in prior years:
- 2025: -4.1% (year-over-year)
- 2024: 0%
- 2019: -31.9%
- 2018: -31.9%
The affordability crisis.
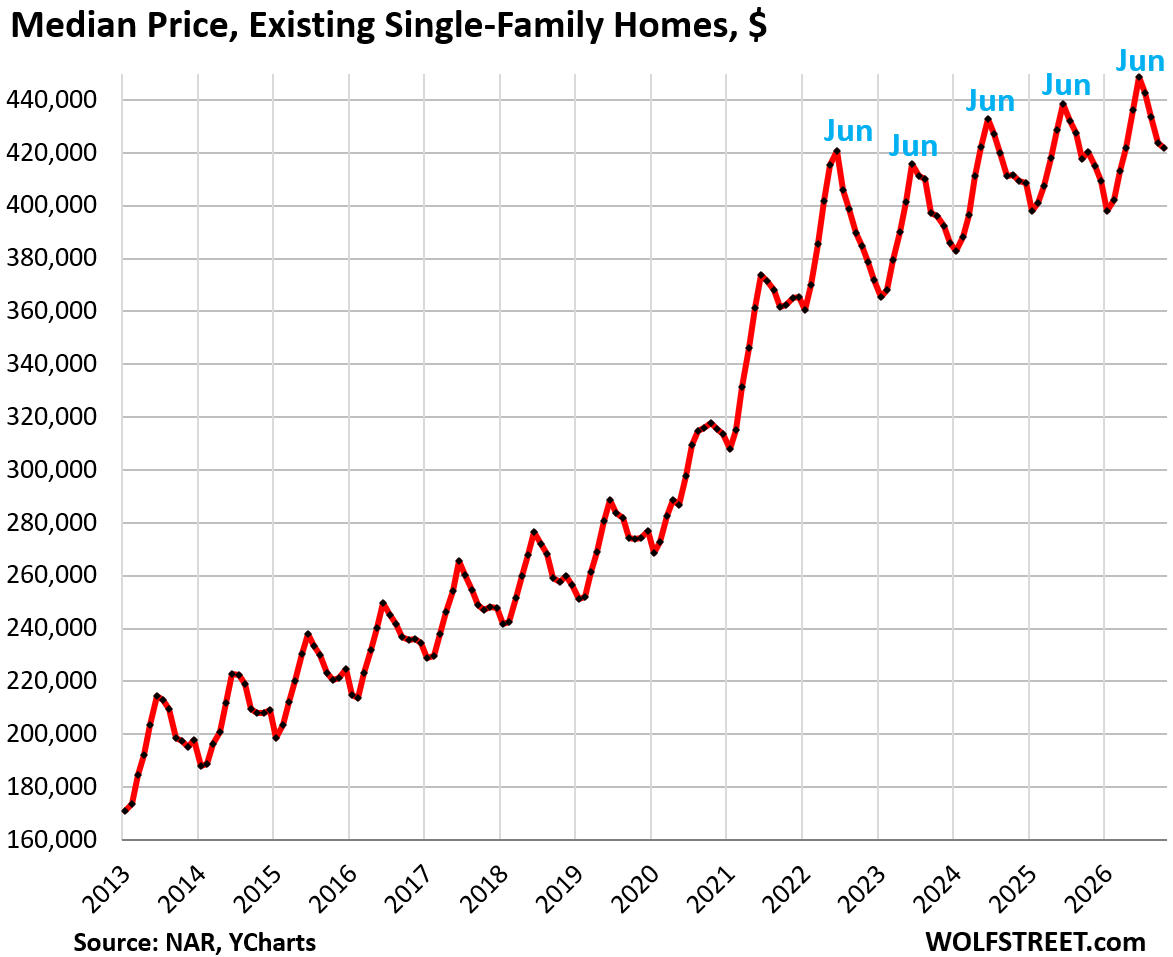
The national median price of single-family homes declined about in line with seasonal patterns to $421,900 in October, not seasonally adjusted. Year-over-year, it was up by just 0.4%.
The “affordability crisis” at the national level, triggering the current plunge in demand, was caused by the price explosion in the two years through mid-2022. The national median price had exploded by 40% in the two years from mid-2020 through mid-2022, on top of already high prices.
Wage increases reduce the affordability crisis. Since October 2022, over those four years, the national median price of single-family homes has increased by 9.7%, while average hourly earnings have increased by 18.0%, thereby easing slowly, over many years, the affordability crisis.
Local prices differ dramatically. The national median price is the “price in the middle.” It’s the price of one home that sold that month whose price was in the middle of all prices of all homes that sold that month. Only one buyer paid that price.
So for people buying or selling a home in their market, the national median price is irrelevant. What matters are prices in their local markets.
In some of those markets, the affordability crisis has lessened substantially through the combination of rising wages and sharply falling home prices.
Prices of single-family homes in (see our report on prices of single-family homes):
- Austin, TX: -26%
- Oakland, CA: -23%
- New Orleans, LA: -20%
- Lee County (Cape Coral, Fort Myers), FL: -18%
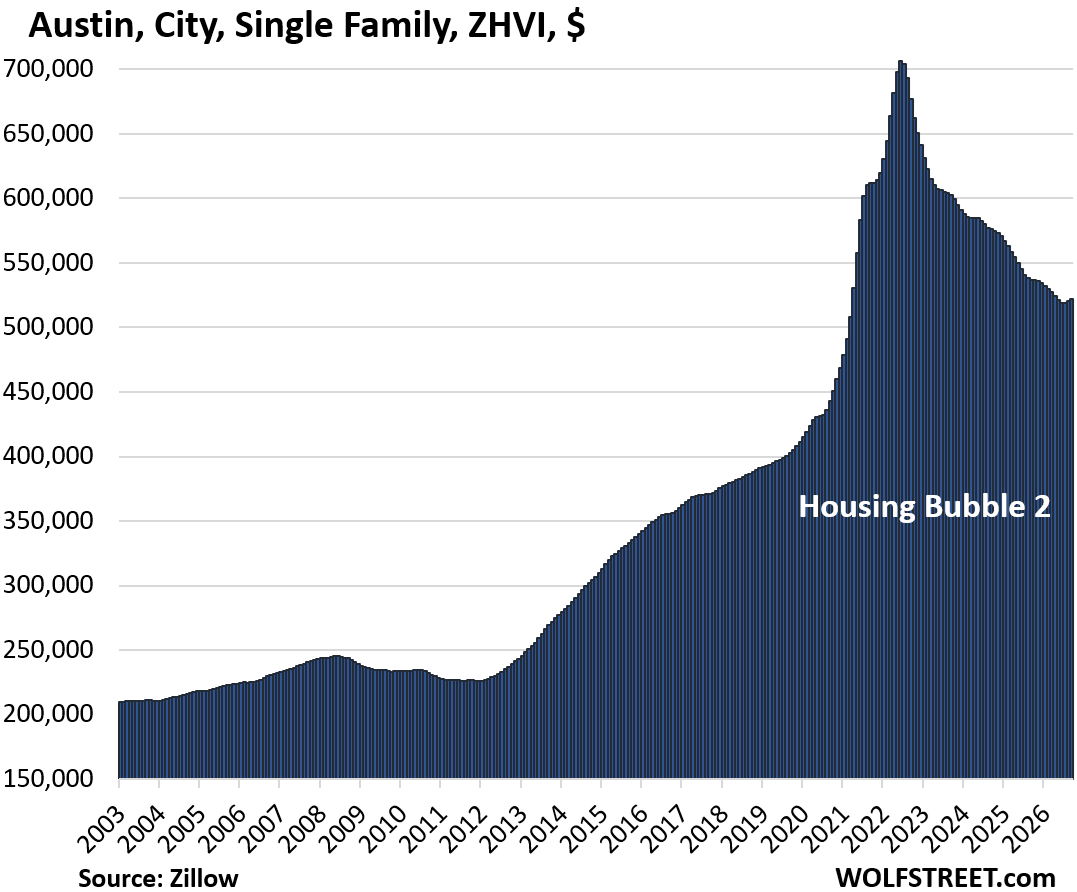
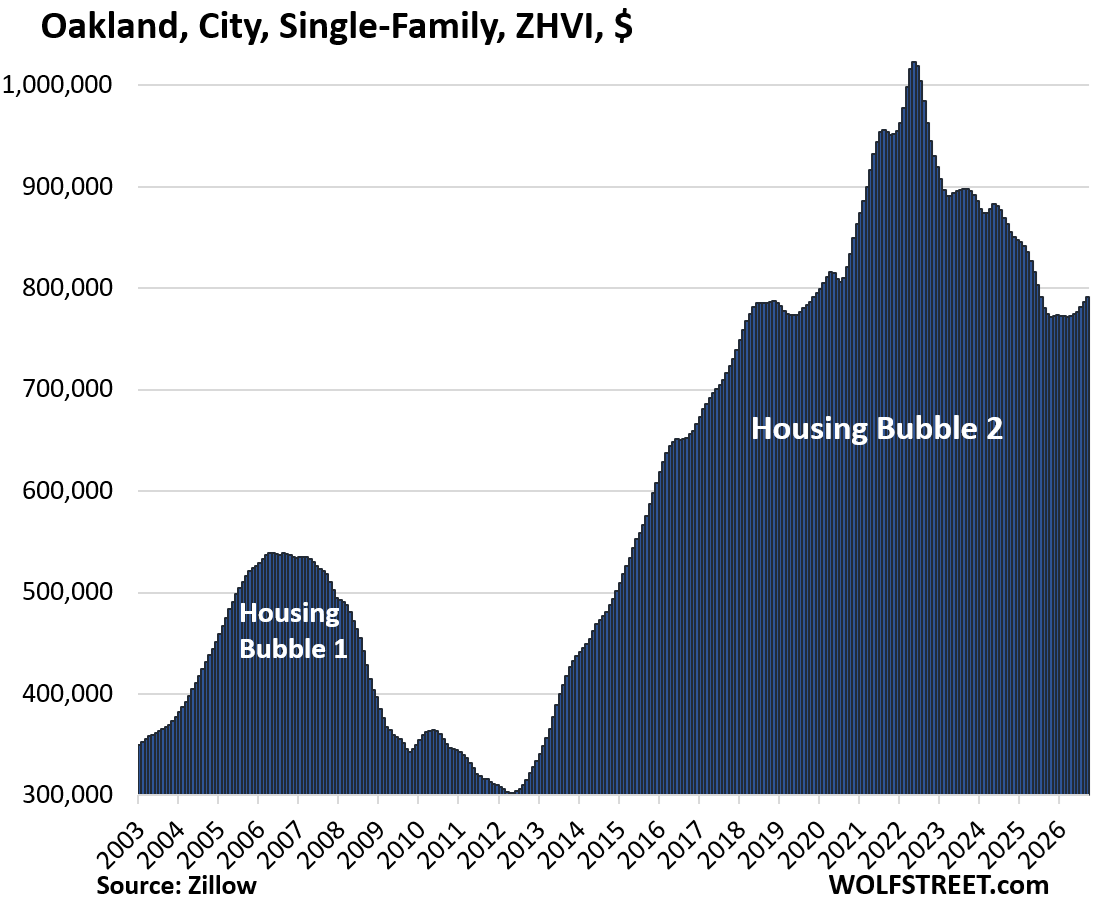
But in some other cities, prices of single-family homes have continued to rise to new highs and have further aggravated the affordability crisis.
The biggest cities with new highs and the biggest year-over-year gains:
- Chicago: +6.1%
- Toledo: +5.6%
- Rochester: +4.7%
- New York City: +4.5%.
The national median price of condos and co-ops ticked up month-to-month to $365,000 in October, roughly in line with seasonality. Year-over-year, prices inched up by 0.3%.
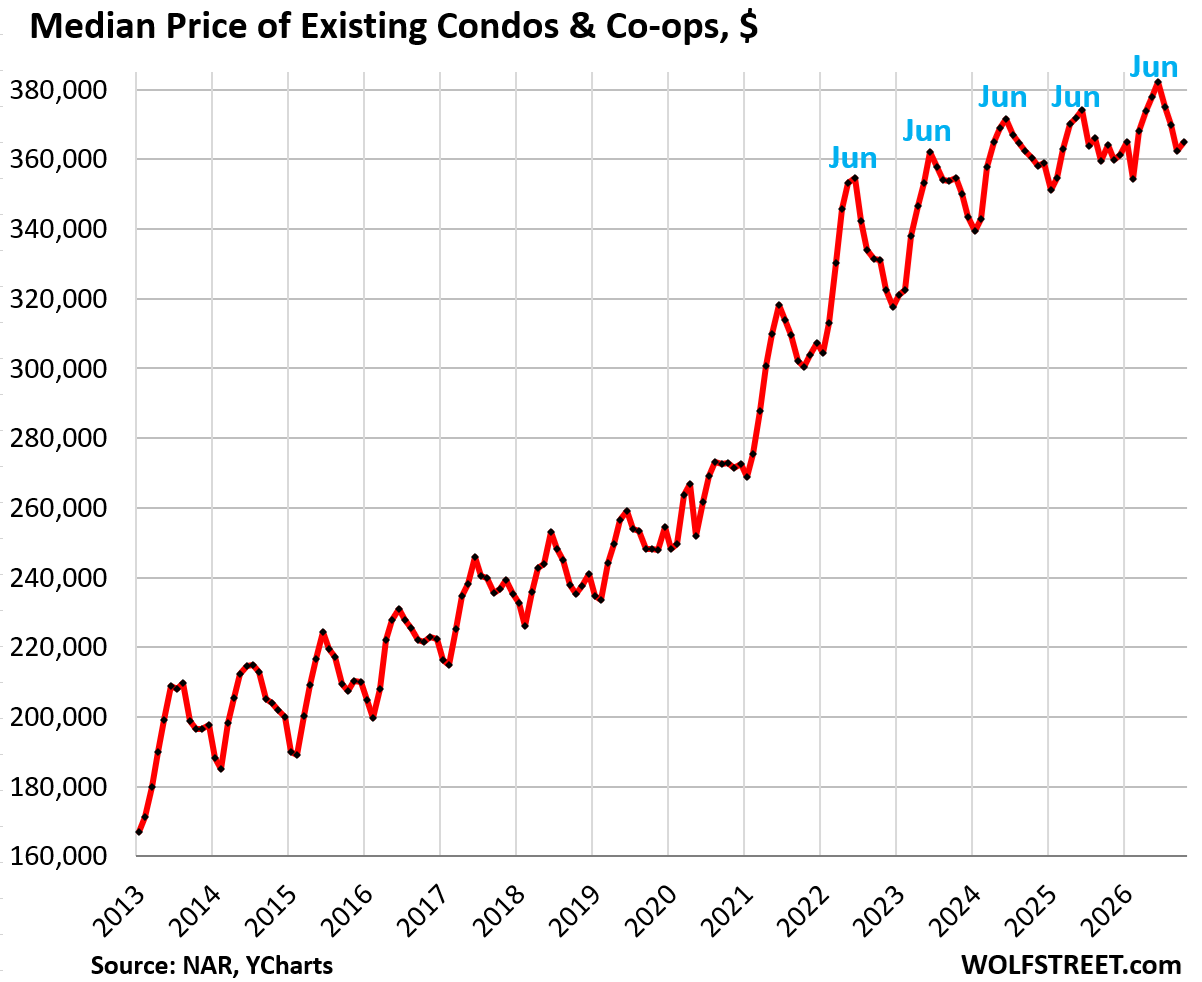
But the national median condo price is irrelevant for condo buyers and sellers anywhere. In many specific markets, condo prices have plunged, and in those markets the affordability crisis has lessened quite a bit. In some of those cities, condo prices have fallen below their highs in 2006 (see our report: Oh Dear, Condo Prices Dropped by 15% to 34% in 34 Bigger Markets).
- Cape Coral, FL: -34%
- Oakland, CA: -32%
- Petersburg, Fl: -30%
- Austin, TX: -28%
- Fort Myers, FL: -27%
- Sarasota County, FL: -24%
- Garland, TX: -22%
- Tampa, FL: -22%.
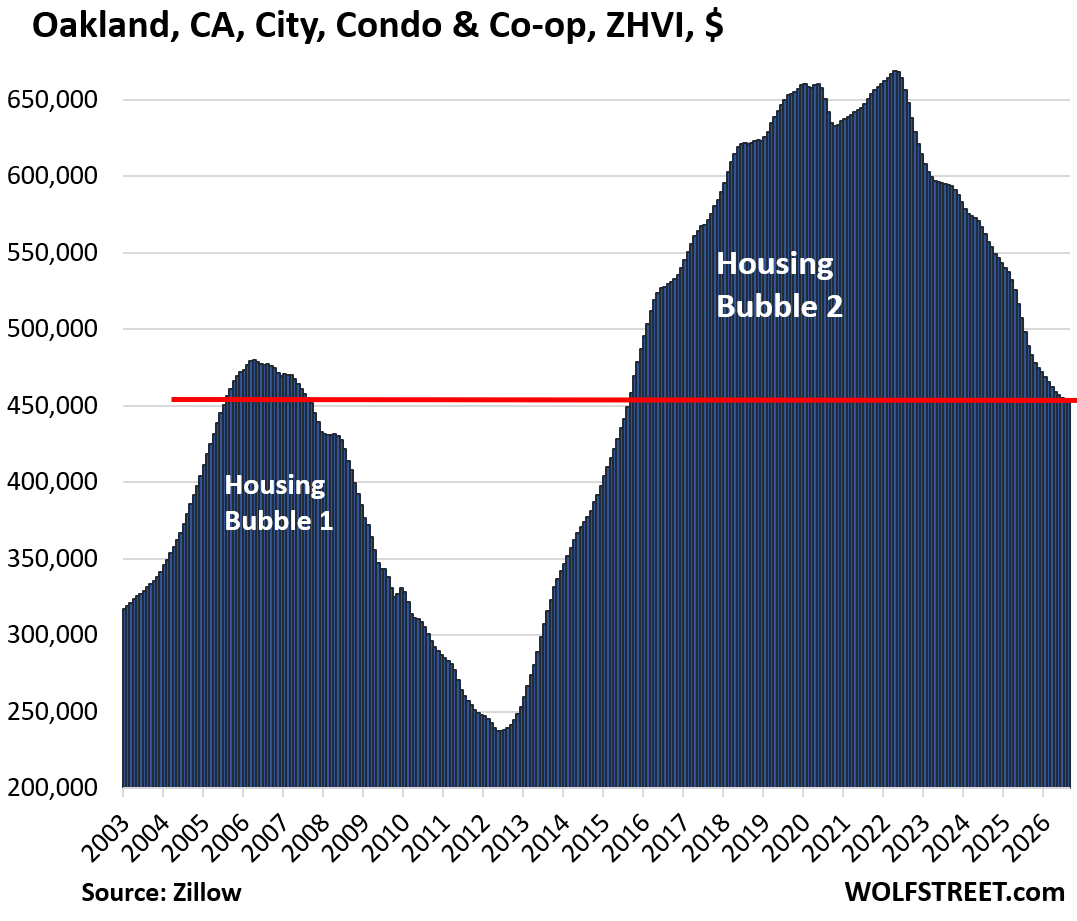
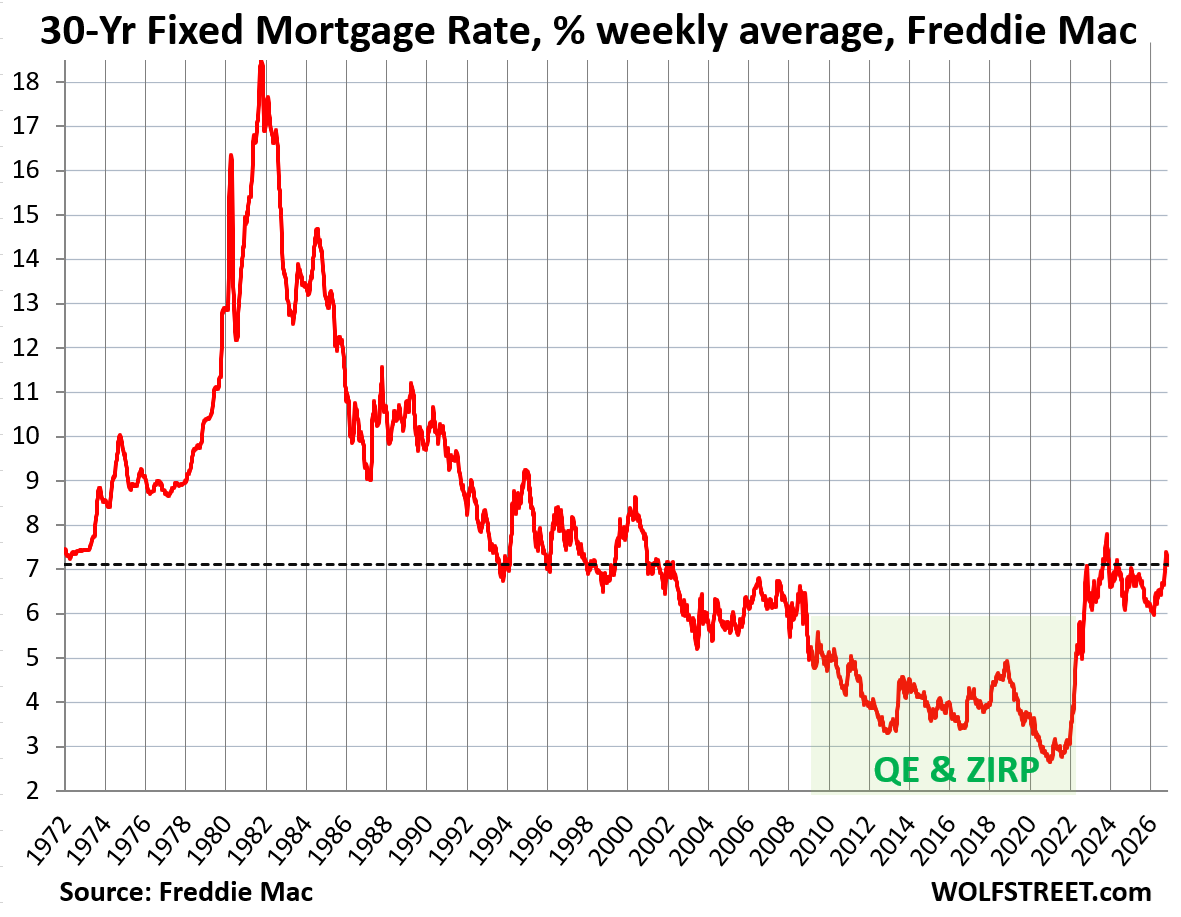
Mortgage rates were not high historically.
In August through October, when the deals were made that became closed sales by the end of October, mortgage rates were between 6.6% and 7.4%, per Freddie Mac’s weekly measure.
The weekly average 30-year fixed mortgage rate as of today for the past week, dipped to 7.11%, per Freddie Mac today.
But the daily measure of the 30-year fixed mortgage rate is already back to 7.42% today, after the spike in Treasury yields this week following the hot CPI report, according to the daily measure by Mortgage News Daily.
In the five-decade historical context, mortgage rates are not high. But home prices exploded between mid-2020 and mid-2022 and are now too high for the market to bear, and that price explosion is the root cause of the affordability crisis. That price explosion came about because the Fed had repressed long-term interest rates via purchases of trillions of dollars of Treasury securities and mortgage-backed securities through mid-2022, which repressed mortgage rates below 3% even as inflation was heading to 9%. Better than free money, and when money was free, prices didn’t matter, and buyers bid them up.
In case you missed it: The Growth of the Vacant Housing Stock in the US
Enjoy reading WOLF STREET and want to support it? You can donate. I appreciate it immensely. Click on the mug to find out how: