But opaque foreign financial centers pile on Treasuries, often held by US companies and hedge funds.
By Wolf Richter for WOLF STREET.
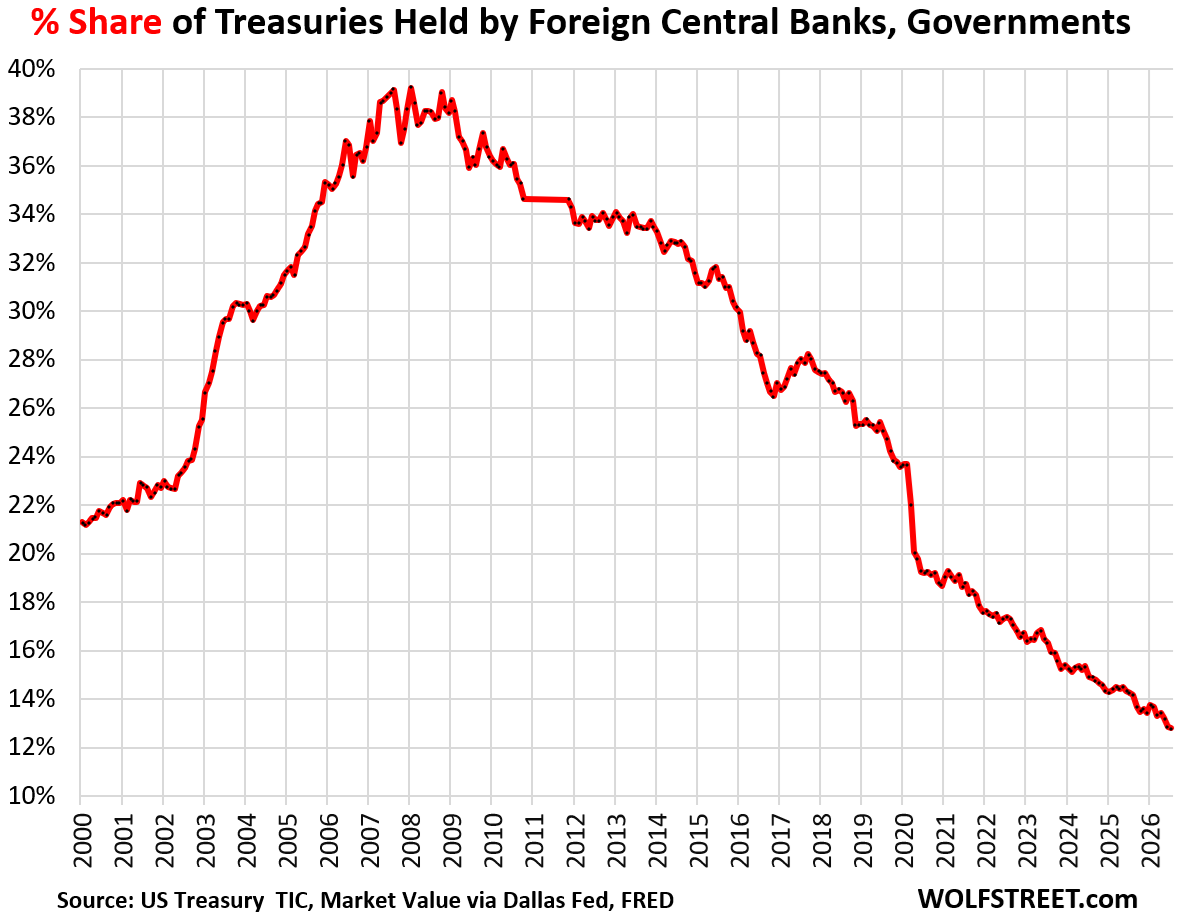
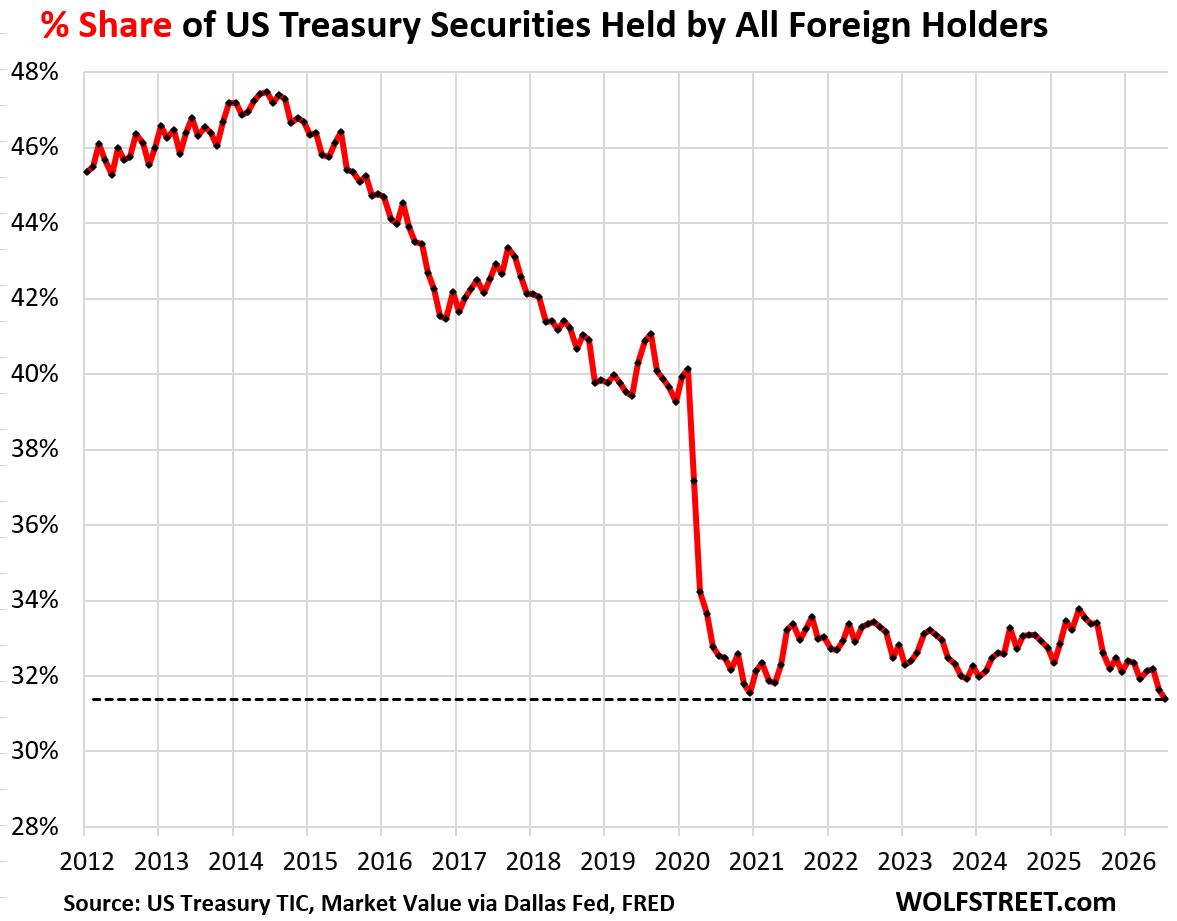
Treasury securities have lost their allure for foreign central banks and governments, whose holdings declined this year and in July dropped to $3.77 trillion at market value, roughly where they’d been in 2012, according to the Treasury Department’s TIC data.
But over this period, since 2012, the amount of Treasury securities outstanding has about tripled, according to the Dallas Fed market-value data (via St. Louis Fed). And inflation since 2012 was 48%. And the share of these “foreign official” holdings has collapsed from a share of 34% of marketable Treasury securities in 2012, and from a share of over 38% at the peak in 2007-2009, to a share of 12.8% in July, the lowest share since 1993.
There are three aspects to this:
- Treasury securities have become increasingly unappetizing for foreign central banks and governments.
- The US has become a lot less dependent on foreign central banks and governments to finance its massive out-of-control deficits.
- The US has become more dependent on opaque foreign financial centers, where US hedge funds and companies keep their holdings.
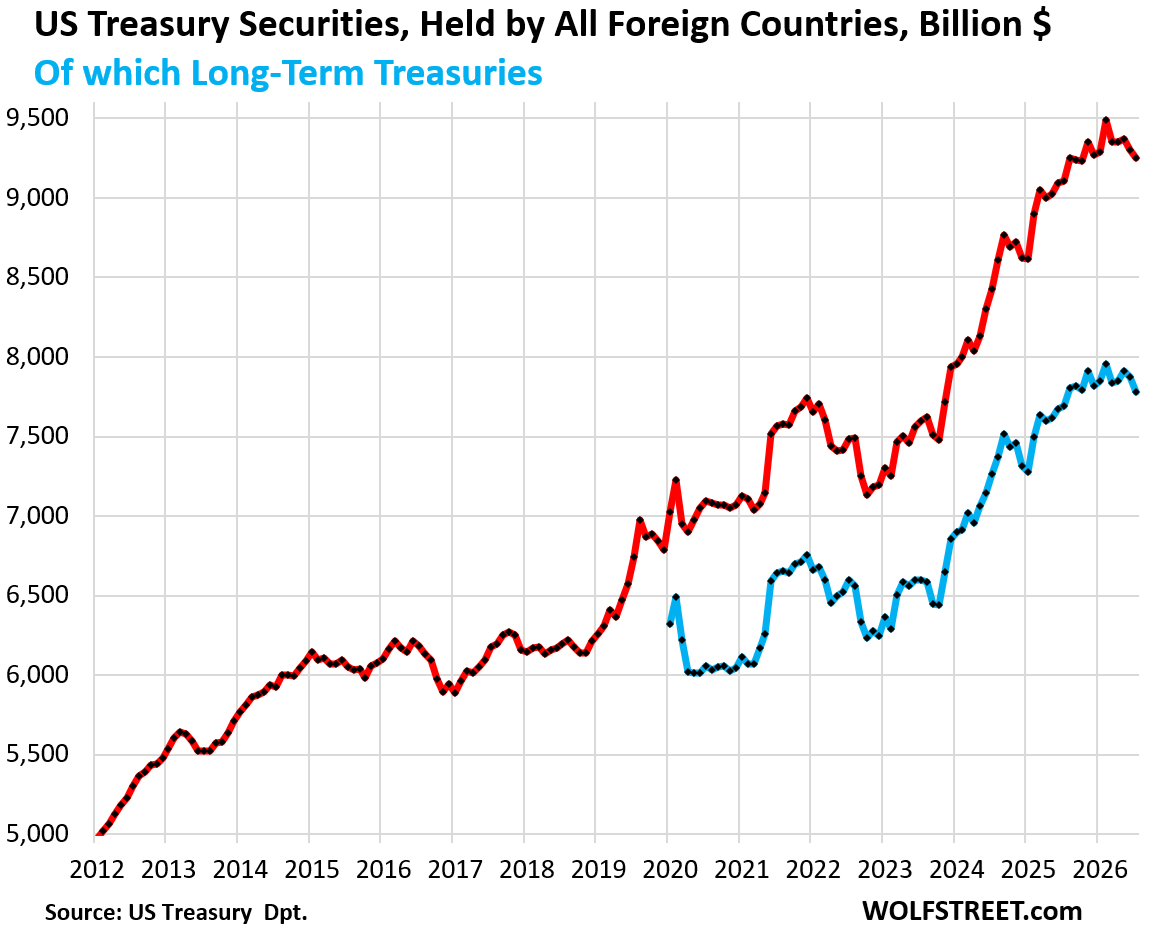
Foreign holders in total – foreign official holders and foreign private holders – shed $50 billion of Treasury securities in July, bringing their holdings down to $9.25 trillion (red in the chart below). Those total holdings kept zigzagging higher over the years and reached a peak in February, driven by private foreign holdings.
Long-term Treasury notes and bonds accounted for $7.78 trillion, or about 84%, of the total foreign holdings (blue line). The rest were short-term Treasury bills.
But these private foreign holdings are not purely “foreign.” They include large amounts from US hedge funds that are domiciled in foreign financial centers, such as the Cayman Islands, a big favorite for hedge funds engaged in the highly leveraged Treasury basis trade that buy Treasuries, estimated at close to $2 trillion, and sell Treasury futures against them. This is the hot money in Treasuries, and back in March 2020, it caused the Treasury market to seize, an event that the Fed keeps nervously talking about. Only now, it’s a lot bigger.
And they include holdings by US companies that have entities in Ireland and elsewhere where they keep their foreign profits, instead of repatriating them to the US and paying income taxes on them in the US. Apple became a poster boy of that during a Senate investigation in 2013. US Big Pharma has set up in Ireland for these reasons. And those Treasuries are included in “foreign private” holdings because the entities that hold them are registered in foreign countries.
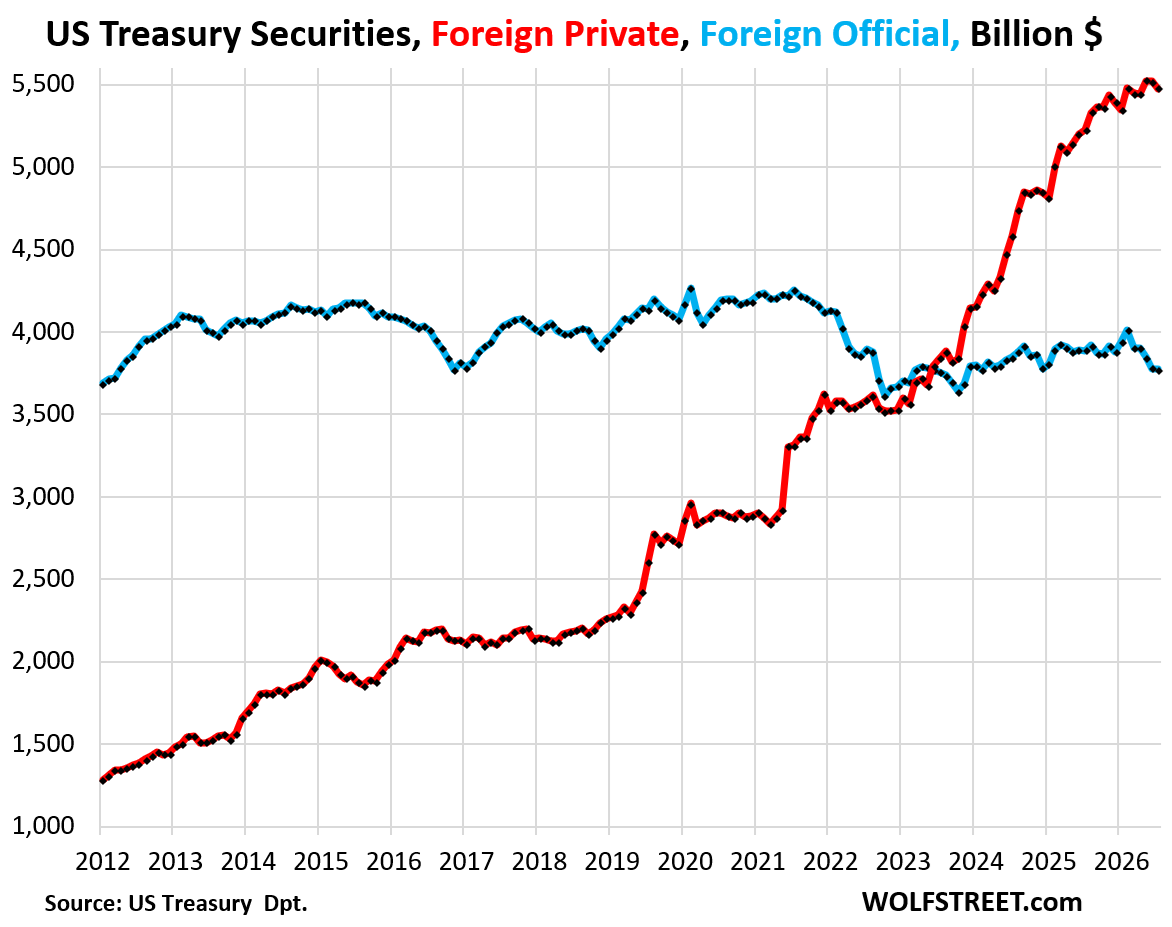
But their share of marketable Treasury securities outstanding declined to a near-record low in July of 31.9%, roughly matching three months in 2020, when the US government had issued about $3 trillion in new debt in three months, and the Fed had bought $3 trillion in three months.
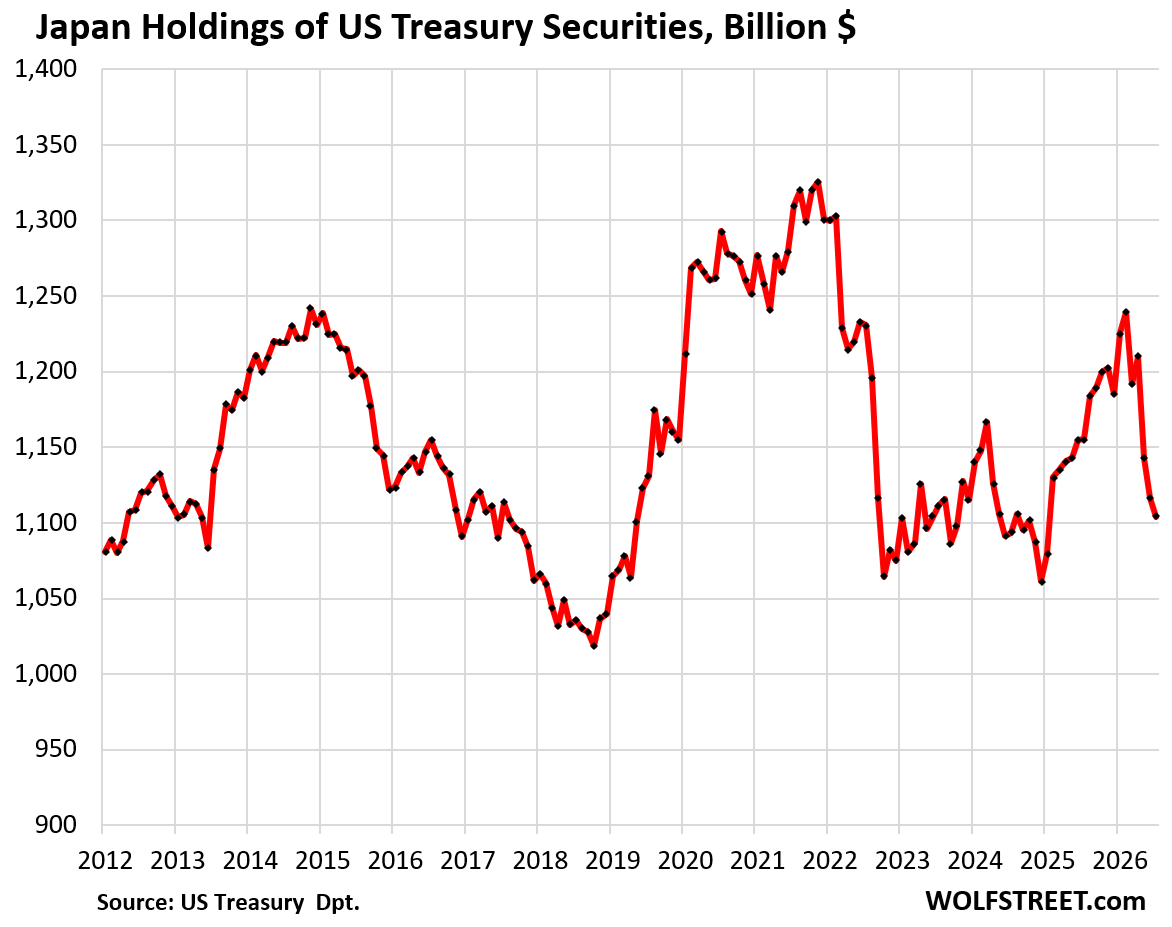
Japan dumped Treasury holdings, shedding $13 billion in July. From February through July, Japan reduced its Treasury holdings by $135 billion.
Japan is trying to put a floor under the collapsing yen and had engaged in multiple rounds of currency market interventions, selling dollars and buying yen. It sold Treasury securities in advance of the intervention to obtain the dollars and to sell them in the currency market and buy yen.
These sales are hugely profitable in yen-terms for the Japanese government since it purchased the securities with much stronger yen years ago, and now gets many more yen from the proceeds due to the yen’s plunge against the dollar. As many of the sold securities were close to their maturity dates, and therefore brought close to face value, the losses in dollar terms due to higher yields were minimal. There are public discussions underway in Japan about what to do with these profits from the Treasury trade. Spend them is part of the answer. Don’t cry for Japan.
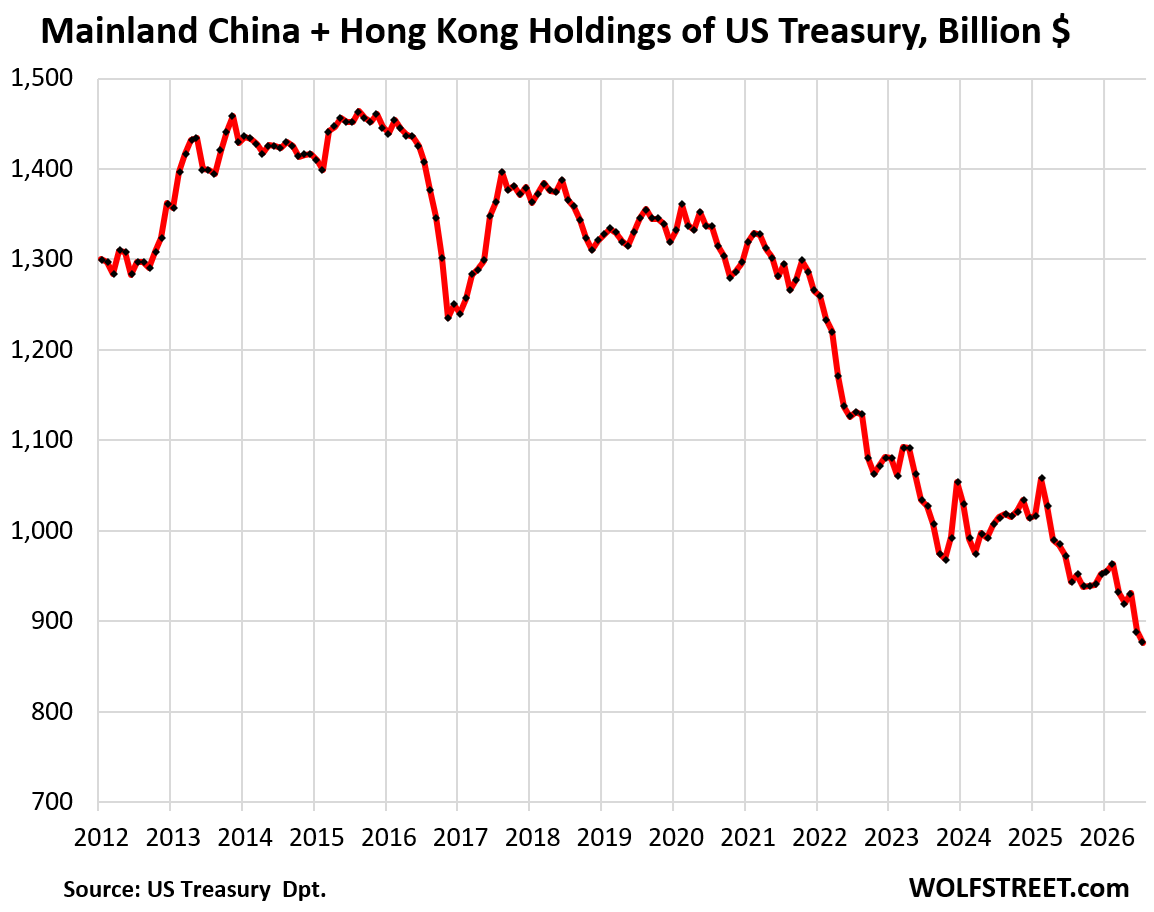
Mainland China and Hong Kong combined have been relentlessly dumping their Treasury holdings since 2015, and that continued in July, when they shed $13 billion, bringing the 12-month total reduction to $67 billion.
Since the peak in 2015, they have shed $587 billion. And their share has dropped to an inconsequential 3.0% of the marketable Treasury securities outstanding.
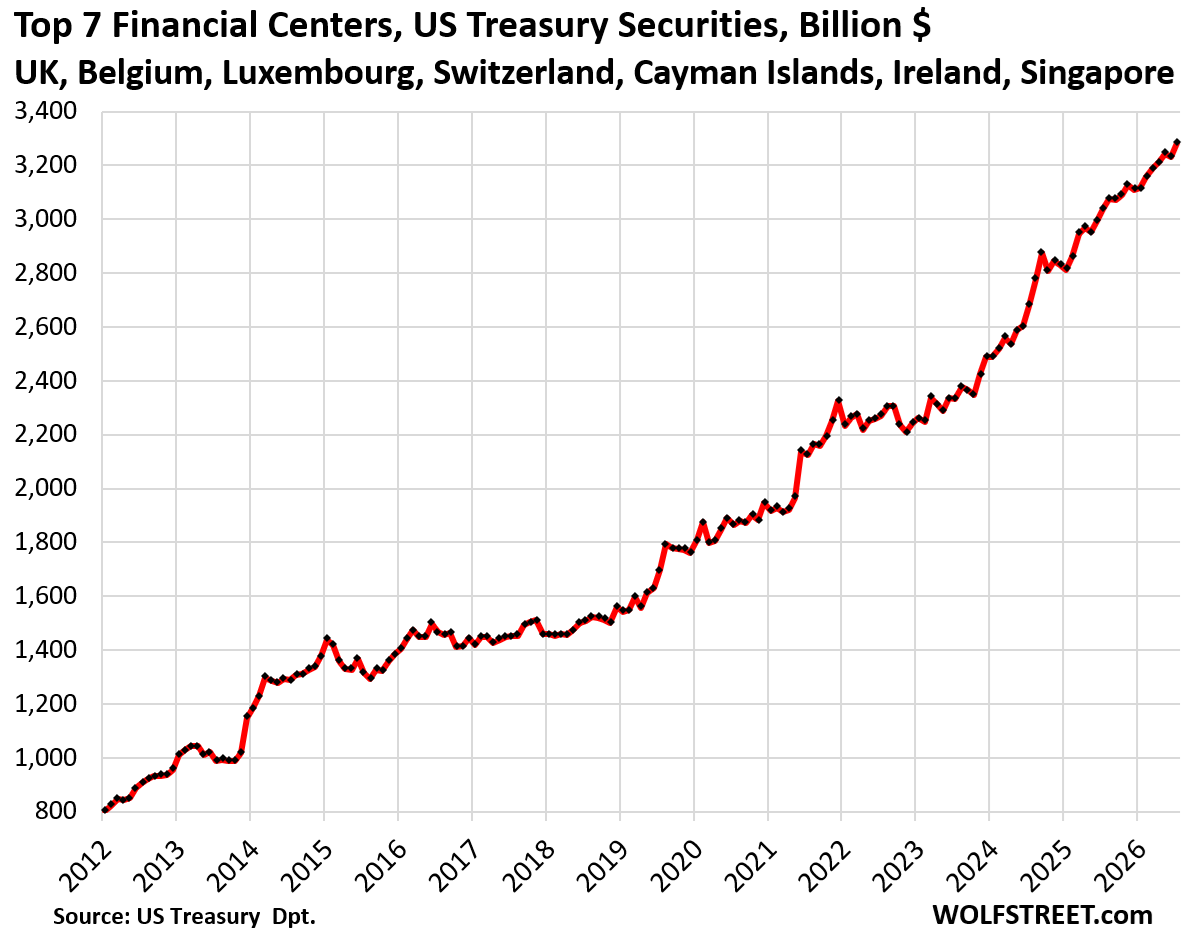
Opaque financial centers rule. Treasury holdings in the seven largest financial centers combined rose to $3.28 trillion. Those seven account for about 11% of all marketable Treasury securities outstanding, and about 35% of all foreign holdings!
In order of the magnitude of their holdings:
- United Kingdom ($1.0 trillion), actually the City of London, the largest financial center in the world;
- Belgium ($471 billion), home of Euroclear;
- Cayman Islands ($460 billion) where US hedge funds are domiciled;
- Luxembourg ($442 billion);
- Ireland ($350 billion);
- Switzerland ($285 billion);
- Singapore ($278 billion).
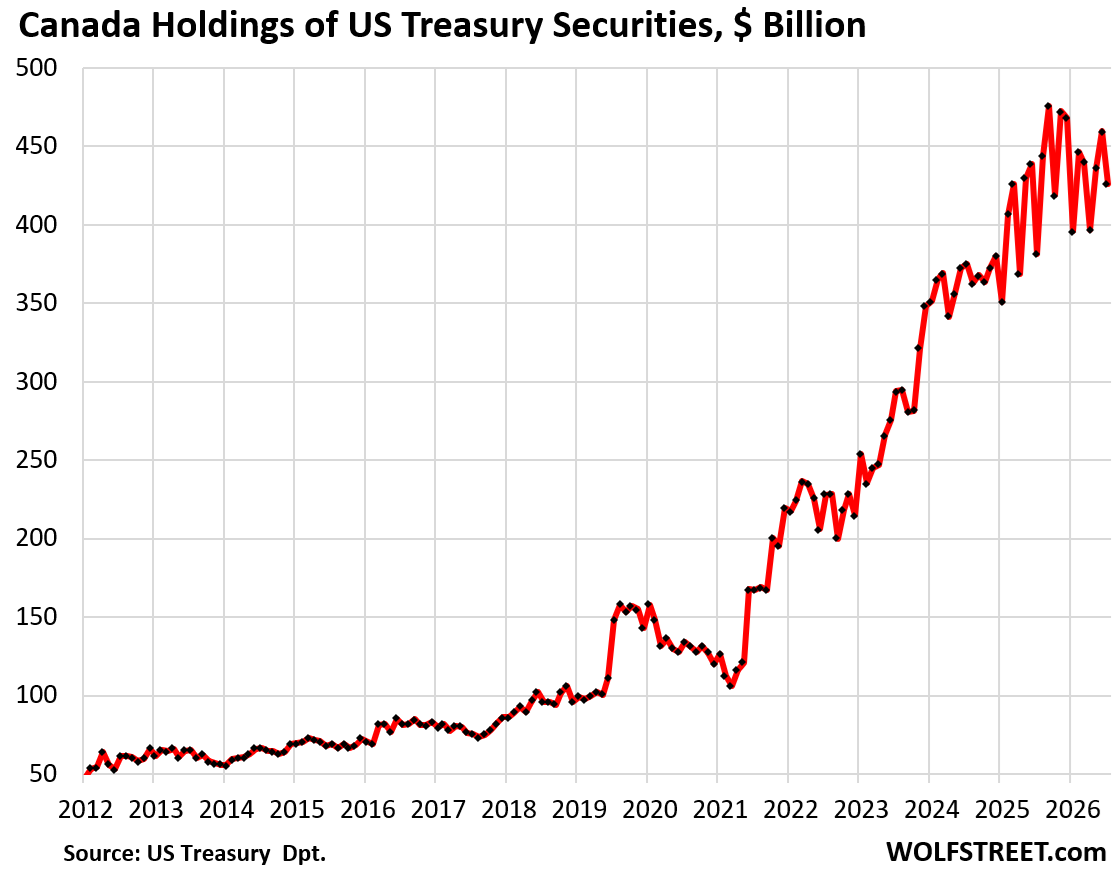
Canada’s Treasury yoyo: In July, its holdings plunged by $33 billion to $426 billion, undoing more than the spike in the prior month. The high was in September 2025 ($476 billion).
The recent massive yoyo makes me think that we’re looking at data collection noise, and not at some investment choices Canadians are making.
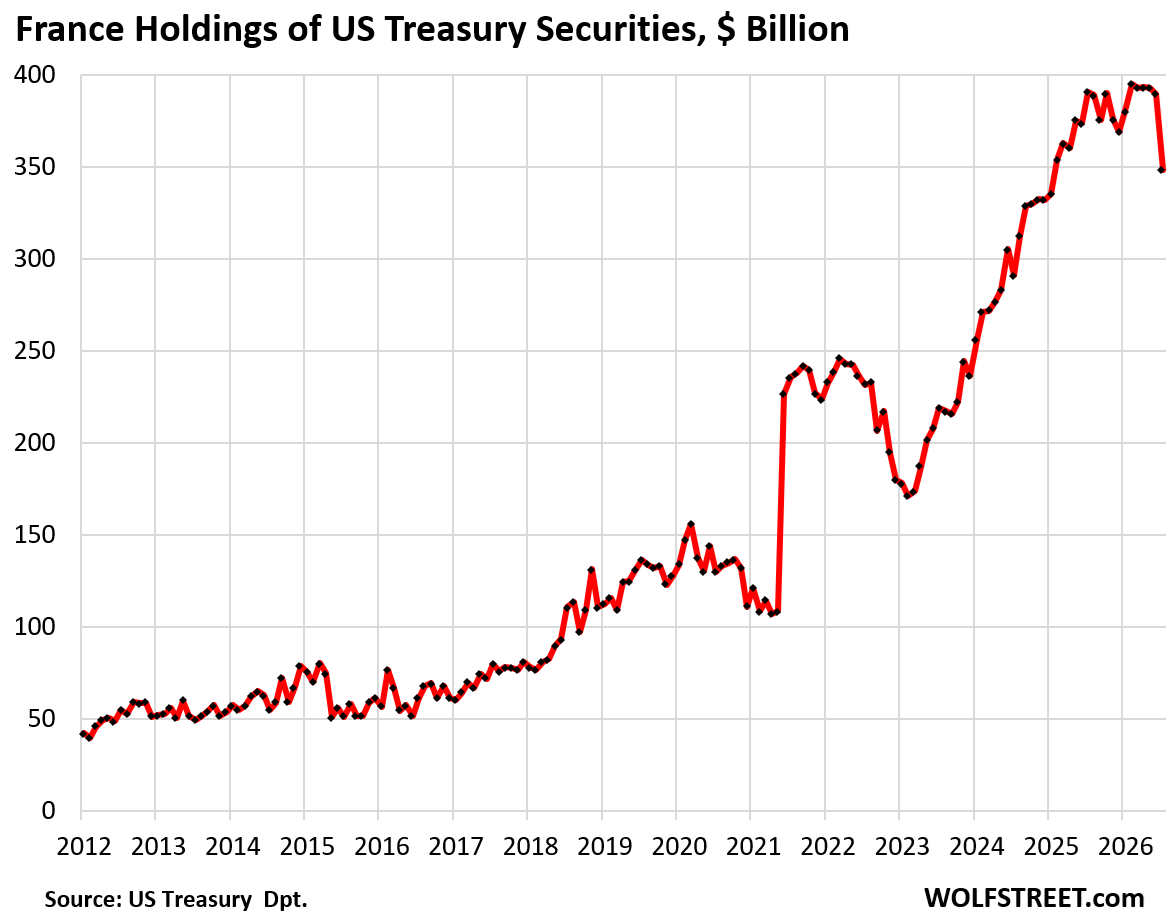
France’s holdings plunged in July by $42 billion from record levels, to $348 billion. The French banking system also has characteristics of financial centers.
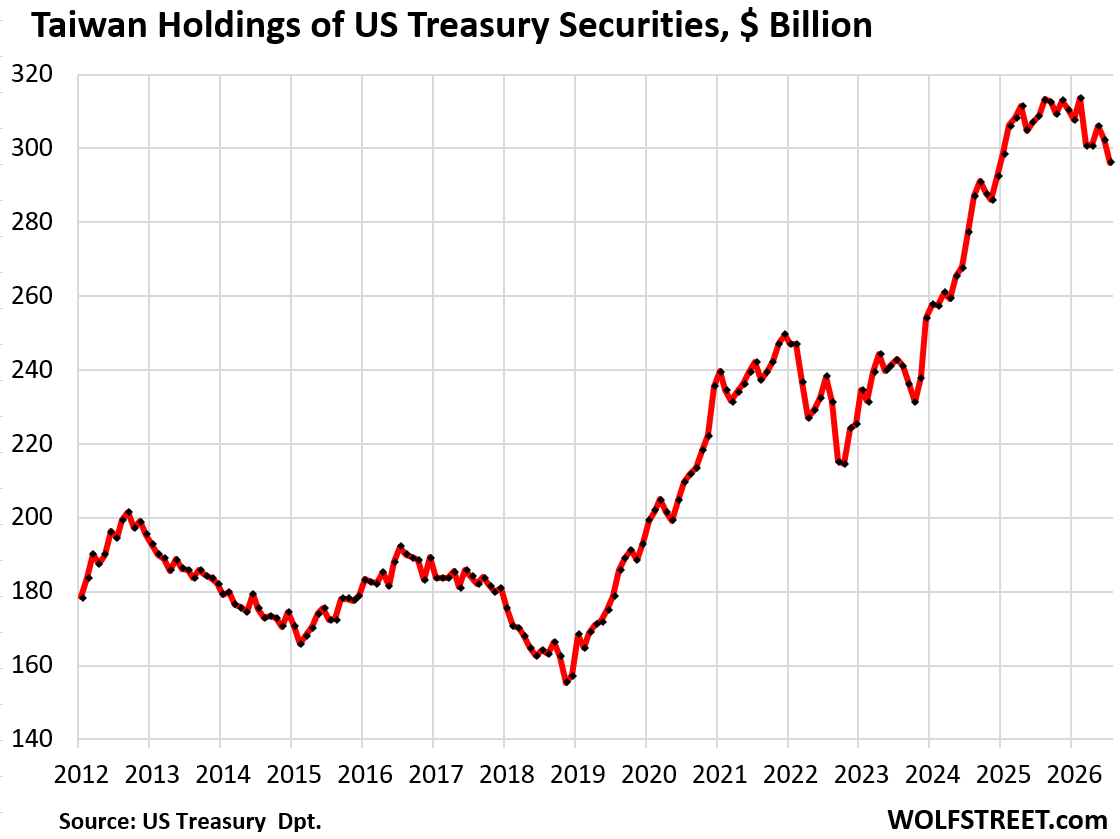
Taiwan’s holdings fell by $6 billion in July, to $296 billion:
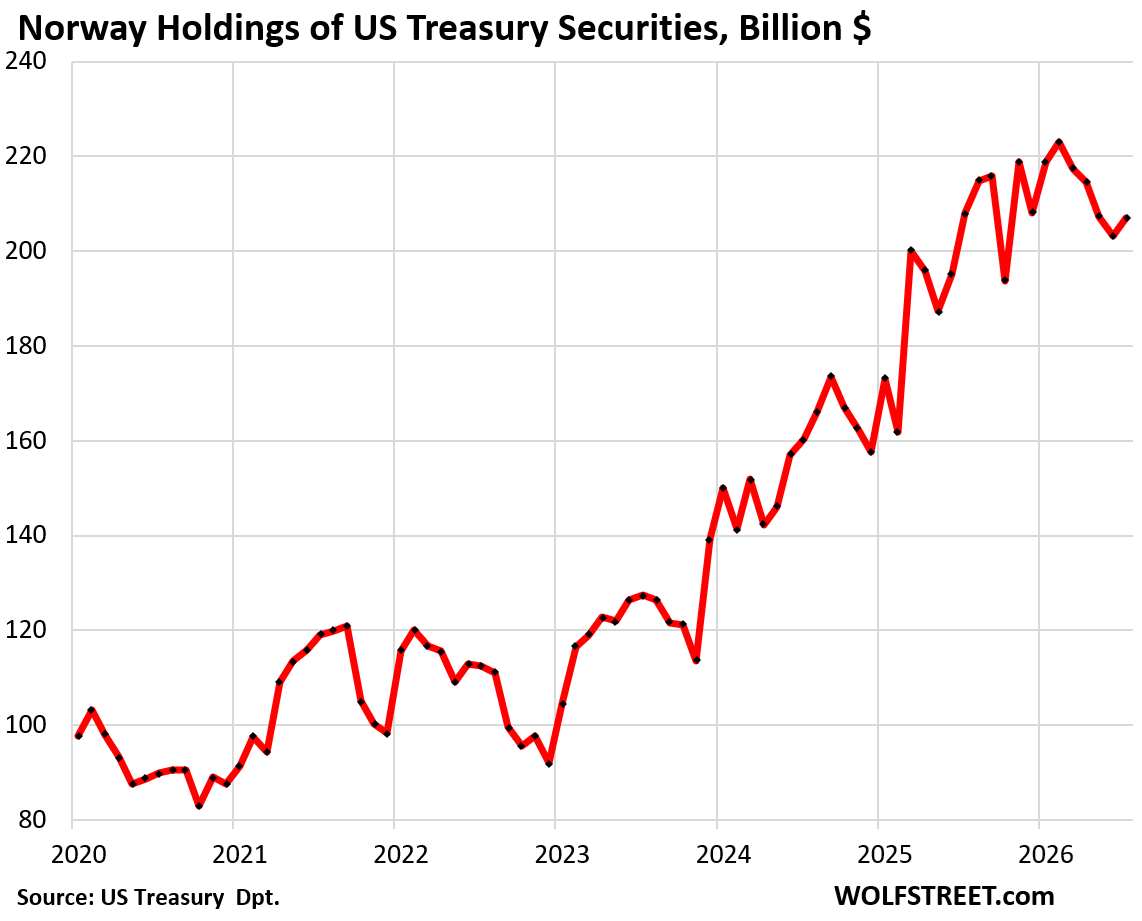
Norway’s holdings rose by $4 billion in July, to $207 billion, after four months of declines, and was essentially unchanged from a year ago.
The tiny country is home to the world’s largest sovereign wealth fund, the Government Pension Fund Global, also known as the Oil Fund, which has $2.3 trillion in assets under management, including Treasuries.
The fund manager has now proposed to reduce its bond holdings in general, and most of the reductions would hit its Treasury holdings, which could be cut by about $80 billion. So we’ll see if that happens.
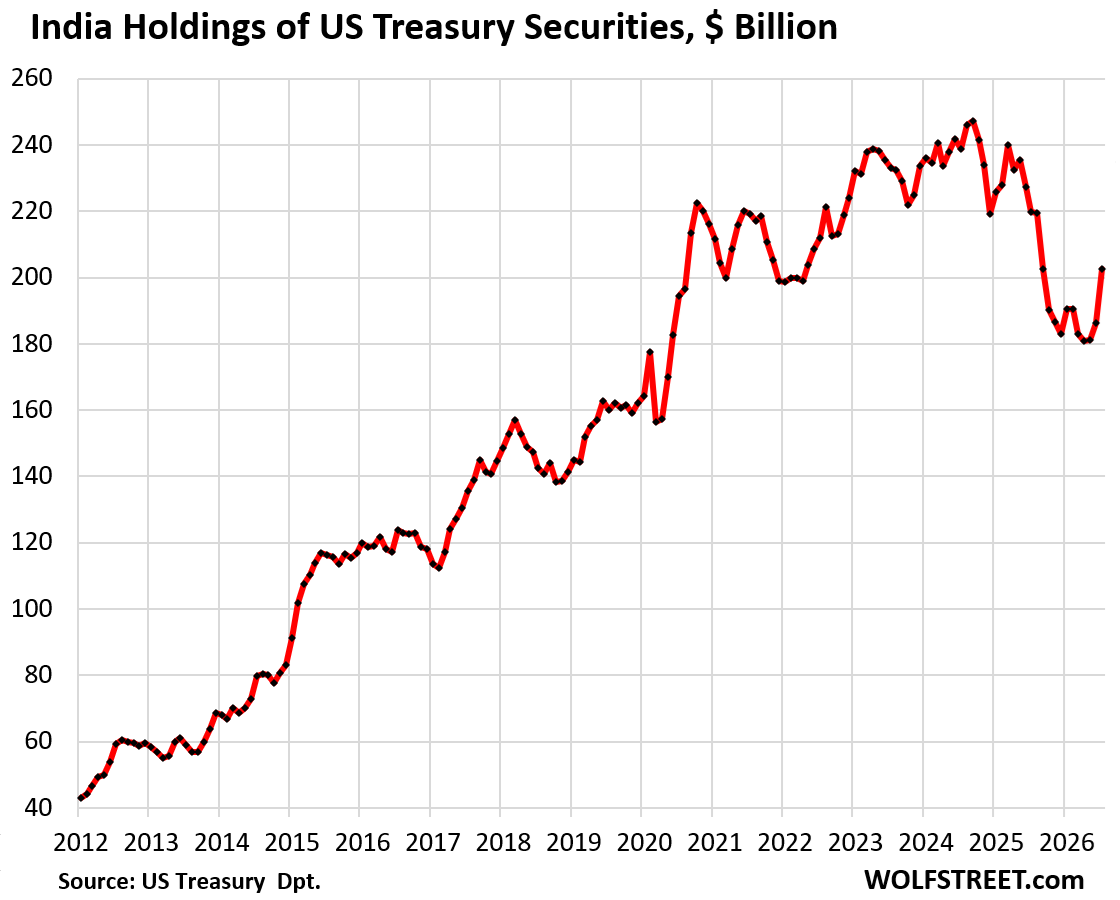
India’s holdings jumped by $16 billion in July, to $203 billion, but still down by $17 billion year-over-year.
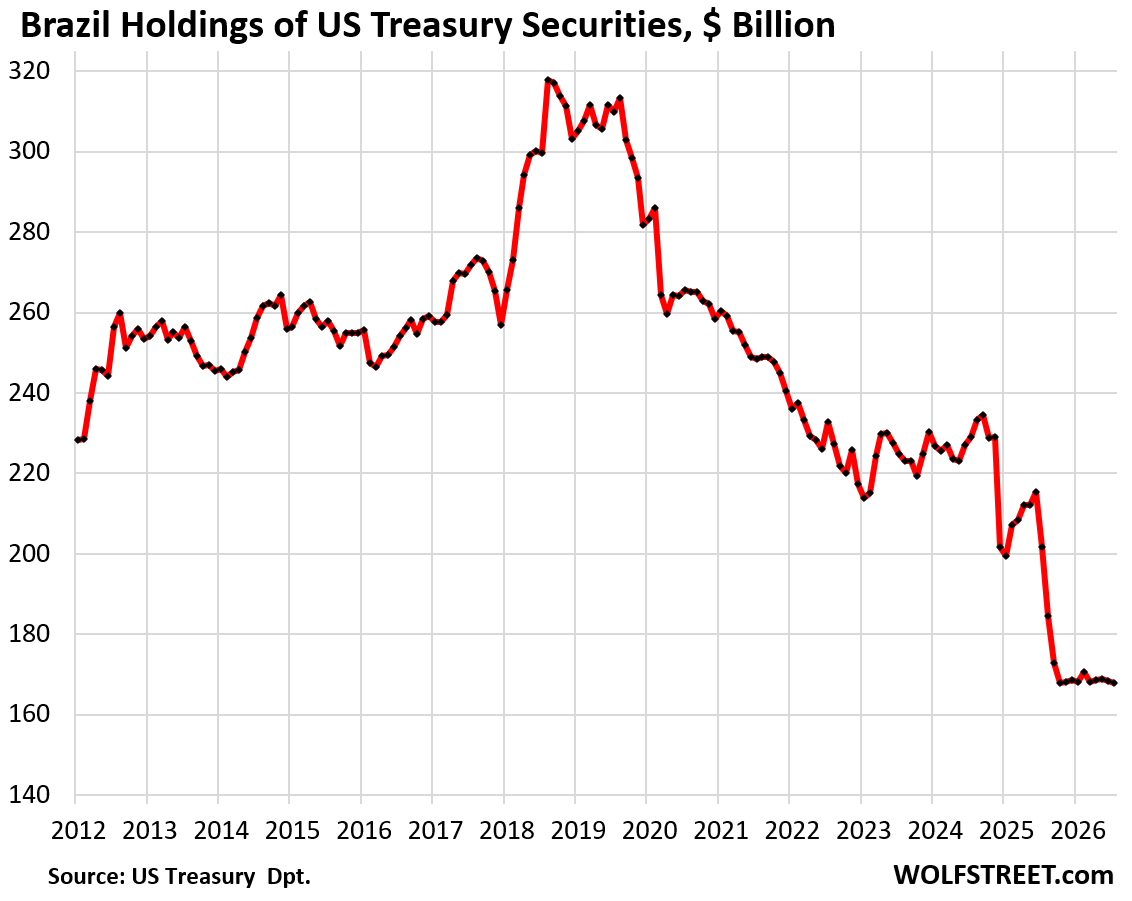
Brazil’s holdings have been roughly unchanged since October last year, at $168 billion in July, down by 46% from the peak in 2018.
Enjoy reading WOLF STREET and want to support it? You can donate. I appreciate it immensely. Click on the mug to find out how:

Real interest rates have declined making holding Treasuries less appealing.
I was in my previous company’s stock program. I got a discount for a certain percentage of their stocks that I bought.
In the last year the stock is down -49.86%. The stock ticker is PNR.
Is this happening because foreign central banks are losing confidence in the us debt situation because they are concerned that the the “let it run hot” plan is to risky for them? Are they concerned that the risk of inflation is going to eat away at any possible financial gain? Treasuries are short-term, so long term inflation isn’t really a problem, right?
Or is it because these central banks are cashing in because it seams that we have entered into a bond bear market/they need the money like Japan and the private institution/others are willing to buy them?
Thanks for the detailed article. Your website has helped me have a much better understanding of how the financial world works!
Bank of America’s Unrealized Bond Losses Could Top $90 Billion on Surging Yields
I commented and asked, in past about balance sheets of central banks. for many central banks, Gold at current market values dwarfs their bond holdings. usa and italy are in the neighborhood of 70% when pricing gold to current market value. just an fyi and question, too. i enjoy your blog. you lay out complicated topics quite nicely. a tip of the hat.
“Gold at current market values dwarfs their bond holdings.”
1. central banks shouldn’t hold any long-term bonds in their own currency. Those bonds are leftover from QE and they should get rid of them through QT, and they’re doing some of that.
2. But central banks hold securities denominated in other currencies, such as USD denominated Treasuries (“foreign exchange reserves”), and those dwarf their gold holdings. From my article (scroll to the bottom to the gold chart):
https://wolfstreet.com/2026/03/28/status-of-us-dollar-as-global-reserve-currency-usd-share-drops-to-31-year-low-as-central-banks-diversify-into-other-currencies-gold/
“Official gold holdings at the end of 2025 would be valued at $5.27 trillion at today’s price, compared to $13.0 trillion in total foreign exchange reserves, and $7.46 trillion in USD-denominated foreign exchange reserves:“
thanks for info
Lol, I just found this. Barron’s been singing this tune for a while
Bank of America Bond Losses Could Top $100 Billion Due to Rising Rates
Barron’s
·
Jan 9, 2025 00:01
That’s been going on since 2022 and several regional banks have collapsed because of it in 2023.
Everyone who bought bonds in 2020 and 2021 sits on huge losses, but they can hold to maturity and have zero losses because they will get paid face value at maturity and collect small interest payments along the way, which is what banks are doing. That’s how long-term bond investors look at bonds. Traders look at bonds differently, they’re trying to capture movements.
“Everyone who bought bonds in 2020 and 2021 sits on huge losses,”
True.
But the very large risk of huge bond losses/freeze up (the slow “riding out” until maturity that Wolf discusses) is basically an inescapable part of using ZIRP for years/decades on end.
Debtor/borrower/speculator “free money” fantasies are lender/creditors/savers nightmares (and bayonet to the back prodding more risky behaviour).
If the Fed has strangled interest rates down to 3% (in the service of a 50 year demented Treasury) then when economically reality is allowed to reintroduce itself (increased rates reflecting the risk of a government with 40 trillion in debt, that hasn’t balanced a budget in half a century), it is mathematically inescapable that the holders of those ZIRP’ed assets are going to face huge losses…or have to freeze things up for a long time until the ZIRP assets mature.
That is one (of multiple) reasons that ZIRP is/always a terrible idea.
And when the assets mature they pay face value in dollars that have depreciated in purchasing power. That is the risk of holding to maturity. Sometimes it is better to take the loss now and invest in something else in the hope to compensate for the loss. When markets and sentiment move, you have to move along.
> “that hasn’t balanced a budget in half a century”
Quarter century.
Are those long term held-to-maturity holdings at banks still available to act a collateral at the FED’s repo facilities if liquidity needs arise.
I’m sure you have done articles on the mechanics of those facilities, but I cant remember the details. If the banks can get liquidity, then unrealized losses are unimportant to them or so I would think.
At the Fed’s Standing Repo Facility (SRF), the banks’ collateral (Treasuries) is valued at fair market value minus a “haircut.” That haircut varies; it is smaller for T-bills and larger for notes and bonds.
So if a bank posts a 2020-vintage 30-year bond — face value of $1,000 and a market value of $500 today — as collateral, it would get maybe a 3% haircut, so -$15, and so it could borrow at the SRF $485 on that $1,000 face value bond.
I wonder if the effect is simmilar to a higher reserve rate. With unrealized losses those banks should be more conservative and reduce the risk of beeing forced to sell before the maturity ends.
Though todays excess liquidity that bubbles up the market seem to get their money not from banks but from private credit.
This only means 1 thing, higher interest and more volatility. Expect the Government to pay a higher rate to attract private hedge funds.
As a foreign state, devaluation of the US dollar comes to mind when they sell US dollar Treasuries. A US foreign based hedge fund does not have to exchange it winnings into dollars, their balance sheet is already in dollars.
I would guess that foreign states selling US treasuries expect a US dollar devaluation in the future. After all, a 10 percent devaluation of the US dollar against their home currency, would easily offset any interest profits made in dollars.
It’s the other way around. Read what I said in this article and the linked article about Japan and its interventions. Japan made lots of profits on its Treasury sales because the yen collapsed against the USD, not the other way around.
The increase in Basis trade holding filled the gap of all foreign central banks decrease holdings. From what I read the basis trade is composed primary of bond above 10 year duration. what could go wrong on a highly leverage USA hedge debt trade?
Cheers
When is the US going to get a reasonably intelligent Secretary of the Treasury with some degree of honesty and responsibility towards managing the appalling mess that US Treasuries have become?
MW: The Fed hasn’t been this terse since 2007. What a 130-word statement signals for market stability.
Let’s see, every time the Fed increases rates the older treasuries(lower interest rate)lose value, ie, discounted. So, if those who bought them had swap agreements, ie, hedged they’re protected. The hedge funds who are also holding dated treasuries of lower interest rates are most likely short selling to maintain or exceed par. Those who are long in duration are the most exposed to increasing interest rates. Those who are short have the opportunity to gain particularly from the FOMC guidance speculating/front running the Fed. And, the media(useful idiots) seem to not have a clue on why the Fed doesn’t want to telegraph their guidance.
Your theory doesn’t work because that’s not how the bond market works.
The Fed’s rate hikes only impact more or less short-term securities, such as T-bills or 10-year notes that were issued 9.5 years ago and now trade like T-bills. Their yield moves with the FOMC’s rate decisions or the expectation of those decisions. But the change in price is minuscule. Why? Because the buyer is going to get face value when the security matures in a few months, plus the full interest (if T-bill) or the last interest payment (if coupon). So the discount induced by a rate hike is so small you can barely see it.
In addition, the rate hike was priced in and short-term yields rose ahead of it in anticipation. Now they’re rising in anticipation of the next rate hike. For example the 6-month yield is 38 basis points ahead of the post-rate-hike EFFR, but only gained a couple of basis points following the rate hike.
If you have to sell $1,000 of face value of 6-month T-bills that you bought 3 months ago at auction for $980 (the difference = interest), you will find that the discount is negligible because the buyer will get $1,000 in three months. So how much is the buyer going to pay you to get $1,000 in three months? You collect the amount you paid plus the first 3 months of interest, but will give up the next 3 months of interest (=$10) that go to the buyer, plus a few pennies to account for the higher current yield. So you might get $989.50 for the bills that you paid $980 three months ago. Which is why T-bills are liquid and not really subject to interest rate risk.
But the longer the remaining maturity, the bigger the loss when yields rise, which is why bonds with 25 years left to run get hit so hard when long-term yields rise.
But the Fed doesn’t control long-term yields: In late 2024, the Fed cut by 100 basis points, but the 10-year yield rose by 100 basis points. If you engaged in a leveraged bet that the Fed’s 100 basis points in rate cuts would have produced a 100-basis point decline in the 10-year yield, you might have gotten wiped out. That’s the bond market at work.
The Fed raised on Wed, yesterday the 10-year yield dropped sharply and today the 10-year yield is back at 5%+ . It’s the bond market that decides this in its chaotic interplay between buyers and sellers, not the Fed.
Long term treasuries 5-30 years out have lost value. Yes, they can hold until maturity but they lose yield to inflation every year. There were long term treasuries that were bought at 2 to 2.5% during 2020-2022. Every year they hold they lose to inflation. They can hold till maturity or the possibility that interest rates decline. If they sell now they face a 40-50% reduction in principal. I have been investing in treasuries 1 year or less and some are slightly discounted but with the maturity being a year or less it’s not a problem to hold to maturity. Just go look through the CUSIPs 5-30 years, somebody’s holding them at a loss, or hedged/swapped. The losses add up when you’re holding billions of dollars in long term treasuries. One percent of a billion dollars is 10 million dollars. If your duration is five years or less it’s reasonable to wait it out to maturity.
PS Yen,
Keep in mind as the Yen lost value to the dollar the energy costs skyrocketed in Japan being oil is priced in U.S. dollars. With a lower yen Japan is able to be more competitive in exporting, however, they have to import too, which may cost more depending on what they’re importing and in what currency.
Re Wolf’s: “But these private foreign holdings are not purely “foreign.” They include large amounts from US hedge funds that are domiciled in foreign financial centers, such as the Cayman Islands,” this is correct. Offshore hedge funds are often a vehicle for tax-exempt U.S. investors to engage in leveraged trading. This is because of unrelated business taxable income–basically the profits from leveraged trading. U.S. tax-exempts are taxed on their UBTI if the trading is conducted directly, such as through a U.S. brokerage account. But the use of a corporate “blocker,” such as a Cayman corporation, essentially converts the taxable UBTI to non-taxable dividend income.
What do all ya’ll expect after 17+ years of rate suppression?
RISK is being repriced, globally.
Fed raised. Not cut. On Wednesday
This seems unrelated to default/inflation risk, given that the trend started all the way back in 2008.
Brad Setser is probably the world’s most knowledgeable expert on foreign reserves and he’s been tracking them for over a decade. In this article, he says that a lot what used to be held by central banks is now held by pension funds, sovereign wealth funds, and government-controlled insurers and banks.
https://www.cfr.org/articles/de-reservification-not-de-dollarization
He also has mentioned several times that official data can be a bit misleading. For example, he says “SAFE [China’s foreign reserves management organization] has shifted its funds out of U.S. custodians, and thus increasingly appears in the data as a “private” holder in a European custodial center.”
He agrees with you that many of these investors have been moving from Treasuries to stocks for a while as their main focus shifts from safety to yield.
Anyway, he’s an excellent (if very wonky and detailed) read.
China has also moved from Treasuries to agency securities which pay higher interest rates and come with the same government guarantees. But the data on that is spotty, just like the data of moving Treasury holdings into custodial centers, such as Euroclear or in the City of London, because custodial centers don’t disclose any of this. But as I show in the article, the holdings of these financial centers are soaring.
The speculation is why?
Why are bond investors retreating?
I suggest the answer is multifaceted.
IMO, US foreign policy is major reason. One shouldn’t seize $300B of Russian assets, declare SWIFT a weapon of financial mass destruction, commit financial and other war crimes, etc. while assuming impunity.
The message is loud and clear. The US cannot be trusted to store one’s wealth in.
It’s doesn’t take much research to figure out a vast amount of the world thinks US moves in the ME are insane.
“The message is loud and clear. The US cannot be trusted to store one’s wealth in.”~ not only did European countries start pulling Gold out of the USA they also pulled it out of Canada(I assume they thought we could take it over) and placed the Gold in London. Great Britain is still trustworthy with keeping Gold safe even though they need more yield to sell debt than the USA.
Risk mitigation not taking chances!
DXY is still strong.
10-year Treasury having its worst run in over 100 years!
Beijing’s holdings fall to 2008 low…
@wolf I am sharing a tweet here.
“India bought $15.2 Billion of U.S. Treasuries in July, their largest monthly purchase in history.”
Some tout this as bullish dollarization (not de-dollarization). But this is just one purchase. Per your chart, they are actually buying less year over year. So how is it a plus for dollarization?
People have been going nuts about this “de-dollarization” BS ever since Adam and Eve, and it still hasn’t happened. India’s currency continues to collapse against the USD. Why would people and institutions in India not try to buy something that doesn’t collapse?
Brad Sester’s de-reservification
Wolf Richter on this topic:
https://wolfstreet.com/2026/03/28/status-of-us-dollar-as-global-reserve-currency-usd-share-drops-to-31-year-low-as-central-banks-diversify-into-other-currencies-gold/
which includes this chart, among many others, share of foreign exchange assets:
Great March article on currency reserves. It’s just now getting more attention.
The current spread between the Interest on Reserve Balances (IORB) and 6‑month Treasuries is roughly +0.30 to +0.35 percentage points, with 6‑month bill yields trading above the IORB rate. Still an easy money policy. Banks make more money buying Bills than holding IBDDs, interbank demand deposits held at one of the District Reserve Banks.
Bonds are just like houses…..
At some price, they will look good!
Please note that if the face value of bonds falls, this does not mean that investors’ holdings are being voluntarily reduced.
On the other hand, I’m European and whilst I invest in Treasuries, I’m not particularly concerned about their normal volatility in an environment of high inflationary pressures and corresponding interest rates.
Not all of us in Europe invest in Treasuries in search of a higher yield.
Just a note on the vocabulary here:
The “face value” does NOT fall. The face value is fixed, and that’s what you get when the bond matures (except with TIPS where the face value grows with the inflation protection). Which is why you’re not worried.
What can rise or fall second by second is the “market value.” But that only hits you when you have to sell the bond before it matures.
Absolutely. My sincere apologies for the slip-up, especially as English isn’t my first language. But you’re absolutely right. It’s the market value that can fall even if the bondholders don’t sell them, but it gives the impression that they are selling.
Thank you very much for pointing that out.
On inflation, the bond market will lead and the Fed will follow.
I should also have mentioned that I can buy (or sell) Treasuries as part of a portfolio/trading strategy, within a specific estimated risk profile which may vary, without, however, worrying too much about the value of the bond themselves. But rather about the portfolio itself. Just think of the classic 60/40 strategy: despite the fall in the value of the bonds, the result remains positive this year.
I think that bond prices are falling, but not in a disorderly and chaotic manner, as is claimed in some media outlets by certain opinion leaders.
Thanks again.
So is the summary here, that foreign central banks and governments are divesting treasuries and “foreign” but probably domestic private parties are buying treasuries but we don’t know who or why they are doing it?
Given the AI boom and datacenter buildout which is consuming trillions of capital, why would any private parties be using their money to buy trillions of treasuries?
“Treasury securities have lost their allure for foreign central banks”
as the harvesting of the myth that the American dollar is a hard earned asset is obviously coming into question too any financial analyst worth their salt.
Also there is a very nasty flu going round that comes on in a day with the calling card a strange tickle in the upper lung, occasionally leading to a cough
Five days sick.