They got spooked: 2-year Treasury yield +13 basis points to 4.90%, after yesterday’s auction. 7-year +14 basis points to 5.04%. 30-year hits 5.39%.
By Wolf Richter for WOLF STREET.
Treasury yields in the 2-year to 10-year range spiked by 12 to 14 basis points this morning, with the 7-year yield going over 5% and the 10-year yield hitting 5.10% currently, after the S&P’s Flash PMI showed red-hot growth and underlying inflation pressures in services and manufacturing, while the announcement of another Treasury buyback auction tomorrow fell flat.
The 10-year Treasury yield spiked by 13 basis points this morning to 5.10%, the highest since June 2007, having therewith broken through the 5% ceiling it had gotten stuck on and bounced against for two weeks.
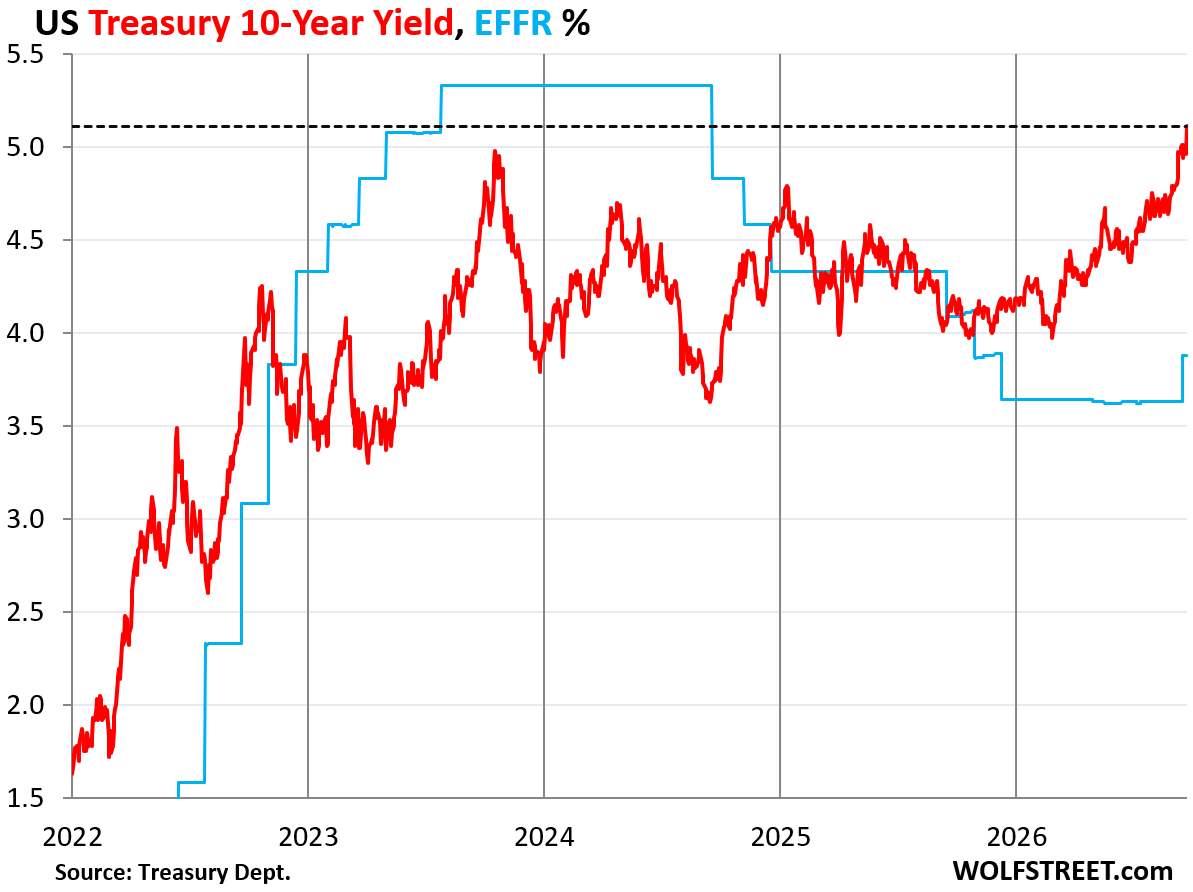
What exactly causes markets to suddenly get spooked like this is always a form of speculation, so here we go again. Today’s spook-moment came right after the release of the hot S&P US Composite Flash PMI that had underlying inflation pressures in services and manufacturing written all over it.
From the S&P PMI report:
“US business continues to boom, with output growing at the fastest rate for over five years in September. Historical comparisons suggest that the latest survey data point to annualized growth of around 5% with a 4% gain now signalled for the third quarter as a whole.
“To put the growth surge in context, barring the spike in demand following the opening up of the economy after the COVID-19 lockdowns, the latest improvement in business activity is the greatest recorded since early 2015. Business is clearly booming now in both manufacturing and services.
“However, this growth is being accompanied by some of the most severe supply chain bottlenecks seen in the near-two-decade survey history if the pandemic is excluded, with companies also reporting increasing problems finding suitable staff. Backlogs of work are consequently rising sharply. While this accumulation of uncompleted orders bodes well for the further expansion of output and capacity in the coming months, it also indicates that companies are developing more pricing power, and hence is a worry for the inflation outlook.
“Firms’ input costs have meanwhile jumped in September at the steepest rate for four years, with fuel and transport costs spiking higher thanks to the rise in oil prices seen during the month, which will add further to the upward pressure on selling prices and inflation in the coming months.”
Here is the long view of the 10-Year Treasury yield. At 5.09%, yields are not high in a historical context beyond the era of QE:
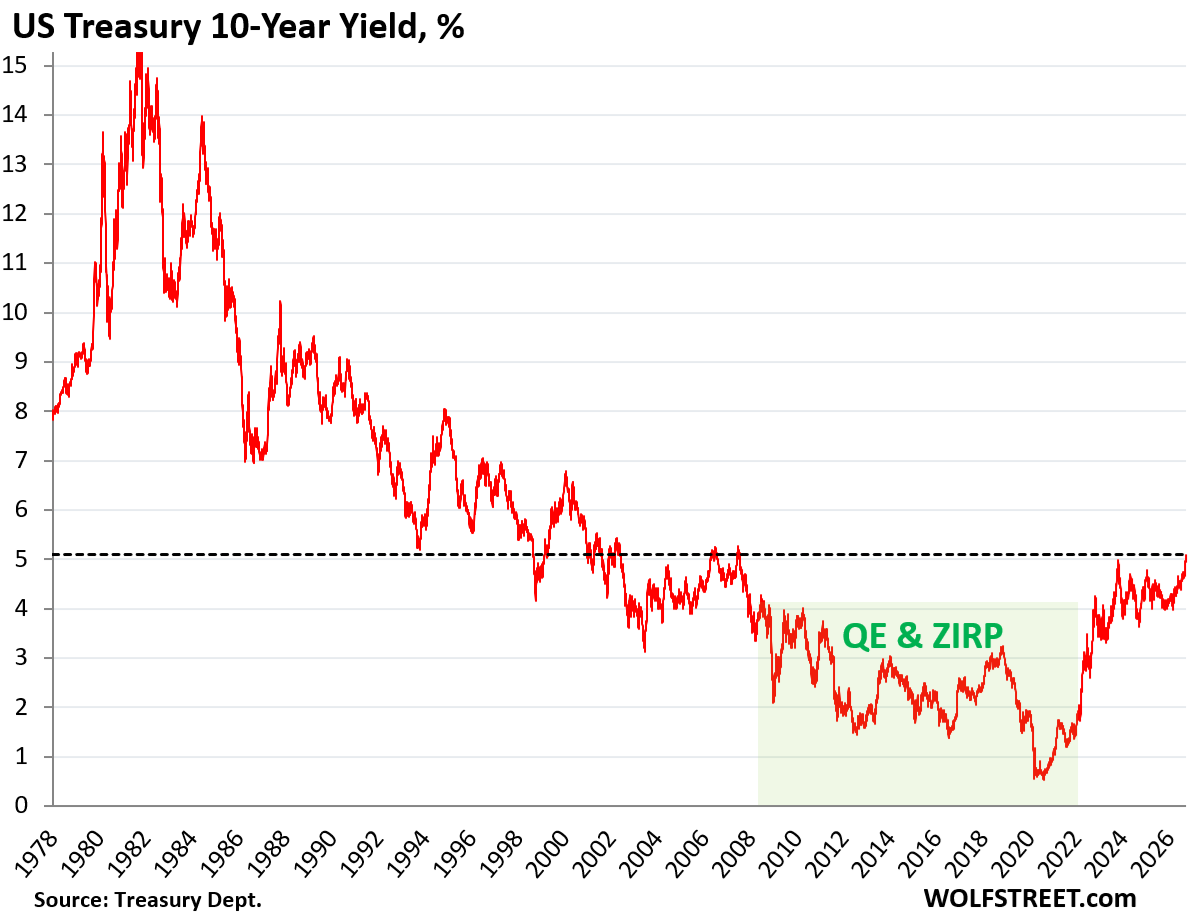
The Treasury buyback announcement this morning fell flat. Treasury said it would buy back up to $6 billion at face value of 20-year and 30-year bonds maturing between February 2047 and February 2056. The actual prices paid at market value will be less than $6 billion after the big haircuts for debt issued during the low-interest-rate years. The $6 billion cap at face value is the same as at the last buyback auction of this type held on September 11, after which yields spiked further, which was not the purpose. The purpose of these buyback auctions is to push down long-term Treasury yields.
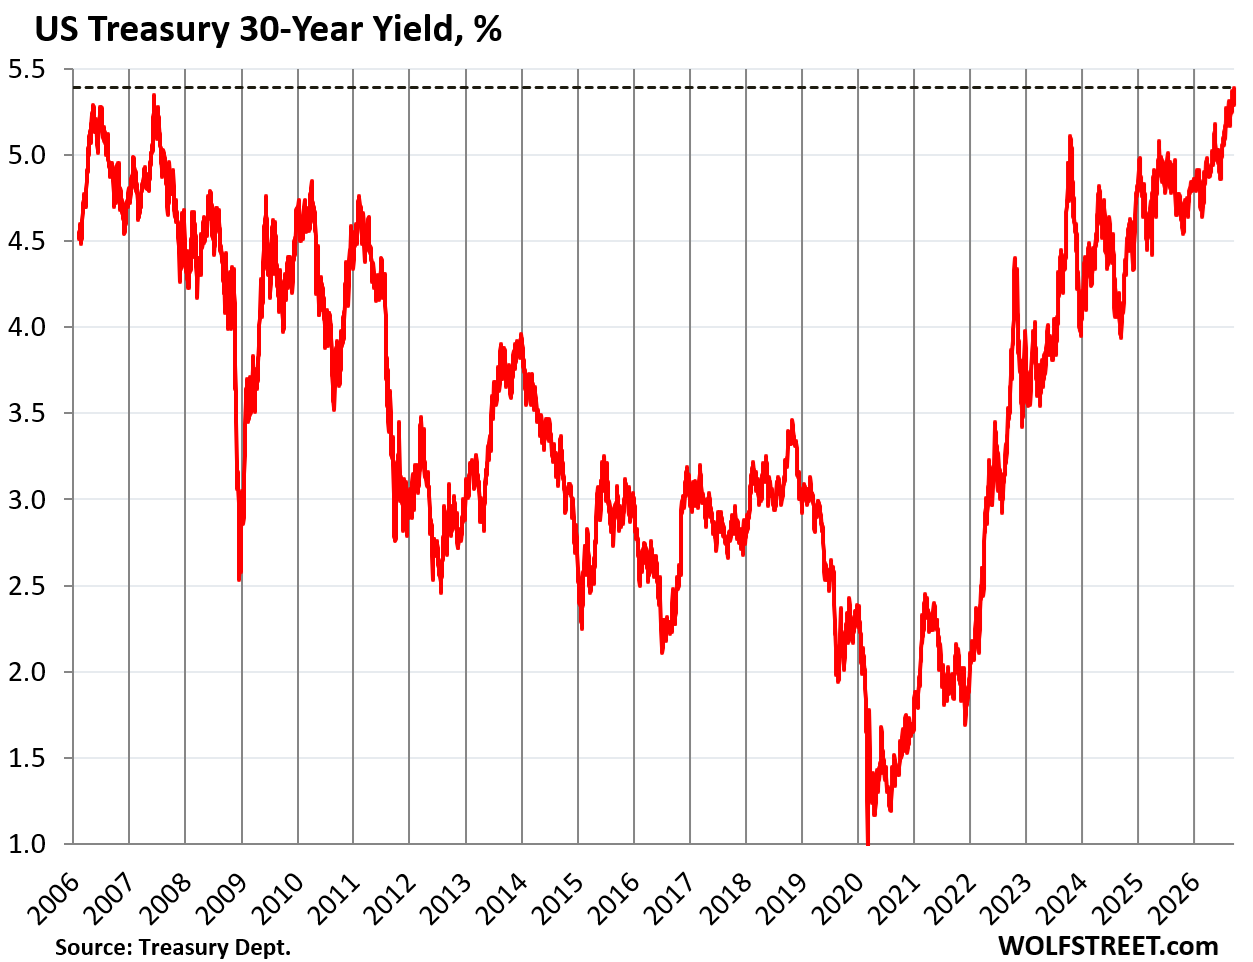
The 30-year Treasury yield spiked by 9 basis points to 5.39% at the moment, the highest since July 2004, having edged past the 5.37% high on September 10, and past the 5.35% high in June 2007.
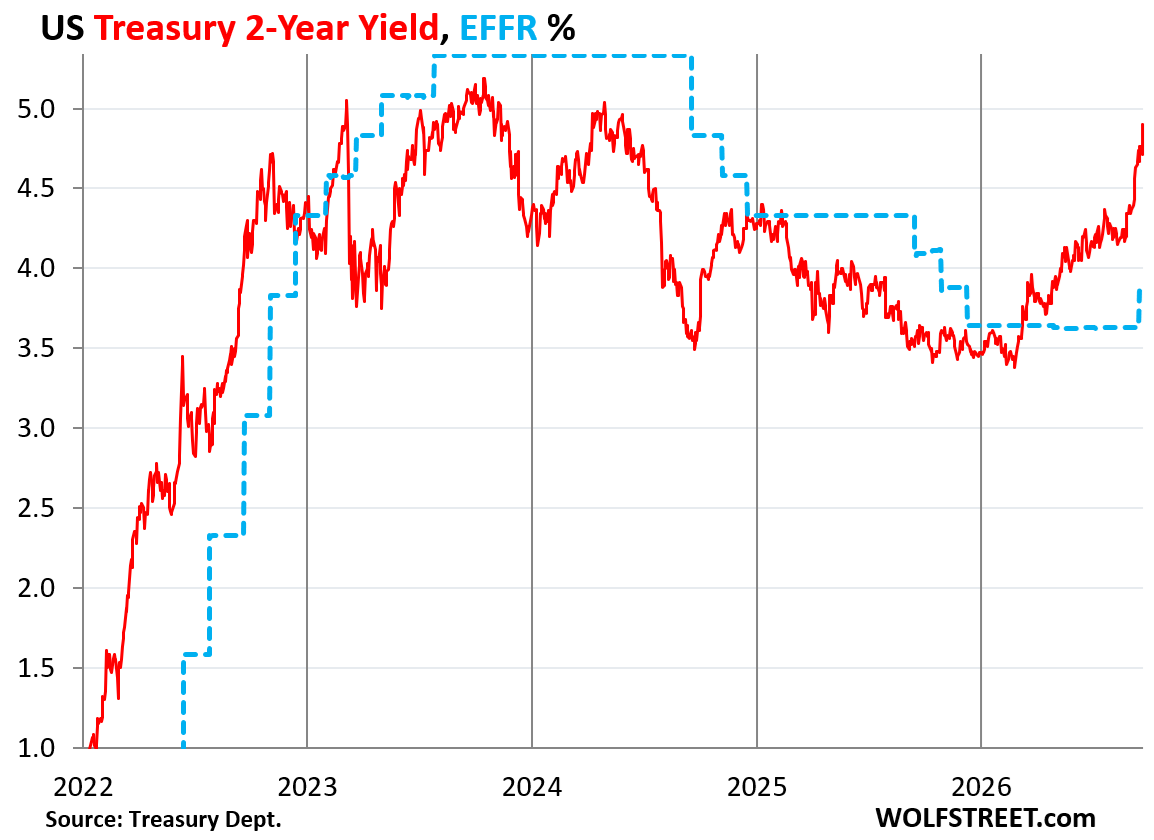
The 2-year Treasury yield spiked by 13 basis points this morning to 4.91%, the highest since May 2024, four months before the rate cuts had even started.
The Fed pays attention to the 2-year yield; it’s a strong signal for the Fed about its next policy moves, and the 2-year yield is telling the Fed to hike its policy rates pronto and multiple times.
Yesterday, at the 2-year Treasury auction, it took a yield of 4.787% to sell all $79 billion of 2-year notes, the highest auction yield in two years, now crushed in the secondary market. It’s quite something that the already highest-in-two-years auction yield is followed the next day by a 13-basis point spike in the secondary market. Some people are now kicking themselves for having bought too early.
The 7-year Treasury yield jumped by 14 basis points this morning, to 5.04% ahead of the 7-year note auction tomorrow. Now all yields of 7 years and longer are over 5%, with the yields in the 2-year to 5-year range closing in on it.
Update on the the 5-year Treasury yield, after today’s auction results were just released: At the 5-year note auction today, it took a yield of 5.033% to sell all $80 billion in notes, the highest auction yield since before 2006 (which is as far as I checked). In the secondary market, the yield then spiked further, now by 18 basis points to 5.03%. Someone is getting spooked.
Enjoy reading WOLF STREET and want to support it? You can donate. I appreciate it immensely. Click on the mug to find out how:

10Y yield headed to a 2-handle when stocks implode. Sovereign debt doomers are early.
LOL! The Fed has made it clear that we will never see significant deflation in equity prices. Don’t overthink this. Risk is simply being repriced, globally. 5% on the ten year is also NOT a “high” rate of return.
Yeah, it’s over now
But I can breathe somehow
When it’s all worn out
I’d rather go without
We pay our debt sometimes
Yeah, we pay our debt sometimes
AIC is much better than AOC :D
Thanks wolf
ZiIRP World was a Hocus Pocus show that lasted longer than anyone could imagine. Now that dream is over. Reality sets in. The drug trip (ZIRP) is over.
ZIRP was 100% created so that rich scumbags didn’t have to take their losses on bad bets. “Privatize the profits, socialize the losses.”
think of all the pension funds and the insurance company investments for annuity payments. The stock market demise will touch a lot more than a rich…
These funds are out there buying DogeCoin and AI-powered fart deoderants at this point.
Pigman talking points.
The 2 year already up 17 bps now. Oof ouchie.
I missed the 2-year auction at Treasury Direct yesterday. The stupid Google AI told me 22nd was the last day, but it was 9am on 22nd pacific time cut off time. I suppose 3-year north of 5% wouldn’t be so bad few days from now.
10-year Treasury yield now +16 basis points, to 5.12%. This is turning into a rout.
The results of today’s 5-year not auction were just released, and I updated the 5-year part of the article with it.
Someone is getting spooked: It took a yield of 5.033% to sell all $80 billion in notes, the highest auction yield since before 2006 (which is as far as I checked). In the secondary market, the yield has now spiked by 18 basis points to 5.03%.
I think the market is going to take a breather here and back off a little. The buyers are starting to come out at those yields.
5.15% today 🍿
Personally, if someone told me that their currency is boss, and that they would print even more currency by buying their debt, to fund their spending spree, I would want a ton more that a measly 5% return buying into that scenario. Especially if that money was to just keep up with on going willie nillie operations, and especially if they carried a 40 trillion debt bag and growing into this. And especially if they wanted 10-30 year terms.
I might not even lend to that person at all. Personally.
Let them buy down even more debt issuance, and see where that gets them. The audacity. Where’s the leadership in all this anyways? Out golfing?
Out golfing is a safe bet.
“Where’s the leadership in all this anyways? ”
20 years of ZIRP money-printing leads here and I wonder where all the outrage was *then*, when the inevitable cancer was cultivated.
Wolf, the money market at Fidelity is paying 3.4% interest as of yesterday. Would some fund investing in 2-5-year treasuries be a good choice now? I suppose that same fund would have lost significant % in just the last 2-3 months.
If you want Treasury exposure, you could buy Treasuries at the auction. No fees. You can do that at Fidelity. You can buy 6-month T-bills, they’re now at about 4.35%, and put them on auto-rollover. Lots of people here are doing this. The yields beat Treasury money market funds because there are no fees, and is safer. If you want to lock in 5%+, you can buy a longer-term Treasury at Fidelity, either at auction (7 year tomorrow) or in the secondary. You might find something with a remaining maturity of 5 years yielding over 5% in the secondary. You should be able to do all this online at Fidelity.
Thank you, Wolf. That makes a lot of sense. I will try to build it up at auctions slowly, up to 5-year durations — it is probably similar to Treasury Direct.
Btw, every time I go to a big bank to open/renew a CD lately, they roll out a used-car-salesman looking “wealth manager” to get me a better 9-10% yield. My guess is they are looking for suckers like moi to buy Nvidia for $5 Trillion. Or OpenAI, or Anthropic for few Trillions.
@wolf – What are the risks of enabling auto roll for a t bill?
There are no risks. You can take them off auto-rollover any time with the click of a mouse (but check for the deadline before the next auction, I think the day before the auction you can still cancel, but check if you’re trying to cut it this close!).
T-bills are also very liquid and easy to sell in the secondary through your broker. So if two weeks after you bought them, you decide you need the money, you can sell them. That’s what they’re for.
Why buy a bond fund when you can just buy the bond? Bond funds plummet and rip your face off when interest rates go up.
Andrew, the value of the bonds you hold goes down just like bond funds, which you’ll discover if you try to sell them. The only difference is there’s no real-time price quote for your bonds, so you’ll need to ask your broker what your bonds are worth.
The main difference is that you can hold bonds to maturity and get face value at maturity plus the interest, while bond funds don’t mature, and you don’t get face value back in three years, and when there is a run on the fund, the fund has to sell those bonds which locks in the losses, and the bond fund never recovers to what you paid.
The shorter the average duration of a bond fund, the less risk it has. Money market funds (=short-term bond funds) operate at an average duration of about 3 months, and that’s fine, and very low-risk. Long-term bond funds (such as TLT) are risky, though they have been mis-sold as safe, and most people don’t understand what risks they’re taking on. Long-bond funds were invented during the 40-year bond bull market, and they worked great during those decades because yields kept zigzagging lower. But that’s over.
Most 401ks do not offer direct bond purchases. Not many good bond options, unfortunately.
Wolf can correct me if I’m wrong, but you can buy closed bond funds that are not forced to sell based on inflows and outflows. There are some options out there that have years and years of consistent dividend delivery and they’re not forced to sell.
This goes all the back to the Bush Jr months preceding the big market crash. Ominous.
I remember. It feels eerily similar except now we had the covid led housing boom and AI bubble smashed together.
Saw yesterday that AMD is now valued at $1T. What a joke. Things have gotten so far beyond rational that I can’t fathom what the downturn will look like.
Like beetlejuice, he appears!
I did back of a napkin calculation sometime ago – top 10 semi stocks are something like $16 Trillion. Thats just one area in the market. Walmart is $1 Trillion. Lilly is $1Trillion. SpaceX is $2 Trillion. Wolfstreet is probably also $1 Trillion.
$1.2 trillion after today’s spike.
I’ve been wondering if that’s why bond yields aren’t even higher than they are.
Maybe Sept 18, 2028 will look a lot like Sept 18, 2008. Only bigger.
The 10-year US Treasury at 10% would be a very nice number.
If it’s true that many things follow the Fibonacci sequence , it could get to 8% in a jiffy.
You do know who Fibonnoci was and he has his own cipher… Gemetria and Numerology and mathematics, the language of our institutional overlords who defined this reality with a ledger and a sword but the pen is mightier than the sword…why game the design, because it is our divine right to do it…
SoCalBeachDude …..
I liked Volcker’s 10 year at 15% ( in 1982). My Merrill Lynch CMA then was paying 21% on cash. But Volcker had a pair …….
At the time, a lot of Treasuries were callable, esp. the 30-year bonds, and were called when yields dropped. Investors who thought they’d locked in 15% for 30 years had 15% for a few years, and then they got face value back and the option to invest it at 8%. Which caused a huge furor because it deprived investors of the rewards for the risks they’d taken. After the furor, Treasury ended issuing callable Treasury securities. But agency securities are still callable to this day, and are getting called all the time.
10-year yield leaps to 19-year high…
Mortgage rates surge above 7%…
POLL: Trump approval hits lowest of career…
Big Beautiful Bill Starting to Bite…
Nasdaq leading stocks lower as 10-year Treasury yield surges to highest level since 2007
If only Xi were kind enough to help stabilize the US treasury market when he and Trump meet tomorrow
Maybe this is all ultimately being driven by the $40 trillion deficit instead of by yields and the policy rate.
In that case, both the administration and the Fed will be shown to be equally impotent and in deep trouble.
How could this happen when Uncle Scam only borrows 8% of gdp year after year and payments on 40 trillion$ plus debt cost 1.2 Trillion$ annually and rising which is 30% of all revenues. Doesn’t make sense.
6% of GDP, not 8%.
LOL! Humor in plain sight, that we don’t usually pay attention to.
GDP itself is huge percent of government spending. i very flawed measure of prosperity. bombing other nations is not productive. the P in GDP.
The entire defense spending, including the parts that are not even part of GDP such as foreign operations, is only 3% of GDP.
1O ust at 5.3 is the target. a few days over 5.3 than greed in equities turns into full on panic(think circuit breakers) I was planning on buying at 5.3 for couple of years now. But black swans are too numerous with this….., no predictably in actions. Plus the margin expense to carry the leverage in the basis trade will eventually kill the profitably of the trade. As people de leverage from basis trade it’s going to fuel the surge in yield! Its circular feedback loop once started will become a yield rocketship in 10 to 30 year UST bonds. Countdown is on!!!
Looking at the 5 year rising wedge breakout I see target at around 6.8%….maybe early next year?
Yeah, it could happen by then. We have 5.138 as the monthly close high in 2006 for $tnx and that’s yield resistance for now. when we closed out the millennium we got 6.66% on the $tnx or 10 year. Right now the 200 monthly average in TNX is 2.666%, I like that symmetry it tells me to pay attention!
6.75% is my old buy @ 5.3%. I am buyer at 6.75% except at that yield equities are going to look real attractive for the first time since the Covid low in 2020. One day at time! But it’s good to have plan.
I’m most curious about the impact of technology on this. What I mean by that is how easy and fast it is for individual investors to go into their big chunky 401k and perform a massive shift in assets with a few clicks or taps on their phone. We’ve seen the impact before and have some controls like the market circuit breaker to control automated trade cascades, but not in the ubiquitous smartphone generation.
It’s almost paradoxical, but the higher percentage of financial literacy in the general population, the higher the chance of major market panic triggered by rebalanced retirement accounts. Easy access, immediately available research, and huge self directed balances for your average salaried American. Pretty scary time to work for a mutual fund when you think about it.
Posted my house for sale in July because I was tired of being a landlord and didn’t want to do it. Struggled the first 30 days on the market and I decided I needed to cut fast and hard. Took $80K off the price and sold it for all cash and close in two days.
Its looking like I made the right call and got out just in time.
Congratulations:) :)
My memory is a bit fuzzy but I recall RE prices rose along with rates in 79/80 until it finally blew up in 81.
Anyone have better recollection?
Case-shiller says there was a mini boom from 76-79, rising about 15-20% faster than inflation before stalling and inflation eating that right back by 82.
Yes, I have more clear memories of 80-83. Brutal job market. I finally landed a job for the County Park taking home $385 every two weeks + free parking for my converted hippie bus at the park and thought I had made Easy Street. Actually, it WAS easy compared to 79-80.
Yes but the prices were but at bleeding levels that time
Tell me how happy you are after the money transfers?
Congrats some great timing
I can top that. Bought a neighbouring property….closing date right now, today. Possession date Oct 15. Had no other option as someone else was going to turn it into a vacation rental….or worse, as the price was low enough to get a real dodgy neighbour. (rural). I have already given the house away to be moved by summer (double wide). They pay and will help the move prep. The greenhouse is going to a friend on October 15 (we already have greenhouses). Amalgamating the two properties to avoid future capital gains as it will be part of our primary residence. Blew my/our savings to pay cash, but no returns these days, anyway. Reading so many comments daily about savers getting an extra 1 or 1.5% and wince. Seriously? With inflation tearing the scabs off more and more we (savers) will be behind even further this year, and the next and so on. The property went for considerably less than current market, anyway.
As far as I’m concerned the formula that works long term is no debt. Reduce debt. Lose debt. Don’t rely on debt. I cannot believe there are still margin investors out there. And Govt…all governments are the biggest ones doing it. Sure, a mortgage is necessary to get started in life but take one on that is affordable should rates rise…even double like mine did in 81. Same for public infrastructure financing. Keep debt reasonable and ride out the change. I learned that very hard lesson in the 80s and barely survived the experience. It was hard.
That 40T G debt is going to balloon with a capital B, and the king of debt still has 2.5 years in the saddle. Good luck.
The folks getting “spooked” went to isle 6 of their local store before the auction and saw what things cost. Or perhaps they wanted to book a flight since their private service was unavailable.
Washington DC is full of genius experts, who say it’s temporary and not bad at all. We just have to wait til the midterms and back to normal.
Wolf, is there any breakdown in what sectors are are accounting for those growth numbers? Other than AI related activity and oil, I’m not seeing evidence of that kind of growth in company reports.
Thanks for your great reporting
So as I said in the article, it’s broken into services and manufacturing. Both were hot. Services were red hot. The S&P PMI data doesn’t go into sectors within those categories. But the way it reads, it’s broad-based, across services and manufacturing. Here is the entire report (the charts are copyrighted, so I cannot post them here, but they’re worth a look … it’s not a one-month fluke).
https://www.pmi.spglobal.com/Public/Home/PressRelease/ed177f50167b4203ac490a961ea706be
BTW, the Atlanta Fed GDP estimate for Q3 GDP is now at 5.1%, with strong consumer spending growth being the biggest contributor (I covered a bunch of consumer spending data here). Nonresidential fixed investments (such as AI data center construction) was also a big contributor. That parallels the S&P PMI.
I don’t think we’ll get 5% GDP growth in Q3. It may be closer to 3%, but that’s still strong. Note: all these GDP figures are “real” GDP (inflation adjusted).
and here is the BOJ that owns a declining asset that they might wish to sell, but Bessent will “spin the plate” so it won’t happen.
What a mess.
But the Japanese bought the “declining asset” with much stronger yen years ago, and when those declining assets are redeemed and the Japanese get the dollar face value, they convert that into their weaker yen, and make a huge profit in yen. Here are the details:
https://wolfstreet.com/2026/09/07/by-dumping-us-treasuries-to-prop-up-the-yen-japans-foreign-currency-reserves-plunged-by-95-billion-in-august-but-dont-cry-for-japan-these-interventions-are-hugely-profitable/
Title and subtitle:
“By Dumping US Treasuries to Prop Up the Yen, Japan’s Foreign Currency Reserves Plunged by $95 Billion in August. But Don’t Cry for Japan. These Interventions Are Hugely Profitable”
“The government is already busy fighting over what to do with the $31 billion in profits on its foreign exchange interventions last fiscal year.“
Howdy Youngins. Aren’t you glad you found the Lone Wolf?? He has been tellin Yall this stuff for some time now…..
All the members at Squirrels Anonymous increased their children’s allowances ten fold. My thirty year olds sons are loving this time even though they are prisoners to their 2 percent mortgages. We is gonna sail to new horizons with lots of CASH to spend. What a great time to be retired….
Sober Sailor Sailing till Death
I am so happy to see UsdJpy = 158.28.
Two weeks ago, when it was 156 and heading south, several banks loudly proclaimed that UsdJpy would soon touch 150; guys like Brad Setser and Robin Brooks were loudly saying Jpy was too cheap. When it strengthened to 154 those dudes were positively crowing, taking victory laps, bragging about 150-here-we-come.
And now they’ve gotten their lunches handed to them.
(I’ll get mine handed to me, too, soon enough; but today I can crow.)
Intervention hocus pocus Bessent 3.0 coming soon
Maybe Bessent can sell some NFT’s to calm down the market… :)
Transports are foretelling. I might do 3 month t bills here cause if rates blow out, I don’t wanna be holding underwater paper for years.
I would rather taken 4% for a few months as the yeast rises the bread. Maybe a year ago the 5 yr was 4.8 and someone on here thought that was the way to go and bought. He had a chance to take profit and I hope he did. Otherwise he’s now underwater on his purchase and who knows where the 5 year will be 4 years from now. And now you can collect 4.9 on a two year!
Citibank has 4.25% 12 months CD, no min required.
No state tax on my Bills. I like that. And as Yappy said, “I might do 3 month t bills here cause if rates blow out, I don’t wanna be holding underwater paper for years.”
I suspect January will see the 1 month T Bill back up to 4.5 and back to 5 in a year.
Goldman Sachs Marcus 9 month CD at 4.30 %. I’m waiting for more …..
When the banks start getting pushy with CDs in their apps, you know interest rates are likely gonna go up. They only get aggressive selling them when they know they’ll make some hay. I started getting Ally CD ads a month ago, I’m sure they have done well from that push.
As expected from Don businessman. Why anyone surprised? Expect worse, way worse. The mob voted and there are consequences.
The danger with the Bond Market Will Lead, the Fed Will Follow is that you make not like where the bond market leads …
I am skeptical the Fed will move to establish its credibility until after the midterms. Too little, too late for the would-be inflation hawk Warsh.
Not to worry. The government has never defaulted.
Yet.
The worry is inflation. Inflation can wipe out the purchasing power of long-term bonds, and yields need to be high enough to compensate holders for it, plus some. Inflation in GDP in Q2 was 4.4% year-over-year and 6.1% annualized. That was bad. In Q3, it’s likely going to be even worse. Bond holders are not getting compensated at current yields for this type of inflation, and for the “plus some.” That’s what I’m worried about, not the default nonsense.
Wolf question: The Trump admin is planning on placing a diesel export ban. With less demand, wouldn’t the admin have to force the sustained production in order keep diesel prices low? If admin buys the excess to fill reserves it will eventually have been a soft bailout.
This is pure speculation but it is a slimy way out of the mess.
TIPS real rates increased by 10bps or more across all maturities. Unbelievable.
09/22/2026 2.51 2.56 2.63 2.88 3.04
09/23/2026 2.65 2.70 2.76 2.99 3.14
I scanned a FRED chart and it looks like these are the highest real yields going back to brief spike during the GFC.
Bond vigilante to bond market: “What we’ve got here is failure to communicate.”
Took a risk and grabbed a tranch of TIPs today… I don’t understand how inflation can be the excuse and the TIPs get seemingly cheaper than the non-TIPs…
I’ve been nibbling too as real rates ratchet up. They’re all hold to maturity for me. Spending smoothing for my future self. Now we both just have to cross our fingers that “They” don’t lobotomize CPI calculations when it suits “Them”.
This should also increase the fixed rate component of ibonds at the next rate reset November 1. The fixed rate is currently 0.90%, could jump near 1.3%. Someone here recommended selling any older ibonds with zero fixed rates and upgrading. I have some over 5 years old (and thus no interest penalty if sold), watching with anticipation.
Great movie, and equally great quote far damn shore…
Good analogy also, as we can expect at this point that some entity will do what the guard did, and shoot the market right in the fore head or other ”’fore”’ of whatever you choose to at least try to stop the absurd degradation of the USD due to the incompetence or corruption of the FRB…
Hedge accordingly is a good ”meme” for these times,,,
Good Luck and God Bless all on here commenting and especially the Wolfster!!
Anyone else picture Bessent in the role of Kevin Bacon at the end of Animal House?
” No worries. Everything is under control.”
Bessent: “I got this ….. hold my pink lady …..
Stupid question, but any chance this is on purpose. The high bond rates go, the cheaper we can buyer put old debt back….
If we could have high rates and a reduction in govt spending for a bit we could make a dent in the national debt
No. None of the major players (government, large banks, large corpos) want US yields spiking.
This is bond customers not buying US bonds in this environment. Maybe because of inflation, crowding out by the corporate bond market, currency devaluation concerns (an “easy” way to payoff debt prices in your own currency), and/or repatriation of assets, something else, or all of the above.
Dang my phones autocorrect has a mind of its own. Lol.
And good points. You’re right. All I could think today was well at least if yields are going up, we can buy back the national debt at a pretty nice discount.
“on purpose” by who? The Bond Vigilantes?
Unless you mean Iran. Iran clearly wants global economic pain to pressure US foreign policy.
I finally started nibbling today. It’s been a long time. $10k at a time. I’m ready to ride prices down/yields up from here. Others here might consider possibly doing same.
So, what are you buying?
Bought a lot of TIPs, some 10 years and a tiny bit of crypto (Hype)
And an 18.8% dividend yield bond fund selling at a an almost 8% discount from NAV… for funsies…
Hopefully Warsh is watching and resumes QE. High yields like this will eventually hurt the stock and housing markets, and inflating those is the Fed’s main mandate. In fact, it’s a constitutional right for Americans’ stonk and housing to go up by 20% a year. Check it, it’s in the 14th Amendment somewhere.
Fed, get to work!
You mean “resumes QT” probably.
He missed the /s tag
It seems we’ve got ourselves a bit of a tug of war between the bond market as the US government who are well on their way to a soft default of the US national debt via 2% growth, 4% inflation and repressed interest rates (as much as possible).
And conservative politicians are still selling supply side economics as the solution to every problem. Let them fight it out, but first let me stop out of all my bond holdings. This is beginning to look ugly for anyone thinking of retiring soon.
LOL! When Regan took office there were less than a dozen lobbying firms in DC. How many are there now? It should be crystal clear to everyone that the political class today are nothing more than corporate whores. The average working stiff has no representation. America’s politicians are fully owned by the corporate (and foreign) lobby. The country has come full circle in 250 years. As far as the supply side goes, in the real world you need real inputs and energy to manufacture. Thanks to Israel’s war global supply lines have been disrupted. In the meantime there are now 8+ billion souls on this rock all competing for all these very real commodities and the energy required to maintain a decent standard of living. So, on the demand side, there is tremendous demand. The bottom line is that in the real world there is plenty of demand and less supply. Add to that the repricing of RISK and I think you can guess which direction interest rates and prices are going REGARDLESS of what the corporate whores in DC are doing. In fact, my money is on them making things much worse.
But we keep finding alternatives to the plants resources or the potential to use other plants resources. The universe is abundant. Just need to advance tech to provide supply.
Planets
Ah yes, the old “technology always saves us BS”.
Please, innovation requires tremendous resources, TIME, and lots of capital. I went through this process in the 90’s and went public in 2001. Yeah, bad timing. The problem is humanity seems to reproduce much faster than your magical technology can be brought to market.
I do not see why it would be a bad time to retire. Seems like an amazing opportunity to be honest.
I guess if your retirement money wasn’t really “your money” and someone else managed it…then you might be screwed…
But 6% nominal growth (2+4) with a déficit at 6% of GDP would be a stable situation.
Yes, and nominal growth ran at 8% in Q2 and will likely be higher in Q3.
Do stupid shit, win stupid prizes.
RISK is being repriced globally.
Hedge accordingly.
“I am the house now!!” Will go down in history as an epic failure of communication in my personal opinion
Another ego trip by a bureaucrat.
Taken out of context. He was talking (joking, laughingly so tbh) about how he used to be the “gambler” in currency trading (he wasn’t talking about bonds in this context) but now that he has access to all the information available in the Treasury department it’s like he’s the House now. It was all in jovial fashion.
Then the media took it and ran with it.
Go watch the whole speech. Actually I thought it was a great talk – worth watching the whole thing and not just reading the out-of-context quotes or editorials on out-of-context quotes 🤷♂️
Exactly. It was like Blankfein’s “doing God’s work” comment. I’m not a fan of Blankfein or Goldman, but that comment was clearly in jest.
“clearly in jest”
“You brood of vipers, how can you, being evil, speak what is good? For the mouth speaks out of that which fills the heart. The good man brings out of his good treasure what is good; and the evil man brings out of his evil treasure what is evil.”
My take is that their “jesting” is really gloating.
I keep thinking of all that privately floated AI debt, off the company balance sheets ($3 Trillion by some estimates)…..and the paper losses.
is this the next “sub prime mortgage” debacle on the horizon?
More debt on the street
More IPOs on the horizon
Supply, supply supply
as the Federal debt rises near $2 Trillion a year.
Not pretty.
Most of the AI debt is held by investors, not banks. These investors can go to hell without systemic risk to the banking system. However, there are some cross-connects to banks, and they would take some losses too. But the primary losses will be borne by investors. That was not the case with mortgages and MBS in 2008 that were held largely by financial institutions. And the AI debt amounts are much smaller than mortgages during the housing bust ($10 trillion or so). You cited $3 trillion, but I think that is a projection of what it will be in a few years if current trends continue, with today’s amount of actual AI debt outstanding being substantially below $1 trillion.
Central bank trend:
Grant’s Interest Rate Observer (Sept. 11, 2026, “Not the United States of America”) notes that ”… central banks accumulated 289 tons of gold, a record haul for any 2nd quarter.” (Grant’s was referring to info relayed by the World Gold Council’s June survey.)
Then goes on to opine: “These bullion purchases are increasingly coming at the expense of American-issued paper as 74% of central bankers anticipate cutting dollar-denominated assets over the next half-decade.”
Potentially a big “yikes” for bonds and stocks?
Thanks for your perspective, Wolf.
The problem here is they are all doing it. Every government is now overspending and interest rates are rocketing up everywhere. They are all being irresponsable at once, whoopie. Moreover, they are printing money (The Swiss) and spending it buying gold bars. Wish I could do that.
The outcome is well, obvious. We all go bust at once and start a new world currency. Perhaps the IMF can help us here, or the United Nations. Paper Currency is no longer a “store of value”. but is still liquidity.
Some governments are overspending more than others…
It would be interesting to compare:
– US
– Europe
– China
Sell your bonds and … buy what exactly? Greenland mining companies?
If the problem is inflation and fiat currency, why race to cash? Gold down, S&P down, Crypto down … just to fiat doesn’t make a lot of sense here 🤔
Durable goods. Heavy machinery. LiFePo battery cells and solar panels.
Quite a few options for things to make money or hold wealth with.
Would be cautious about Solar – I’ve worked in the industry and it’s not what it’s being sold as… Definitely advise looking for the risks unstated and I will leave it at that.
95% scammers…especially leasing companies.
Agree that most solar companies are pretty suspect or not worth talking to, you need to do it yourself.
I was at about 1/8th the cost that the utility was quoting. They quoted around 40k for a 12kw setup, and I instead went up to 24kw and had right around $12,000 invested.
8 week Bill went out at 4.07% today at auction.
In perspective, the Ten year was there last March. My, my, my how rates have changed.
“What risk” some have said.
BOND MARKET BLOODBATH…
TREASURY RATES HIT 22-YEAR HIGH…
Global debt tops $365 trillion as economists sound alarm over ‘vicious cycle’…
Dow falls, S&P 500 and Nasdaq end flat as 10-year Treasury yield nears 5.2%
Over now 5.208 after close
The FED is just letting the free market do its work for them.
We’re not used to this sight anymore. We’ve forgotten all about it. The last time we saw a bond market actually price risks as it saw them was over 20 years ago.
It’s looking like Warsh’s “no forward guidance” is bumping up against letting the market indicate where rates should be. Almost like some reverse forward guidance is happening. Especially with the 3month yield almost completely removing the rate cuts of 2025.
Not sure if it’s like reverse psychology or like getting poked in the chest and being told to pay attention